At 31.6%, How Well Will The Economy Function Going Forward?

By: Russ Kamp, CEO, Ryan ALM, Inc.

I occasionally receive emails from Glen Eagle Wealth, LLC, which often contain a nugget of information that inspires me to write. Yesterday’s email provided such impetus. You see, Glen Eagle provided startling statistics from a recent Barron’s article in which they shared that the richest 1% of U.S. households now control 31.6% of U.S. wealth, up from 22.9% in 1989. Meanwhile, the middle-class share of wealth fell from 35.7% to 29.6%, and the bottom 50% fell from 3.4% to 2.5%!

Group1989TodayChange
Top 1%22.9%31.6%+8.7 pts
Middle class35.7%29.6%−6.1 pts
Bottom 50%3.4%2.5%−0.9 pts

Sure, an economy can survive, and even grow, with wealth concentration at these levels. But can it truly function? Does increasing wealth concentration eventually undermines the mechanisms that sustain broad-based economic growth?

The economic concern is not simply that some people have too much money. The issue is the fact that who owns the wealth affects what happens to the next dollar of wealth. As we know, the U.S. economy is heavily dependent on household consumption (roughly 70% of GDP). As a result, a dollar of additional wealth accruing to a middle- or lower-wealth household is much more likely to translate into additional spending than a dollar accruing to an already wealthy household.

An important 2025 Federal Reserve study quantified the difference related to the impact of an additional $ of wealth on various cohorts. It estimated that growth in wealth held by the top 20% produced about 0.8 cents of additional consumption, while wealth changes among the bottom 80% produced about 7.5 cents per dollar. That is a huge difference.

The Fed concluded that increasing wealth concentration has reduced the economy’s overall propensity to consume which helps explain why there’s been weaker consumer spending since the Great Recession.

Furthermore, the IMF has found an association between greater equality and longer, more durable growth, while also finding little evidence that ordinary levels of redistribution necessarily damage economic growth.

Ownership of the American economy has increasingly migrated upward and ownership matters because capital compounds. Someone who owns a business, stocks, bonds, and/or real estate participates directly in productivity growth, corporate profits and asset-price appreciation. Someone whose economic life consists primarily of wages participates much less directly.

If productivity increases but workers don’t receive a proportional share of those gains through compensation, the gains don’t disappear. They tend to appear elsewhere through corporate profits, returns on capital, and ultimately asset values. As the data reflects, those assets are disproportionately owned by the wealthiest households.

So, you can witness an economy that continues to grow, but the impact on the lower 50% of American wage earners is reflected in:

  • Median household wealth grows slowly,
  • Housing affordability deteriorates,
  • Household debt rises,
  • Retirement security weakens, and
  • Economic mobility declines

The impact on retirement security is where we at Ryan ALM focus our attention. We believe that DB pension plans are a mechanism for allowing ordinary workers to participate indirectly in capital ownership and its subsequent returns. Stocks, bonds, real estate and other productive assets generate returns that ultimately finance workers’ retirement benefits. Unfortunately, as DB plans disappear and workers increasingly bear retirement risk individually, households that don’t accumulate substantial 401(k)/IRA balances have much less exposure to the compounding of capital.

History suggests an economy can operate this way for quite a while. The more challenging question is whether it can do so indefinitely without eventually producing weaker consumption, greater reliance on debt, reduced economic mobility, political pressure for redistribution, or some combination of all four. As I’ve said many times, asking the average American worker to fund, manage, and then disburse a “retirement” benefit through a DC plan is just silly policy. Bringing back defined benefit pension plans should provide American workers and our economy the economic boost needed longer-term.
Still Think That They Are Performance Drivers?

By: Russ Kamp, CEO, Ryan ALM, Inc.

Bonds enjoyed a nearly 4-decade bull market as U.S. interest rates plummeted from historic highs to an environment of negative real rates. It was unprecedented. As a result, bonds were perceived to be performance drivers. But are they?

We are often told by plan sponsors or their advisors that they can’t invest in a cash flow matching (CFM) strategy because de-risking the portfolio will negatively impact the fund’s ability to achieve the annual return on asset (ROA) assumption. Is that reality?

Facts:

  • The Aggregate bond index has produced a -0.29% annualized return for the 5-years ending August 31, 2026!
  • A CFM portfolio would have generated a return commensurate with its YTW (or YTM) during that 5-years. Shorter maturity (1-5-year defeasement) CFM portfolios were yielding about 1.6% at that time. That equates to a nearly 2% per year return advantage. Still think that CFM is a drag on performance?
  • U.S. inflation remains elevated. A CFM portfolio is the perfect pension inflation hedge since it is fully funding liabilities that have inflation in the projected benefits to be funded.
  • The direction of U.S. rates is uncertain, although rates have been trending higher, putting more strain on core fixed income strategies that tend to underperform when rates rise.
  • For the 28-years prior to the bond bull market (1953-1981), U.S. rates rose. Are we in a secular long-term rising rate environment?
  • Bonds should only be used for their cash flows of interest and principal upon maturity, which can be modeled to match and FUND a pension plan’s liabilities (benefits and expenses), with certainty barring any defaults.

Plan sponsors have not had this level of U.S. interest rates in roughly 20-years, providing them with a wonderful opportunity to protect the improved funded status, while securing the liquidity necessary to meet those pesky monthly obligations. Will this opportunity go unheeded just as the one presented in 2000 did? We know that failing to protect and preserve DB plans in 2000 was followed by two major equity market corrections that crushed pension funding and caused contributions to skyrocket. Do you think that sponsors of DB plans have the financial wherewithal to see contributions escalate once more? I don’t!

We recommend converting your current core fixed income allocation, with all of its interest rate risk, to a cash flow matching bond portfolio, that will carefully match and fund all of the monthly obligations as they come due. A CFM portfolio matches interest and principal against future obligations, and in doing so, eliminates interest rate risk as future values are not interest rate sensitive. If you owe a plan participant $2,000 in benefits next month, it is $2k whether interest rates are at 2% or 10%. The higher rates reduce the future value cost of the promised benefits in present value $s. We are seeing roughly 6% YTMs in our recent 30-year assignments and a >50% reduction in the cost of those future benefit payments.

You could continue to use a core fixed income allocation with all of its uncertainty or you could create certainty within a portion of your plan that doesn’t exist today. I suspect that your participants would appreciate knowing that the promised benefits are secure no matter what transpires in global markets.

Why wait?

By: Russ Kamp, CEO, Ryan ALM, Inc.

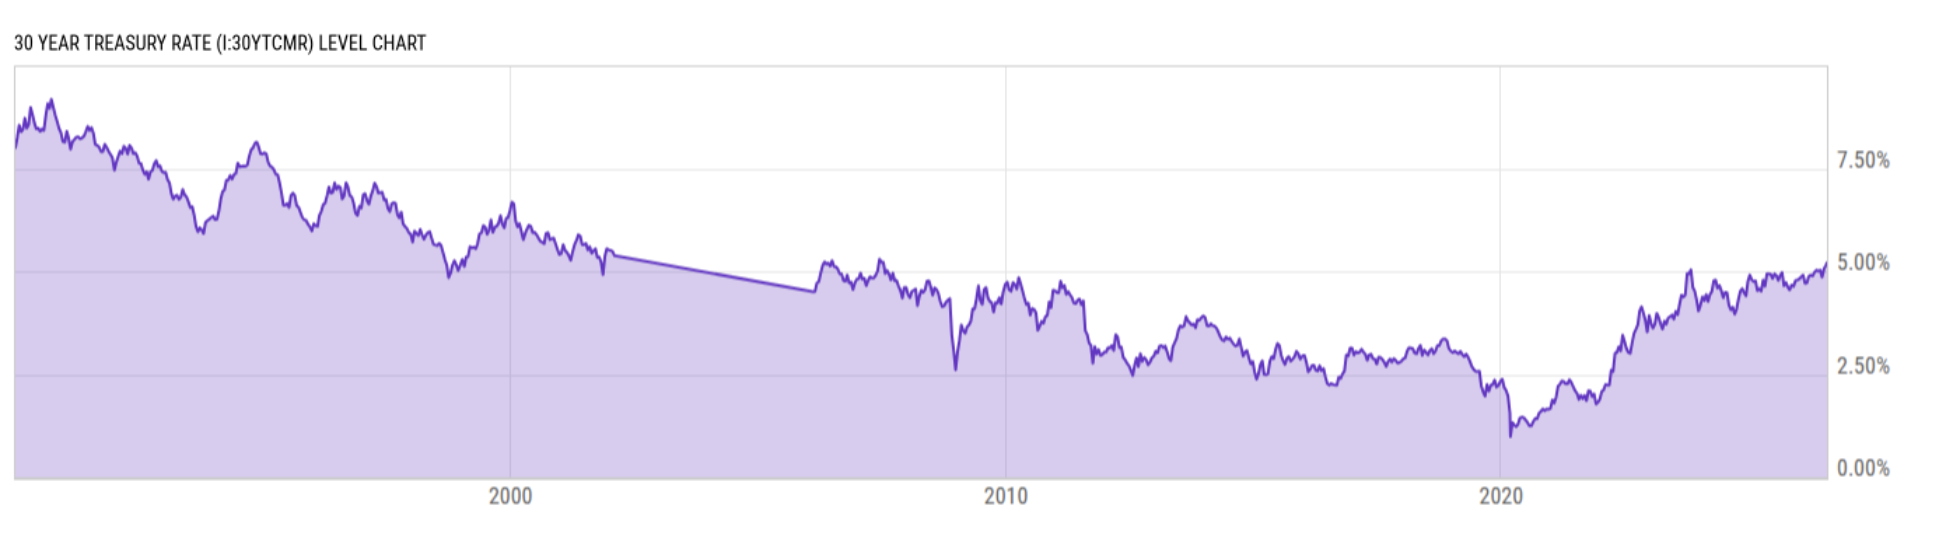
Due to great uncertainty brought on by the conflict in the Middle East and the war’s potential impact on the price of oil ($85.63 at 10:01 EST) that could drive inflation higher, U.S. long-dated Treasury yields continue to rise. In fact, the U.S. 30-year Treasury yield has not been this high (5.26%) since July 6, 2007, when the yield was at 5.28%. Where yields go from here is anyone’s guess, but I will share that oil, as represented by WTI, has risen 24.9% since June 30, 2026. Given the exposure that oil or oil-derived inputs have in more than 6,000 products, the significant rise in the recent price could impact inflation for quite some time, even if oil soon began to flow more freely.

We recently saw the average 30-year BBB+ bond trading at 110 bps above the prevailing 30-year Treasury. If that relationship is maintained, pension plans could potentially cover most of their desired return on asset (ROA) annual target (average public pension plan has a 6.75% ROA) through bonds. Should inflation spike once again, there is no telling how high U.S. interest rates could rise. Despite domestic equity’s apparent immunity to market fundamentals and geopolitical risks, there will come a time when higher U.S. yields become too attractive to ignore leading to the potential for rebalancing out of equities into fixed income. That action will likely lead to lower equity prices and falling bond yields.

So, I ask, why wait? Why wait to take risk from your current asset allocation before the markets act? Why not SECURE your benefit promises through cash flow matching (CFM) well into the future and reduce the volatility related to returns, contributions, and funded status? Why not take advantage of very attractive bond yields? As a reminder, core, active fixed income strategies are highly interest rate sensitive. Rising yields negatively impact bond prices, as seen in the performance of the Aggregate Bond Index, which is up only 0.1% annually for the 5-years ending June 30, 2026. However, a CFM strategy, which secures benefits that are future values, eliminates interest rate risk, as future values are not interest rate sensitive.

Public pension plans have done a good job of improving their funded ratios since bottoming after the Great Financial Crisis but remain only one market crash away from repeating this vicious cycle. Get off the performance rollercoaster. Secure your promises chronologically for some period into the future (your plan’s funded status should dictate the allocation). You and your participants will sleep much better knowing that the promises made will be kept.

A “Joe Friday” Moment

By: Russ Kamp, CEO, Ryan ALM, Inc.

Jack Webb, who portrayed Joe Friday in the 1950s crime drama “Dragnet”, was famous for saying in season two “all we want are the facts, ma’am.” The catchphrase eventually morphed into a shorter phrase with the help of comedian, Stan Freberg, who released his parody “St. George and the Dragonet” in which he stated, “just the facts, Ma’am”. That phrase has been carried forward in Dragnet remakes. But, I digress.

Today, I present to you a Joe Friday moment. Here are the facts: Oil prices have risen by 27% since July 6th. U.S. Treasury yields are rising across the yield curve, and the 30-year Treasury yield is within 6 bps of this cycle’s high of 5.2%. The 10-year Treasury yield is currently 4.66% as of 10:24 am on 7/22/26. Investment grade corporate bond spreads have finally started to widen although slowly. According to Morgan Stanley, the “average” yield on a BBB+ corporate is 6.23% or roughly 1.1% higher than the yield on the comparable 30-year Treasury bond. Inflation, which moderated in June, is likely to spike higher given the current direction of activity in the Middle East and its impact on shipping lanes.

These are the facts. They suggest to me, and hopefully you, that the current U.S. interest rate environment is ripe for de-risking activities through cash flow matching (CFM). Why continue to live with the uncertainty surrounding oil, inflation, rates, etc., when you can SECURE your fund’s promises in the near-term?

I wish that I had a crystal ball to help me forecast the future but alas I don’t, and I suspect that you don’t either. Given the lack of clarity related to future events, I suggest that we live in the moment. We have an environment in which the cost of those future promises (benefit payments) can be cut dramatically. An environment that brings an element of certainty to a very uncertain process. An environment in which U.S. interest rates are providing plan sponsors with a significant portion of the annual return on investment target.

We’ve seen this scenario before. At the start of the 2000s, we had pension plans extremely well-funded and contribution expenses well-controlled. That opportunity went unheeded. The result of that inaction proved to be disastrous as we saw DB pension funding get pounded by two major equity market corrections. Are you confident that another major correction isn’t around the corner?

Like Joe Friday, I rely on the facts, which I’ve now presented to you. Ignore them at your peril.

DB Pension Plans: Only One Certainty

By: Russ Kamp, CEO, Ryan ALM, Inc.

As you look at the landscape for defined benefit pension plans, it is readily apparent that there is only one CERTAINTY. Each month your fund must fulfill a promise. Benefit payments (and expenses) can’t wait to be paid. Like clockwork, B&E come due each month whether markets have behaved or suddenly made finding liquidity a challenge. What have you done to make sure that those obligations are met?

Pension plan management is primarily focused on the fund’s assets. Sponsors and their advisors put together an asset allocation framework that is singularly focused on the annual required return on assets (ROA). But those asset allocation frameworks come with a lot of volatility and uncertainty. Many factors contribute to market movements. Each one out of the control of the pension sponsor.

Do you know where stocks will be trading in 1-hour let alone 1-month, 1-year, or 1-decade? How about inflation? Interest rates? What about the Middle East, Ukraine, China, etc.? Why live with such uncertainty?

How comforting would it be to know what a pension fund’s annual contributions will be for the next 10-, 20- or 30+-years? No guessing, no budgeting woes, and no unfortunate spikes in annual contributions for public systems that harm one’s ability to support the social safety net. The process that can create this level of certainty has been used for decades: Cash Flow Matching (CFM).

As previously mentioned, current pension management approaches are return focused, which only guarantees volatility. Volatility in returns, contributions, and funded status! A CFM approach, which is the careful matching of asset cash flows (principal and interest) with the liability cash flows of benefits and expenses, will bring certainty (outside of a rare IG default) to the management of DB pensions. Importantly, liquidity is created and available when needed. There is no forced selling to fulfill those commitments. No scraping of dividend income which is detrimental to the long-term success of the equity program.

Importantly, a CFM program also “buys time” for the residual assets (presumably the alpha assets) to grow unencumbered with the goal to meet future liabilities. A longer investing horizon will dramatically enhance the probability of those assets meeting long-term return expectations.

Given that there is currently only one certainty (monthly obligations) for sponsors of DB pension plans, wouldn’t it be beneficial to create another level of certainty through the SECURING of the monthly promises? Why wait, especially given all the uncertainty facing market participants today? Ryan ALM, Inc. is always willing to provide you with a free analysis of what CFM could do for your fund. We’re ready to help you sleep better at night.

Milliman: Corporate Pension Funding Highest Since 2007

By: Russ Kamp, CEO, Ryan ALM, Inc.

Milliman has once again released its monthly Milliman 100 Pension Funding Index (PFI), which analyzes the 100 largest U.S. corporate pension plans. It would be fascinating to see how these 100 plans differ from a list just 20-years ago.

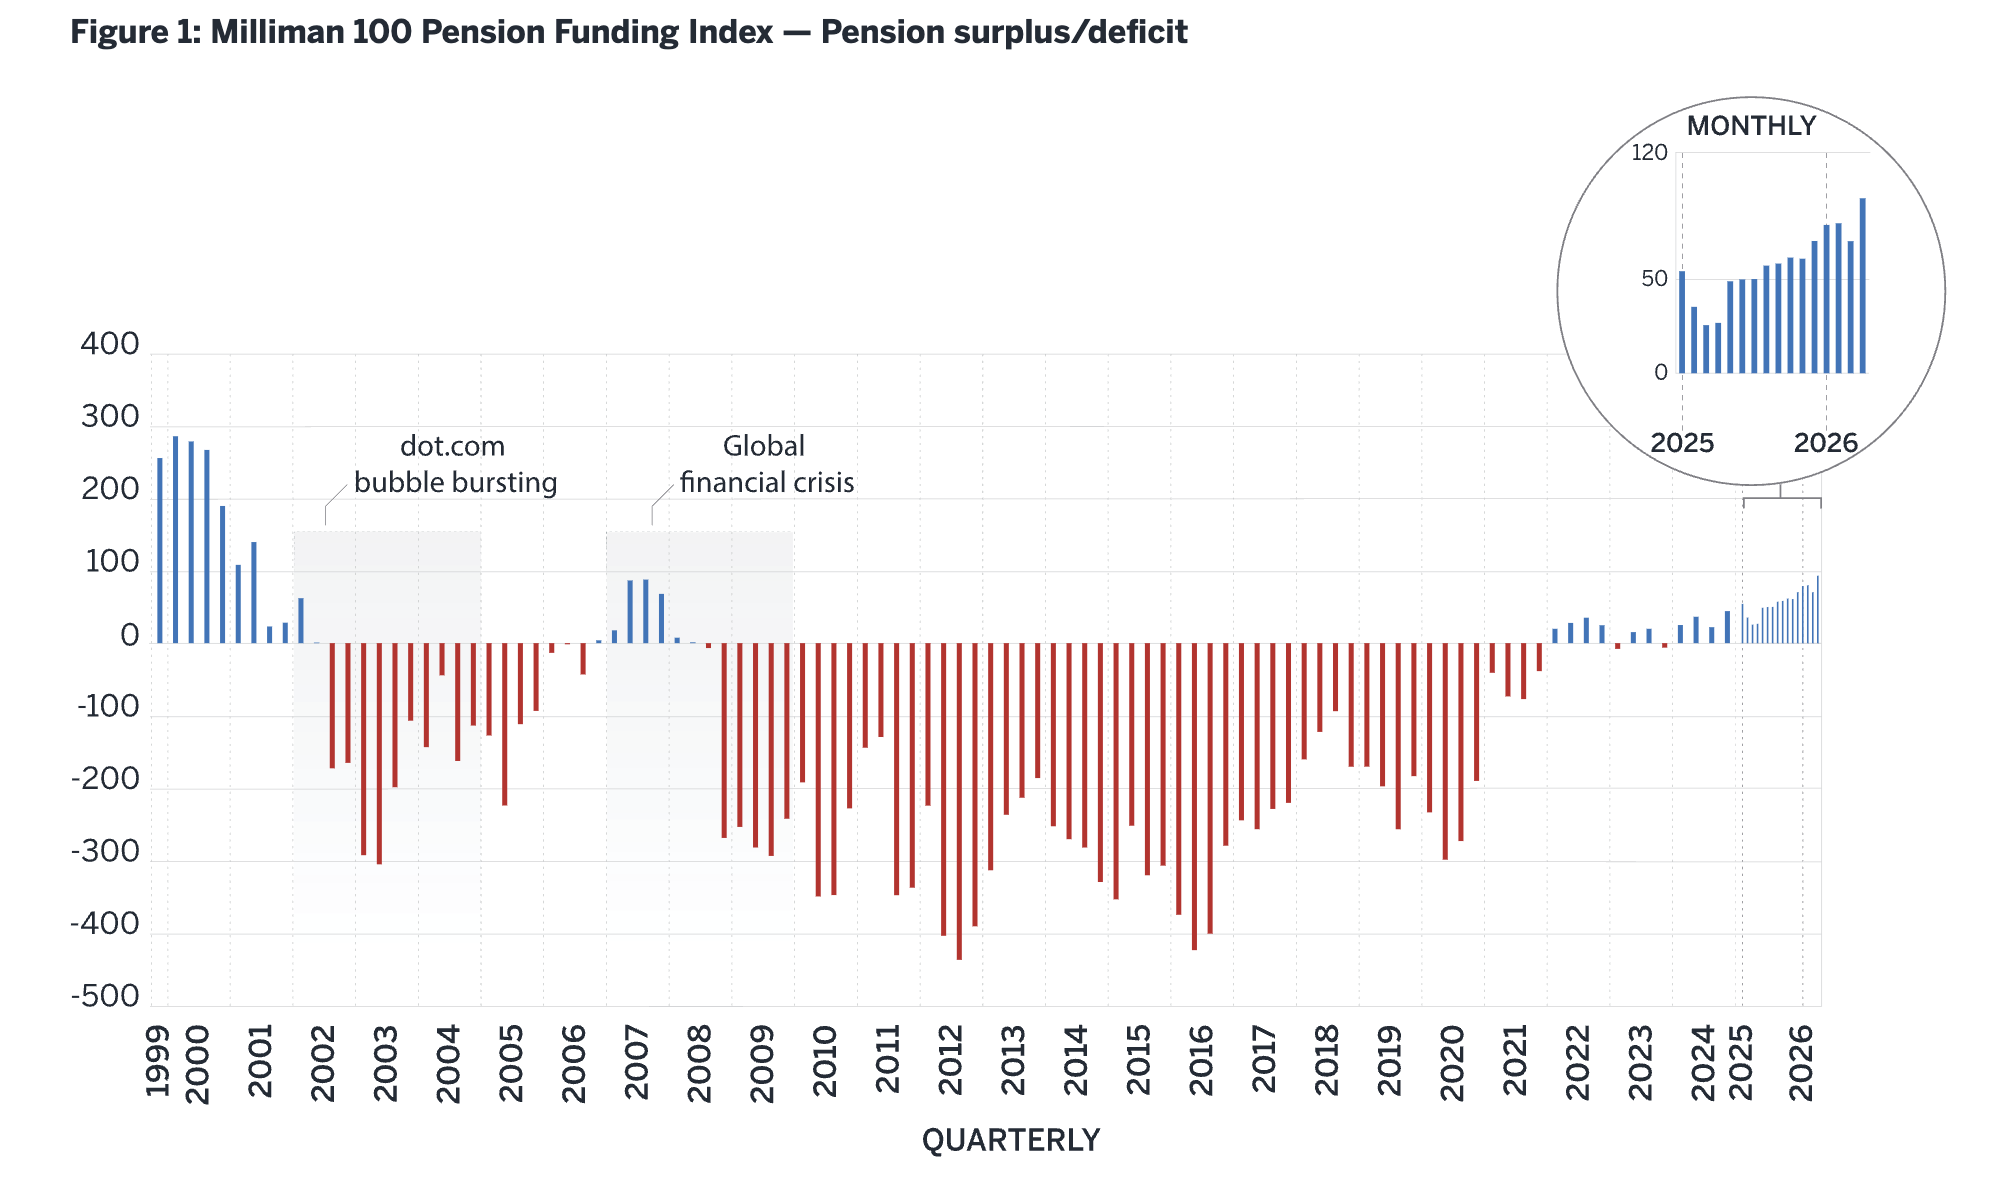
As for today’s members, the Milliman 100 PFI plans showed improved funding by $23 billion during April. These stellar results were driven by strong equity returns as the constituents averaged a 2.13% gain. As a result, the funded ratio dramatically improved from 105.9% at the end of March to 107.8% at the end of April representing the highest level of funding since October 2007, when it stood at 108.1%. Strong investment gains increased assets by $20 billion and now stand at $1.297 trillion, while the projected benefit obligation fell slightly to $1.204 trillion, as the monthly discount rate edged up one basis point, to 5.66% from 5.65%. 

“After a flat first quarter, the funding surplus grew to $94 billion at the end of April, primarily due to strong market returns,” said Zorast Wadia, author of the Milliman 100 PFI. “This means plan sponsors continue to have more pension risk management options as plans move further into surplus territory.”

Plan sponsors would be wise to seek risk reducing strategies. The previous high watermark was achieved in October 2007, just prior to the start of the Great Financial Crisis, which pummeled markets through March of 2009. As the graph below highlights, the Milliman 100 went from a small surplus in the Q3’07 to a major deficit within 6 months. It would be another 13-years before a surplus was once again created.

Plan sponsors should secure the pension promises through a cash flow matching (CFM) strategy and then actively manage surplus assets since they’ve now created a much longer investing horizon for those assets. Ryan ALM, Inc. is always willing to provide a free analysis of what is possible through CFM.

For the full Milliman report, click on the link below.

View this month’s complete Pension Funding Index.

Is Now Really the Time to Buy Stocks?

By: Russ Kamp, CEO, Ryan ALM, Inc.

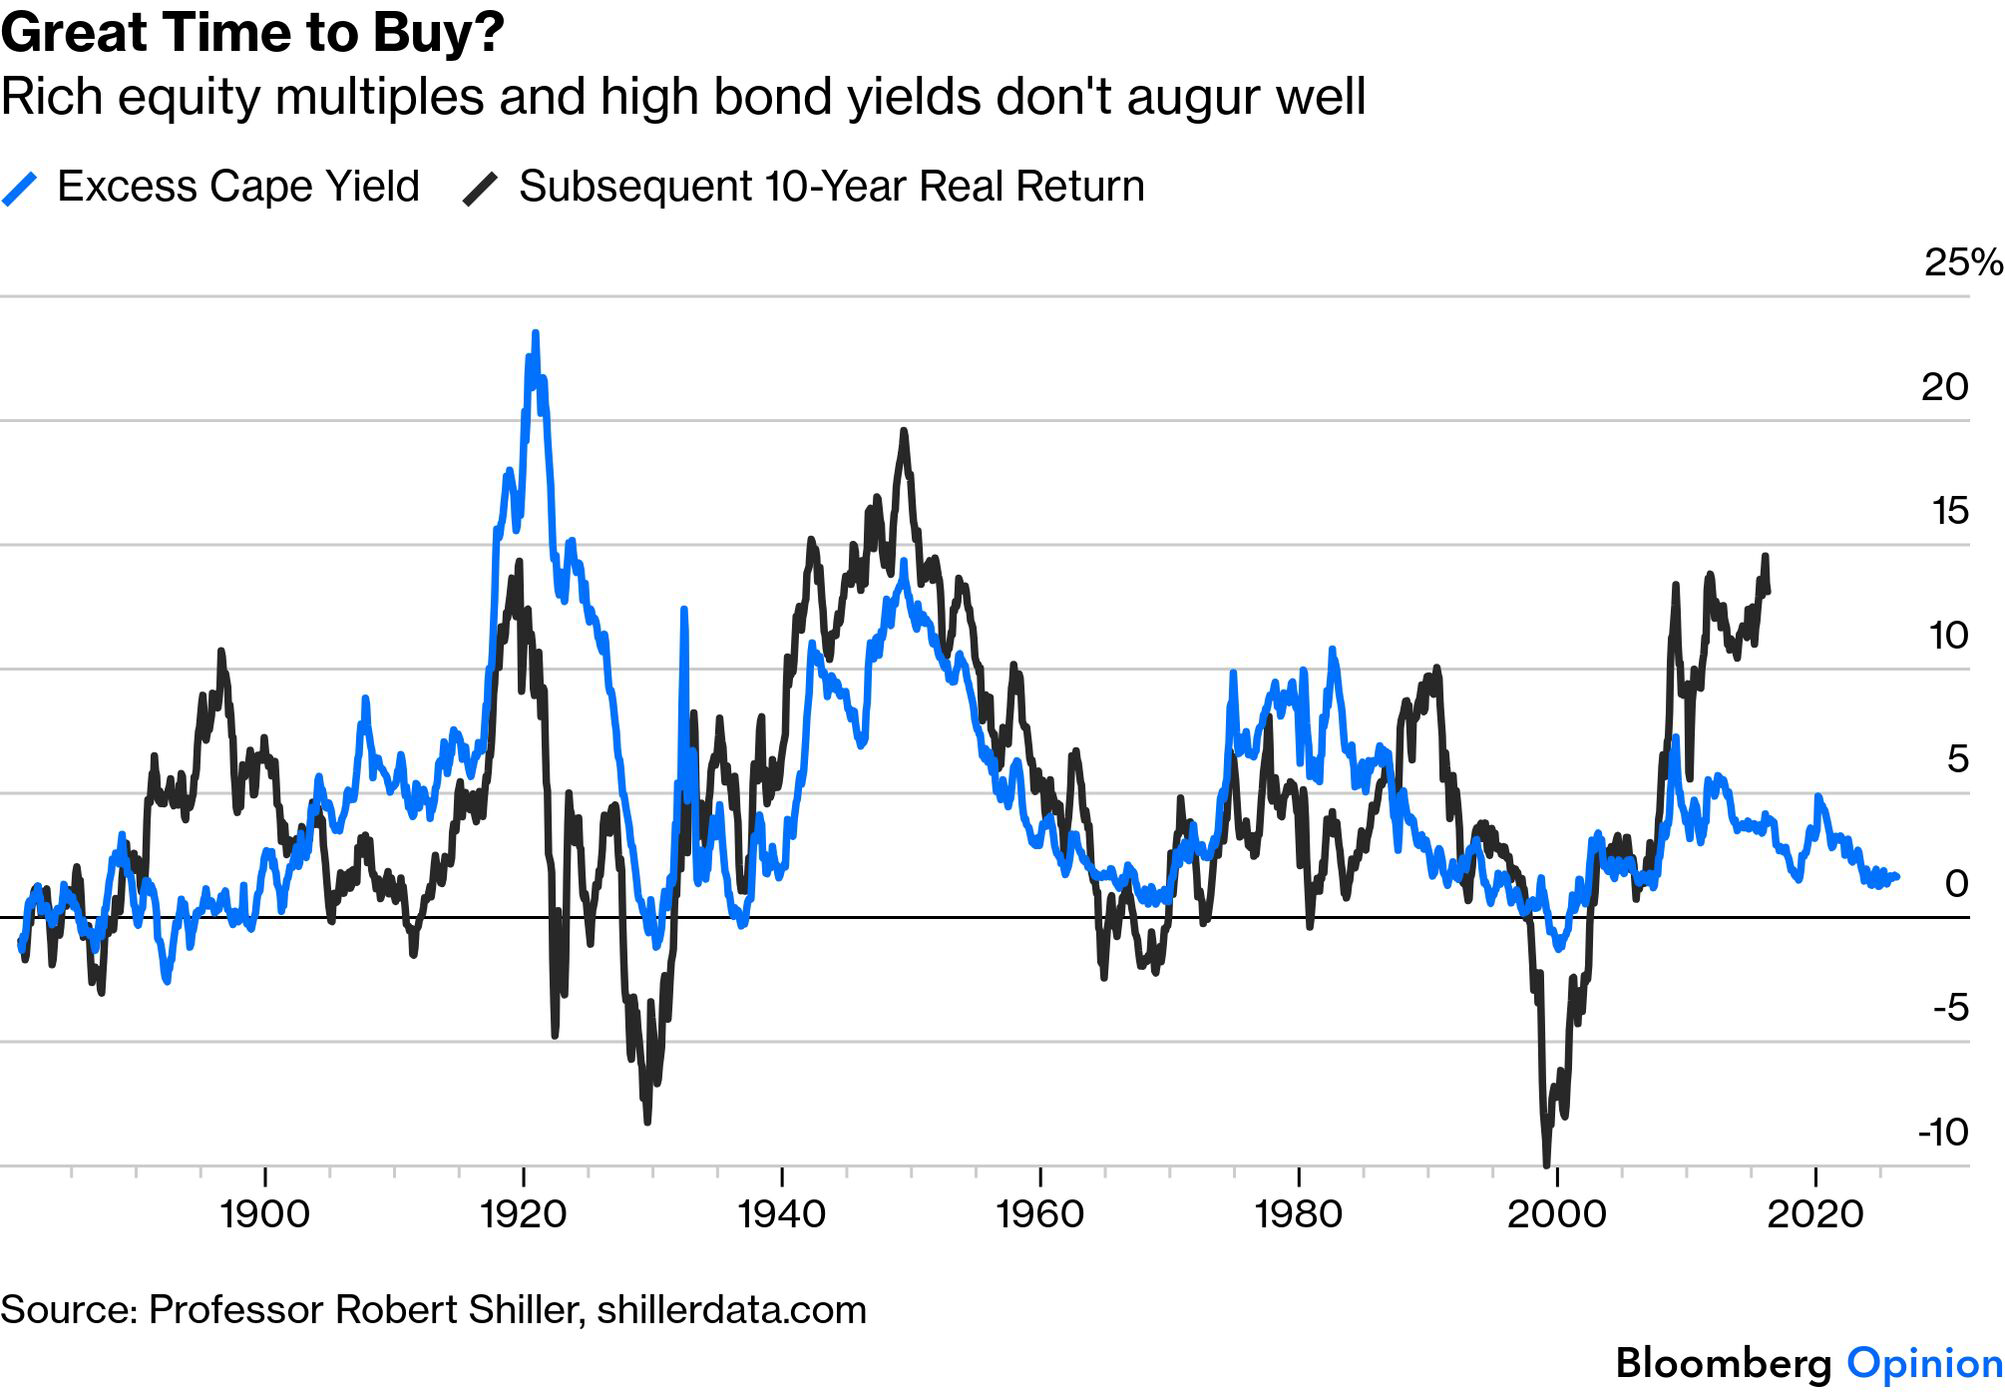
U.S. equity markets enjoyed a robust April despite myriad economic and geopolitical inputs that might have given investors pause. Should equity investors remain bullish at this time? The graph below caught my attention primarily because of the recent disconnect between the two lines related to the Shiller Excess Cape Yield (ECY) and subsequent 10-year Real Return for equities. There are many, many valuation tools that claim to provide clues about the future direction of stocks, and this is such an example. Those tools can be short-, medium-, and long-term in nature. The ECY happens to be one valuation metric that provides “guidance” for longer time frames. The current reading of 1.60% certainly looks rich relative to its long history.

In case you don’t know, the Shiller excess CAPE yield is a valuation measure that compares the stock market’s earnings yield with the “real” yield on the 10-year Treasury note. In simple terms, it asks how much extra return stocks may offer over inflation-adjusted government bonds.

How it is calculated

  • Take the inverse of the CAPE ratio, which is the market’s “earnings yield.”
  • Subtract the real 10-year Treasury yield.

So, ECY=(1/CAPE)10-year real Treasury yield

A higher excess CAPE yield suggests stocks might look more attractive relative to bonds. A lower reading suggests the equity risk premium is thinner, meaning stocks offer less return versus bonds. As mentioned above, current readings show the S&P 500 Shiller Excess CAPE Yield around 1.60% for April 2026, which is well below its long-term average of 4.60%. Another data source put it at 1.41 as of April 30, 2026.

Investors have historically used the ECY as a long-term asset allocation tool, especially when comparing stocks with Treasury bonds. It is not a short-term trading signal, but rather a rough guide to whether equities look cheap or expensive relative to real bond yields. A CAPE yield below 2% has generally signaled subdued future equity returns over the next 5 to 10 years, providing a valuation warning sign, and not an exact measure.

As a reminder, there are many valuation techniques used to identify opportunities and risk when investing in U.S. equities. Depending on a pension plan’s liquidity needs, funded ratio, willingness to take risk, etc. today’s current environment may be providing an opportunity to reduce risk by trimming equities and using the proceeds along with core fixed income assets to establish a cash flow matching mandate. In the process, the plan’s liquidity is improved, promised benefits secured, and the investing horizon extended for the residual assets. Give us a call. We are always willing to provide a free analysis showcasing how CFM can help your fund.

March Proves Challenging for Core Fixed Income

By: Russ Kamp, CEO, Ryan ALM, Inc.

March was a difficult month for active core fixed income managers, as the Bloomberg U.S. Aggregate Index fell -1.8%. Uncertainty related to the impact of the Iran War on oil prices and subsequently inflation, pushed rates higher across the Treasury yield curve. The U.S. 10-year Treasury note saw yields rise 38 bps to 4.31%.

Agencies fell -1.7% in line with Treasuries, while the Corporate sector declined -2.0%. Corporate spreads ended March with an option adjusted spread (OAS) of 88.6 bps. The best performing Corporate sector was Financials (-1.7%), while Utilities performed worst at -2.2%.

The greatest risk managing bonds is interest rate risk. Given both geopolitical (Iran, Taiwan, Ukraine) and economic risks (oil, inflation, interest rates), now is the time to significantly reduce risk within your fund, whether that be a DB pension or E&F. Why continue to ride active fixed income through these uncertain markets? One can use a cash flow matching (CFM) strategy to SECURE and fund net liabilities chronologically well into the future. In the process, interest rate risk is eliminated as future benefits and expenses are not interest rate sensitive.

Furthermore, by securing near-term liabilities, the non-bond assets can now grow unencumbered providing more time to wade through these challenging times. I have no idea how long this conflict will last. I also don’t know how much damage has occurred and that which might still happen to oil production in the Middle East. Implementing a strategy that doesn’t rely on forecasting U.S. interest rates should be a high priority today.

Making the switch is easy. Rotate your current core fixed income assets from an active investment strategy to a CFM portfolio. There isn’t a need to revisit the fund’s asset allocation. We’ll even look for opportunities to take-in-kind some of your existing holdings. You’ll appreciate not having to search each month for the liquidity to meet the monthly promises that have been made to your participants, as the CFM strategy will provide all the liquidity that you need. Moreover, the Ryan ALM CFM model is skewed to A/BBB+ corporate bonds which should outyield most generic bond indexes that are skewed to Treasuries (e.g. the AGG).


Unfortunately, the Joke Was On Us!

By: Russ Kamp, CEO, Ryan ALM, Inc.

I started raising alarm bells related to DB pension exposure to alternatives – mainly private equity and private credit several years ago, and have produced roughly a dozen blog posts that touch on this issue. You may recall some of the posts from 2024:

The Joke’s On Us!

Good Ideas are Often Overwhelmed!

Kinda Silly Question

Well, unfortunately it appears that it is time to pay the piper! As mentioned in the posts listed above, we as an industry don’t truly appreciate the idea that there is a natural capacity to EVERY investment. As an industry, we DO overwhelm good ideas and those funds that are late to the party are often left with just the crumbs in the chaffing dish.

I stumbled over a good, but scary, list of recent events within private credit. The list was compiled by Ignacio Ramirez Moreno, Host of The Blunt Dollar Podcast:

Cliffwater saw 14% redemption requests.

Morgan Stanley’s fund got 10.9%.

Blackstone hit a record 7.9%.

All three capped withdrawals below what investors requested.

Glendon Capital flagged concerns about Blue Owl’s valuations.

Pimco called it “a crisis of really bad underwriting.”

JPMorgan’s marking down loans and tightening lending to private credit funds.

Partners Group thinks defaults could double.

Pimco’s predicting a “full-blown default cycle.”

Apollo’s saying the pain could last 12-18 months.

Well, that is some list! In addition, I was always quite skeptical of the credit quality that was assigned to these companies, and I guess that I wasn’t too far off given that 43% of private credit borrowers have negative free cash flow. Furthermore, the U.S./Israel vs. Iran war won’t help either, as inflation expectations have ratcheted higher reducing significantly the prospects for Fed action leading to lower rates. In fact, it would not be surprising to see the Fed have to raise rates. If such an action occurs, the higher interest rates could exacerbate the current challenging environment for private debt borrowers and their income statements.

Let’s see how the pension plan sponsor community and their advisors deal with private credit’s first real crisis. It should be both interesting and likely painful.

What is the PCE Price Index Telling Us?

By: Russ Kamp, CEO, Ryan ALM, Inc.

As most investors know, the Federal Reserve’s primary inflation measure is the Core Personal Consumption Expenditures (PCE) price index. The Federal Open Market Committee (FOMC) targets 2% annual PCE inflation while trying to balance long-term price stability and maximum employment. The PCE is produced by the Department of Commerce. Why the PCE? The PCE inflation index covers broad household spending and importantly it adjusts for shifts in consumer behavior, unlike fixed-basket indexes, such as the Consumer Price Index (CPI). Furthermore, the PCE reflects actual expenditures economy-wide and updates the index weights more dynamically. The goal of the PCE inflation measure is to help gauge underlying trends in the broader economy.

The most recent PCE inflation data was published as of today, March 13, 2026, covering a period through January 2026. Core PCE (excluding food and energy) ticked up to 3.06% in January 2026, after having touched 3% at year-end. Cleary, this reading remains well above the Fed’s 2% target, reflecting persistent underlying pressures that may become even more dramatic with the 41% increase per barrel of WTI registered since the close on Friday, February 27th.

The PCE inflation measure has recently accelerated while CPI cooled primarily due to differences in housing weights (lower in PCE) and consumer behavior adjustments.

MonthHeadline PCE (%)Core PCE (%)Headline CPI (%)Core CPI (%)
Dec 20252.93.02.72.9
Jan 20262.93.12.42.5
Feb 2026 (est)??2.4?

The fact that core PCE has now exceeded 3% must be worrying for the FOMC/FED that are also dealing with broader economic pressures, such as employment and US interest rates. Speaking of rates, historically the U.S. 10-year Treasury note has traded at a premium yield to inflation of roughly 2%, with periods as high as 3% or greater. The 10-year Treasury note is currently trading at a yield of 4.25% (as of 10:29 am) suggesting that a “normal” spread should have the YTM at 5.1%.

Given the great uncertainty related to current economic and geopolitical issues, it would not be surprising to see the Treasury yield curve continue to shift upwards. Such a move would create a wonderful environment for pension plan sponsors to de-risk through a cash flow matching (CFM) strategy. It is time to bring an element of certainty to the management of DB pensions to reside in a state of great uncertainty! Don’t wait to explore the amazing benefits provided by CFM.