Ryan ALM, Inc. – We Offer A Turnkey System

By: Russ Kamp, CEO, Ryan ALM, Inc.

Ryan ALM helps defined benefit pension plans understand and manage the COMPLETE economics of their pension promise. Using cash flow projections of contributions, benefits, and expenses, the Ryan organization uses its proprietary liability valuation methodologies (ASC 715 discount rates), its trademarked Custom Liability Index (CLI), and our cash flow matching strategy that we call the Liability Beta Portfolio (LBP) to develop investment SOLUTIONS designed to align plan asset cash flows with liability cash flows. It is the SECURING of those future obligations that should be the paramount activity when managing a pension plan.

We refer to this process as a turnkey system, which Ron Ryan, Ryan ALM’s Chairman, recently described in great detail. We believe that our firm is unique in this regard. Unfortunately, pension plans today receive an actuarial update at most once per year, perhaps 4-6 months delayed. They rely on their asset consultants to create an asset allocation that should reflect the funded status but often the allocations are driven by the ROA. Investment managers are then retained to manage strategies based on the asset allocation, but not the plan’s liabilities. That seems pretty disjointed to us.

Ryan ALM’s competitive advantage is its proprietary turnkey system that integrates:

  • Liability valuation through discount-rate modeling
  • Cash-flow forecasting
  • Liability benchmark construction
  • Portfolio implementation
  • Ongoing monitoring

A true repeatable framework focused on the long-term SUSTAINABILITY of pension plans. Most pension plans don’t have such a system. They receive quarterly investment reports and annual actuarial valuations, but nobody integrates the assets and liabilities into a synergistic decision-making framework. Have you ever wondered: “How has the plan’s financial health changed since our last meeting, and what risks should we be paying attention to?” If not, you should be. Do you know where your liquidity is going to come from to meet those ongoing monthly obligations?

Ryan ALM would be happy to provide you with a free cash flow analysis based on our proprietary turnkey system. Given significant uncertainty today, a short 30-minute conversation followed by our analysis could ensure that your fund is set up for long-term success.
It is Our Mission!

By: Russ Kamp, CEO, Ryan ALM, Inc.

The individual professionals on the Ryan ALM, Inc. team have both a personal and professional mission which drives us every day! What is that mission? We are driven with the goal of protecting and preserving defined benefit pension plans, which we believe are the only true retirement plans. Any other “retirement” vehicle pales in comparison. Yet, our industry has adopted practices which we believe are detrimental to the long-term stability of these critically important plans.

Pursuing an objective focused on return has created an environment that has these DB plans on a perpetual rollercoaster of performance, ultimately creating unnecessary instability and uncertainty as it relates to both contributions and funded status. As a reminder, we believe that the primary objective in managing a DB pension plan is to SECURE the promised benefits at a reasonable cost and with prudent risk. It is not a performance objective.

Recently, I reviewed a pension plan that believed its biggest challenge was improving returns. After examining its cash flow needs, we discovered the larger issue was liquidity. By addressing liquidity first, the trustees reduced risk, a key action in these uncertain times, while improving confidence in their ability to meet future benefit payments. Furthermore, most trustees I speak with are wrestling with the same issues—liquidity, uncertainty, and how much risk is appropriate at this stage of the investing cycle.

Through Cash Flow Matching (CFM), a dedicated investment-grade bond portfolio in which we carefully match asset cash flows of principal and interest against the liability cash flows of benefits and expenses, we are able to bring certainty to your cash flow needs through enhanced liquidity. I’d be happy to walk through your plan’s cash flow profile and show you how a cash flow matching approach would support your current asset allocation.

Every pension plan is different, but every trustee shares the same responsibility: ensuring promised benefits are paid. Markets will do what markets do. Interest rates will rise and fall. Economic uncertainty will come and go. The question is whether your pension plan is structured to withstand those events without jeopardizing the promises made to participants.

If you’re not completely certain that your fund is structured appropriately, let us at Ryan ALM work with you to protect and preserve your DB plan, as it is our collective mission. Your fund’s participants will appreciate knowing that their promised benefits have been secured for some period of time. If you’d like a second opinion on your plan’s liquidity profile, cash flow needs, or overall asset allocation strategy, let’s talk. A 30-minute conversation may help you see risks—and opportunities—that aren’t visible through a funded ratio or return assumption lens.

As Clara Would Ask: “Where’s the Beef?”

By: Russ Kamp, CEO, Ryan ALM, Inc.

Clara Peller became famous as a result of her participation in the 1984 Wendy’s ad campaign in which she famously asks, “where’s the beef?”. Her comment was of course in reference to Wendy’s competitors whose burgers were less than impressive in size.

Yesterday, I produced a post highlighting the many benefits of cash flow matching (CFM), including providing ALL the necessary liquidity, creating an extended investing horizon, providing certainty and security, lower management fees, stable contributions/funded ratio, and the elimination of interest rate risk.

Despite the plethora of benefits, we occasionally receive push back from plan sponsors and their advisors on the use of CFM because some folks believe that they can identify a fixed income manager or group of bond managers that will “outperform” a CFM portfolio thus supporting the ROA target, as if that was the primary objective. As we’ve stated many times, the primary objective in managing a defined benefit plan is to SECURE the promised benefits at a reasonable cost and with prudent risk. It is NOT a return objective.

But, let’s just say for argument’s sake that using bonds in your fund was for return purposes. The greatest risk in managing U.S. fixed income is interest rate risk. Yes, most of us grew up in this industry during the last 40+ years when interest rates declined from ridiculous levels (10-year Treasury yield was 15.1% on the day I entered this business (October 1981)) to the zero-rate environment created by Covid-19. Most core fixed income managers continue to use the Barclays Aggregate (formerly Lehman) Index as the benchmark. The YTW on that index is 4.67%. A yield that is certainly below most, if not all, ROA targets for DB pensions (certainly public and multiemployer plans). Moreover, the yield on the Ryan ALM CFM is over 5.00% since it is a portfolio of primarily A/BBB+ corporate bonds. Our CFM should outperform the Agg by the yield difference given the same or similar duration.

Furthermore, that core fixed income manager(s) will actively position exposures related to the types of bonds, including Treasuries, agencies, MBS/ABS/CMOs, corporates, duration, sectors, etc. relative to the index to try to capture some excess return. But is “active management” adding value and what is the annual volatility or standard deviation associated with that activity? Many bond investors benefited from the nearly 4 decade decline in rates, as bond prices rose when yields fell. However, most investors today weren’t around for the 28-years prior to 1981 when U.S. interest rates rose! Things were much different for bond managers then.

Do you know in which direction interest rates will travel during the next 1-, 3-, 5- or more years? We, at Ryan ALM, certainly don’t and we don’t need to know. Given that the greatest risk to an active core bond strategy is rates, why do you remain confident that your manager(s) will consistently meet or exceed the index’s return? With CFM, there is no guessing as to what rates will do. On the day that the CFM portfolio is created, asset cash flows of principal and interest are matched against the liability cash flows of benefits and expenses. As rates move (either up or down), that careful match remains, which is how we can claim that both security and certainty (barring a default) is achieved. Your core manager can’t make that claim because the Aggregate index looks nothing like your unique liabilities.

By the way, the “Agg” is up only 0.17% for the 5-years ending May 31, 2026. On a YTD basis, the index has produced a 0.38% return. Do you think that those results are helping or hurting your fund? As Clara asked 42-years ago (oh, my!), “where’s the beef?” I can tell you. It is found in a CFM strategy and it is a whopper! 

What Do You Need?

By: Russ Kamp, CEO, Ryan ALM, Inc.

We are now nearly through the first half of 2026. That doesn’t seem possible. Despite the very uncertain economic and geopolitical environment, U.S. equities continue to march higher, especially for stocks associated in any way with AI. As a result, I suspect that a number of plan sponsors/trustees will say that they only need for those good times to keep rolling. But is that possible given current valuations? On the other hand, perhaps you are a sponsor/trustee that believes that nothing grows to the heavens, and as a result you might be looking to take a little risk out of your current asset allocation. If so, I have a suggestion. But first, here are a few questions that I’d like you to consider:

  • How is your fund’s current liquidity profile?
  • If raising the necessary monthly liquidity is challenging, how would you like a strategy that provides the liquidity you need, net of contributions, each month chronologically as far out as the strategy’s allocation will take you?
  • Given current equity valuations, how would you like an extended investing horizon that buys time for your fund’s alpha assets to wade through potentially choppy near-term markets without fear of forced selling to meet benefits and expenses?
  • How does reducing investment management fees sound?
  • How would you like to stabilize contribution costs and the funded ratio?
  • The investment strategy that I am referring to brings an element of certainty to the management of pensions that sorely lack that today. How does that sound?
  • How do you think your participants would appreciate knowing that their promised benefits are SECURED for the period that your new strategy covers?
  • Interest rates are the greatest threat to a fixed income (bond) investment program. How would you like a strategy that is not impacted by changes in U.S. interest rates?

Come on Kamp, is there really an investment strategy that can secure the benefits, buy time for the residual assets to just grow unencumbered, lower investment fees, eliminate interest rate risk, and provide the liquidity that I’ll need to pay my monthly bills? There sure is! For regular readers of this blog, you likely know that I’m referring to Cash Flow Matching (CFM) as the investment strategy.

This bond product carefully matches the asset cash flows of principal and interest with the liability cash flows of benefits and expenses. By doing so, the benefits are secured for the length of the program. We have assignments from 3-years to 30-years. We’ve just bought time for the assets not engaged in CFM to wade through any ugliness in markets without fear of liquidation to meet monthly payouts. Furthermore, we are matching future values which are not interest rate sensitive. A $1,000 benefit payment next month is $1,000 whether rates are at 2% or 10%. Finally, we provide our investment management services at attractively low rates.

We also provide a free analysis to any sponsor who’d like to know how CFM could benefit their fund. We’ll produce a CFM portfolio that will help you understand the potential cost reduction in the value of those future benefit promises. In today’s rate environment, we can produce portfolios that reduce the future cost of providing benefits by roughly 2% per year. Ask us to cover the next 10-years and the savings becomes very attractive and meaningful. We are ready when you are!

Unique Liabilities Require A Unique Solution

By: Russ Kamp, CEO, Ryan ALM, Inc.

Most pension plans have exposure to fixed income. Perhaps not as much as they did prior to 2000, but today’s common thinking is that the current exposure is enough to act as a buffer should equity markets not continue along this momentum fueled path, and finally, to support the monthly liquidity needs of the fund. But are those the right reasons to use bonds and what type of fixed income should be used to accomplish those objectives?

We observe that most funds use a variety of investment grade bonds (Treasuries, Agencies, Corporates, etc.) and they have that collection benchmarked to a generic index such as the Bloomberg U.S. Aggregate Index (a.k.a. the Agg). As a reminder, the Agg was created by Ron Ryan when he was Head of Research at Lehman Brothers a few years ago. But, again, is this the right approach? We at Ryan ALM, Inc. believe that bonds should only be used for their cash flows (principal and interest) and not as a performance driver. Bonds are perhaps the only asset class with a known cash flow equal to the value at maturity (PAR) and contractual interest payments. Those known cash flows can be modeled to meet the plan’s ongoing liability cash flows (benefits + expenses). 

Which brings me to the point that every pension plan’s liabilities are unique, and as such, no generic index such as the Agg could possibly match a plan’s liabilities. If the asset cash flows don’t match and fund the liability cash flows (benefits and expenses), the plan is subject to unnecessary interest rate risk. Again, given that every pension plan has a unique set of liabilities this would suggest that each pension plan needs to have an investment strategy created specifically for their cash flow needs. Cash Flow Matching (CFM) is an investment strategy with a very long and successful history. An appropriately crafted CFM portfolio will meet and fully fund chronologically the liability cash flows as far into the future as the allocation to the CFM strategy lasts.

We take great pride in our proprietary CFM optimization modeling, which we began using at Ryan ALM’s founding in 2004. Having the ability to tailor unique solutions to client specific issues/requests is a hallmark of our firm, and this capability is being recognized throughout the industry. In fact, we recently received this feedback from an ALM expert at a large asset/liability consulting firm, who stated that I’m “impressed with the team’s ability to build portfolios for such non-standard cashflow streams.” Thank you!

We’d be happy to demonstrate our capability and we’re always willing to provide a free analysis highlighting how your fund could benefit through CFM and Ryan ALM’s expertise. Just call us.

Pension Plan Sponsor: “I Wish that I could…”

By: Russ Kamp, CEO, Ryan ALM, Inc.

In October, I will celebrate my 45th year in the pension/investment industry. I’ve been truly blessed, but also frustrated by activities that I deem detrimental to the successful management of DB pension plans.

First and foremost, I believe that a majority of folks think that achieving the return on asset assumption (ROA) is the primary objective in managing a DB pension plan. This is an incorrect assumption! Creating an asset allocation targeted at a return only guarantees annual volatility, and NOT success.

Second, meeting monthly liquidity through the sweeping of interest, dividends, capital distributions, and worse, the selling of investments harms the long-term return of your fund.

Third, using core fixed income as a return generator is not a sound strategy, as bonds are highly interest rate sensitive, and who knows the future direction of rates.

That being said, if I were a pension plan sponsor, I’d wish that I could find an investment strategy that provided: All of the plan’s liquidity needs, certainty for a portion of that plan, and a longer investment horizon for my alpha generating assets (non-bonds) so that I enhance the probability of achieving the desired outcome.

Great news – there is such a strategy. Cash Flow Matching (CFM) is designed to use investment-grade bonds for their cash flows of interest and principal (upon maturity) to match liability cash flows of benefits and expenses for as far out as the allocation goes. Furthermore, it extends the investing horizon for the non-bond assets so that they can wade successfully through choppy markets without being a source of liquidity. Finally, there is an element of certainty (minus that rare occurrence of an IG bond default) absent in the management of DB pension plans outside of a pension risk transfer (PRT) or an annuity.

I believe that the primary objective in managing a DB pension plan is to SECURE the pension promise at low cost and with prudent risk. Does focusing on the ROA secure benefits – no. The “sweeping” of dividends, interest, and capital distributions to meet ongoing liquidity needs can negatively impact the plan’s long-term return. Guinness Global (U.K. investment shop) produced a study that said sweeping dividends and not reinvesting them reduced the return to the S&P 500 by 47% over 10-year periods back to 1940 and 57% for 20-year periods.

Finally, bonds are highly interest rate sensitive. After a nearly 40-year decline in U.S. interest rates which drove bond prices up and yields down, we have seen rates rise to more average levels where they are holding leading to very weak fixed income returns for recent performance periods. Matching asset cash flows with liability cash flows eliminates interest rate risk for that portion of the portfolio, as benefits and expenses are future values that are not interest rate sensitive. Furthermore, Ryan ALM’s approach is to use 100% IG corporate bonds to build the CFM portfolio. A 100% IG portfolio will outperform a core active fixed income portfolio by the yield differential given the core portfolio’s exposure to agencies and Treasuries.

Question: If you had the opportunity to bring some certainty to the management of pensions, why wouldn’t you do it? If not, please share with us why not.

A Ryan ALM, Inc. Client Portfolio Review

By: Russ Kamp, CEO, Ryan ALM, Inc.

We are blessed to work with a wonderful array of clients, both pension and E&F. They have chosen to bring an element of certainty to the management of their fund. We commend them for that decision and thank them for the confidence that they’ve shown in us and our cash flow matching (CFM) strategy/capability.

Our client relationships begin with the acquisition of important inputs including projections of benefits/grants, expenses, and contributions as far into the future as possible. Most often these are provided by the fund’s actuary. The next step in building a portfolio is to create a Custom Liability Index (CLI), that will establish the framework for monthly distributions.

Upon completion of the CLI, we will work with the client and their advisors to determine the appropriate allocation to CFM. We often suggest converting the current core fixed income allocation since bonds should only be used for their cash flows. Once that has been determined, we will build a high quality bond portfolio (most often 100% IG corporate bonds) that carefully matches asset cash flows of interest and principal with the liability cash flows (benefits and expenses (B&E)).

Once this portfolio is built, we have created an element of certainty for the plan sponsor, as asset cash flow will march in harmony with the liability cash flows barring a bond default, which occurs <0.2% annually (40-year study by S&P). It is only upon changes in the actuaries forecast that lead us to adjust the portfolio, and those annual changes tend to be quite insignificant.

Now the fun part: We are often asked to provide quarterly updates on our portfolio, which couldn’t be any easier. My last portfolio review lasted about 37 seconds. I stated that the projected cash flows that had been shared with us were matched by the asset cash flows, and that there have been no instances in which monthly cash flow needs were not met in their entirety. Furthermore, there have been no defaults in our portfolio ensuring that future cash flow needs will also be met as required. Any questions?

As you can see, there is no need to fret about the direction of U.S. interest rates. No worry about what the “Fed” may do today, tomorrow, or next year. No forecasting of the economic environment, inflation, and/or the geopolitical landscape. Once the CFM portfolio is constructed, the cost savings (cost to fund future B&E) is known and locked in. How many investment managers can tell you how the portfolio will perform over the duration of the program?

Why wouldn’t you want to bring an element of certainty to your fund? Wouldn’t a “sleep-well-at-night” strategy bring comfort to you and those that you serve? If the true objective in managing a defined benefit fund is to SECURE the promised benefits at low cost and with prudent risk, is there another investment strategy that can match the positive attributes of CFM? If we’ve grabbed your attention, reach out. We provide a free analysis of how CFM can make your fund less volatile and uncertain.

March Proves Challenging for Core Fixed Income

By: Russ Kamp, CEO, Ryan ALM, Inc.

March was a difficult month for active core fixed income managers, as the Bloomberg U.S. Aggregate Index fell -1.8%. Uncertainty related to the impact of the Iran War on oil prices and subsequently inflation, pushed rates higher across the Treasury yield curve. The U.S. 10-year Treasury note saw yields rise 38 bps to 4.31%.

Agencies fell -1.7% in line with Treasuries, while the Corporate sector declined -2.0%. Corporate spreads ended March with an option adjusted spread (OAS) of 88.6 bps. The best performing Corporate sector was Financials (-1.7%), while Utilities performed worst at -2.2%.

The greatest risk managing bonds is interest rate risk. Given both geopolitical (Iran, Taiwan, Ukraine) and economic risks (oil, inflation, interest rates), now is the time to significantly reduce risk within your fund, whether that be a DB pension or E&F. Why continue to ride active fixed income through these uncertain markets? One can use a cash flow matching (CFM) strategy to SECURE and fund net liabilities chronologically well into the future. In the process, interest rate risk is eliminated as future benefits and expenses are not interest rate sensitive.

Furthermore, by securing near-term liabilities, the non-bond assets can now grow unencumbered providing more time to wade through these challenging times. I have no idea how long this conflict will last. I also don’t know how much damage has occurred and that which might still happen to oil production in the Middle East. Implementing a strategy that doesn’t rely on forecasting U.S. interest rates should be a high priority today.

Making the switch is easy. Rotate your current core fixed income assets from an active investment strategy to a CFM portfolio. There isn’t a need to revisit the fund’s asset allocation. We’ll even look for opportunities to take-in-kind some of your existing holdings. You’ll appreciate not having to search each month for the liquidity to meet the monthly promises that have been made to your participants, as the CFM strategy will provide all the liquidity that you need. Moreover, the Ryan ALM CFM model is skewed to A/BBB+ corporate bonds which should outyield most generic bond indexes that are skewed to Treasuries (e.g. the AGG).


Trouble Paying the Bills?

By: Russ Kamp, CEO, Ryan ALM, Inc.

“The worst thing that can happen,” Andrew Junkin, CIO, Virginia Retirement System says, “is that you’re a forced seller in any market.”

That quote appeared in a Chief Investment Officer article from March 4, 2026. We couldn’t agree more with Mr. Junkin. Despite improved funding, public funds are being challenged to find adequate cash flow to meet the monthly benefits and expenses. Two factors are at play: 1) improved funding leads to lower annual contributions, and 2) much heavier allocations to alternatives have dried up liquidity, as expected capital distributions fail to materialize.

According to a report by NIRS, from 2001 to 2023, public pension plans shifted roughly 20% of public equity and fixed income into alternatives such as private equity, real estate, and private credit. These are illiquid investments. Despite the “wisdom” of the pension crowd, illiquidity is a RISK and not an alpha generator. As more assets shifted into these illiquid investments, the trades became ever more crowded reducing liquidity further. That is, unless one was willing to take a significant haircut through the secondary markets.

As a reminder, public pension funds are designed to become cash-flow negative over time. Contributions into these funds exceed benefits in earlier decades, building a corpus to be used to fund retirements down the road. They are designed to have the last $ pay the last promised benefit. There is no inheritance waiting for the last few beneficiaries.

You want to have adequate liquidity that isn’t forcing the sale of assets at inopportune times? Develop an asset allocation strategy that bifurcates your assets into two buckets – liquidity and growth – and stop the focus on the ROA as if it were the Holy Grail. It isn’t! Use a cash flow matching (CFM) investment strategy to ensure that abundant liquidity is available from next month as far into the future as your allocation goes. The remainder of the assets go into the growth bucket. If you still want to maintain a heavy allocation to alternatives, they can now grow unencumbered as they are no longer a source of liquidity.

The allocation should be driven by the pension plan’s funded ratio and ability to contribute. We recently provided a large fund with an analysis that showed a plan with <50% funding could still secure the promised NET benefits for the next 33-years, while creating a substantial surplus that could now be managed as aggressively as members of that Board could withstand. Not only are the promised benefits secure, but so are the participants who can now sleep well at night knowing that myriad risks won’t sabotage their golden years.

ARPA Update as of March 20, 2026

By: Russ Kamp, CEO, Ryan ALM, Inc.

I’m sure that folks were very (perhaps bitterly) disappointed not to get my weekly update yesterday on the PBGC’s implementation of the ARPA pension legislation. I was traveling for business yesterday, but unlike many travelers, my experience at Newark Airport was shockingly positive. I have heard of 4-6 hour waits to get through security and planes that are forced to leave the gate with as few as 5 passengers. Various estimates put the daily impact of these disruptions at $285 million to $580 million once a 10% reduction in flights occurs.

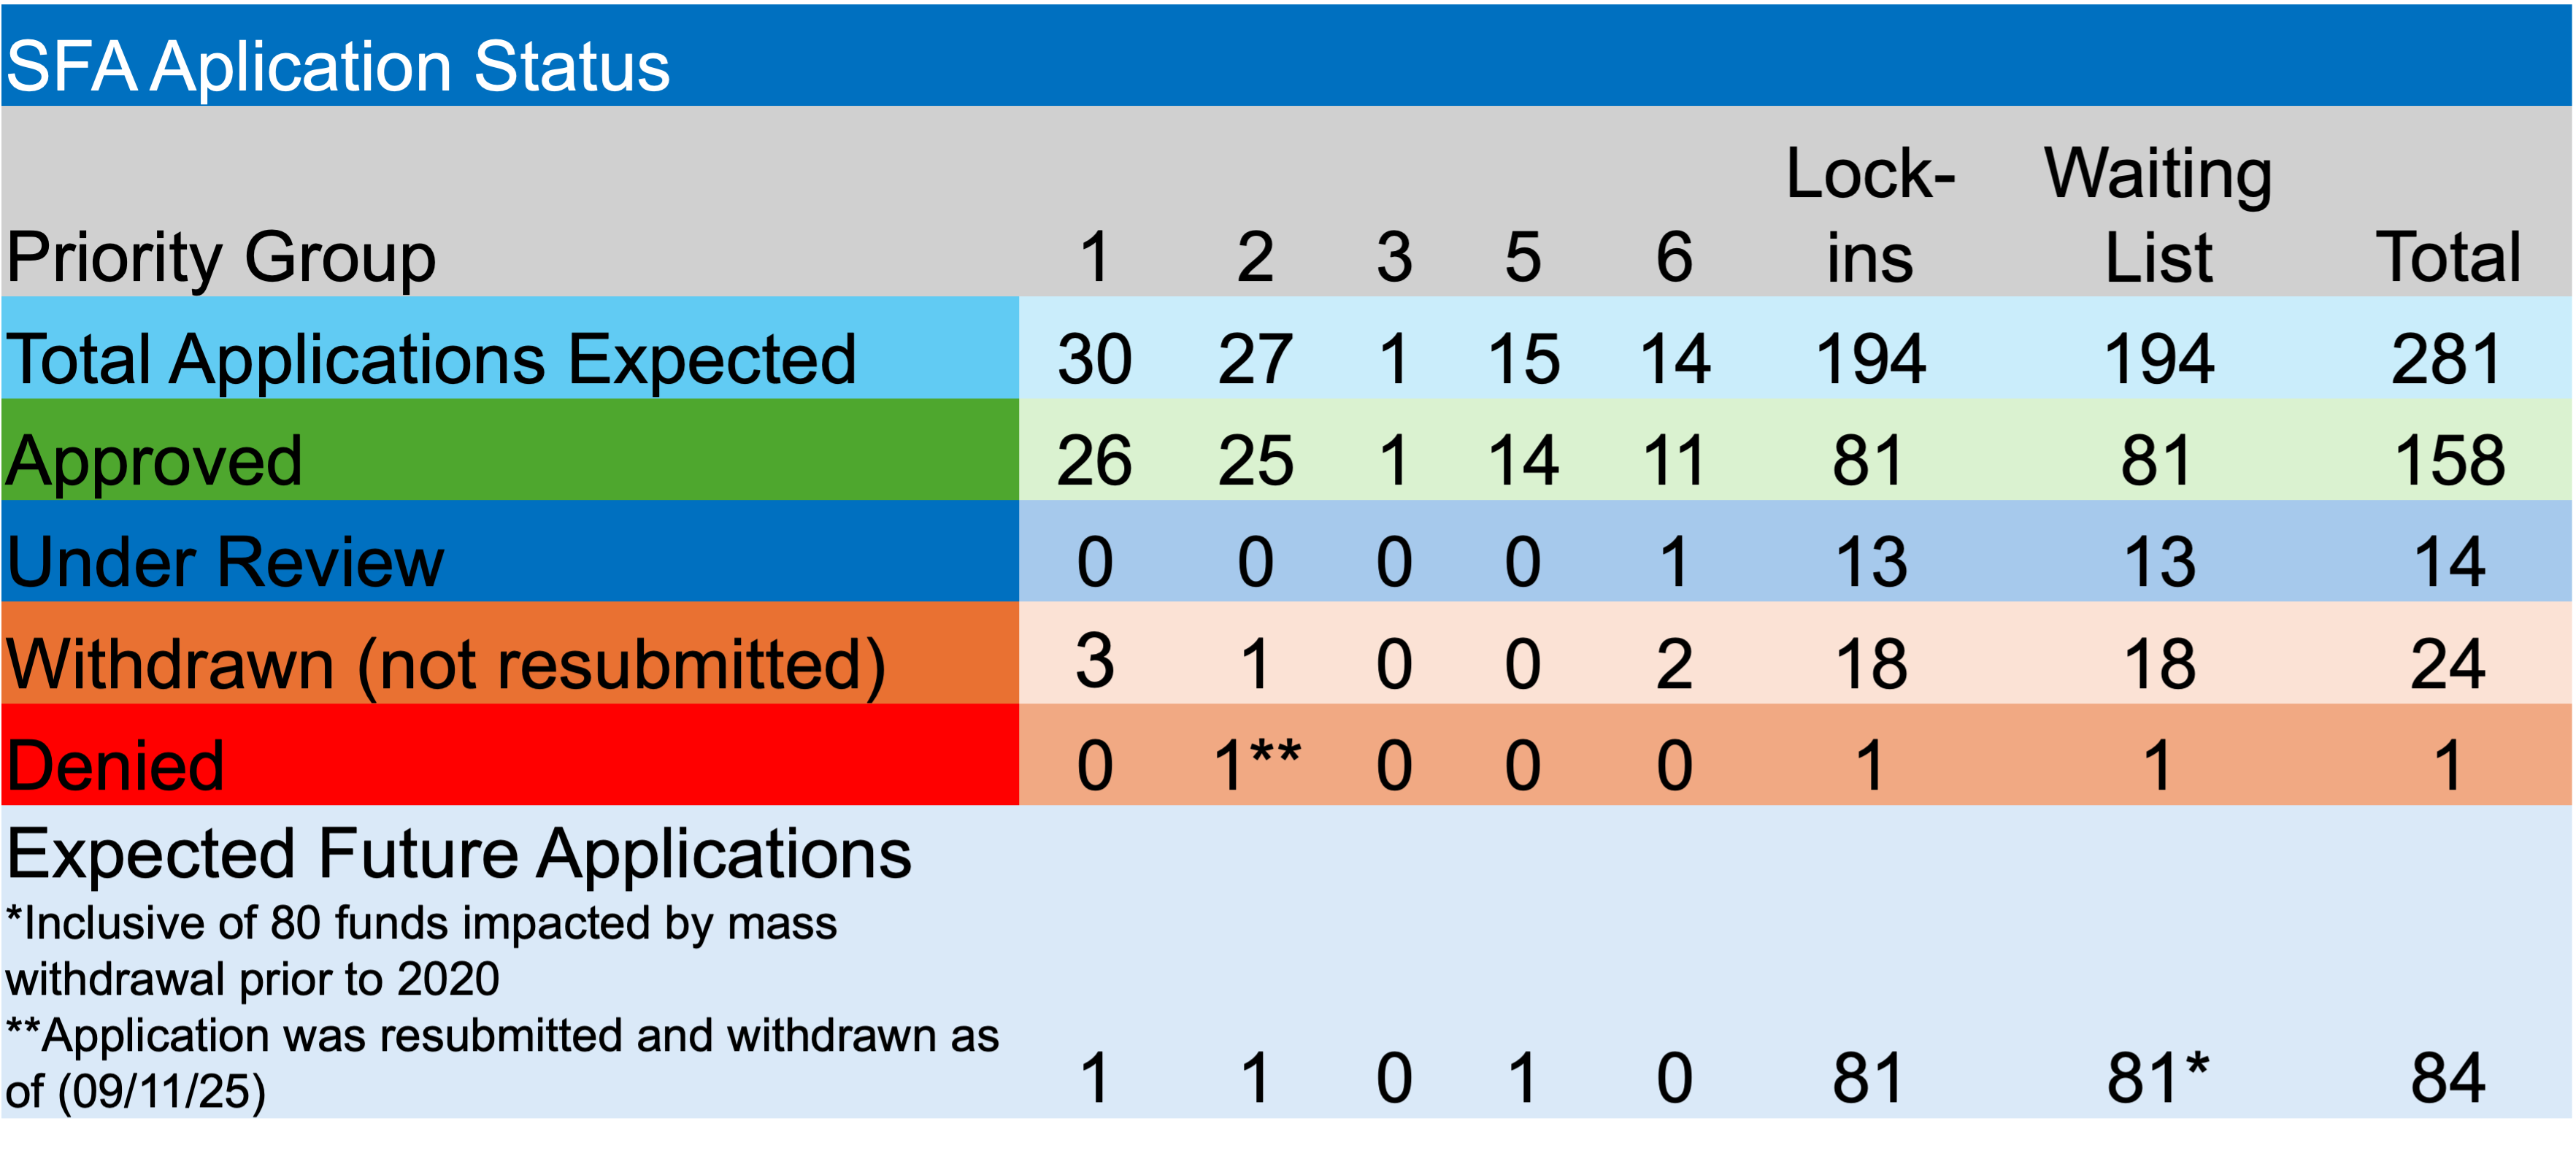
What about ARPA? As regular readers know, the PBGC has worked through a significant majority of non-mass withdrawal applicants. There remains just one fund – Plasterers Local 79 Pension Plan – that hasn’t gotten to submit an initial application form those on the waitlist. There are still a few pension funds from the original Priority Groups that haven’t filed an initial application seeking SFA.

During the prior week, Cumberland, Maryland Teamsters Construction and Miscellaneous Pension Plan received approval of its revised SFA application. They will receive $9.5 million for their 101 plan members. Congrats!

In other news, there is no other news, as there were no new applications submitted, as the PBGC’s eFiling portal remains temporarily closed. Also, there were no applicants denied, no plans were asked to repay a portion of the SFA, and no applications were withdrawn or added to the waitlist.

The treatment of the 80 plans (from potentially 131) currently on the waitlist that fall under the category of plans suffering mass withdrawal prior to 2020 is the last remaining significant issue that the PBGC must still work through.

U.S. Treasury yields have risen sharply since the beginning of the Iran conflict. As challenging as that development is on existing bond funds, the entry point for SFA recipients wanting to use CFM to secure the benefits and expenses is as good as it has been in more than 1-year. As a reminder, higher yields reduce the cost of those future promises.