Will Rising Rates Rattle Equity Markets?

By: Russ Kamp, CEO, Ryan ALM, Inc.

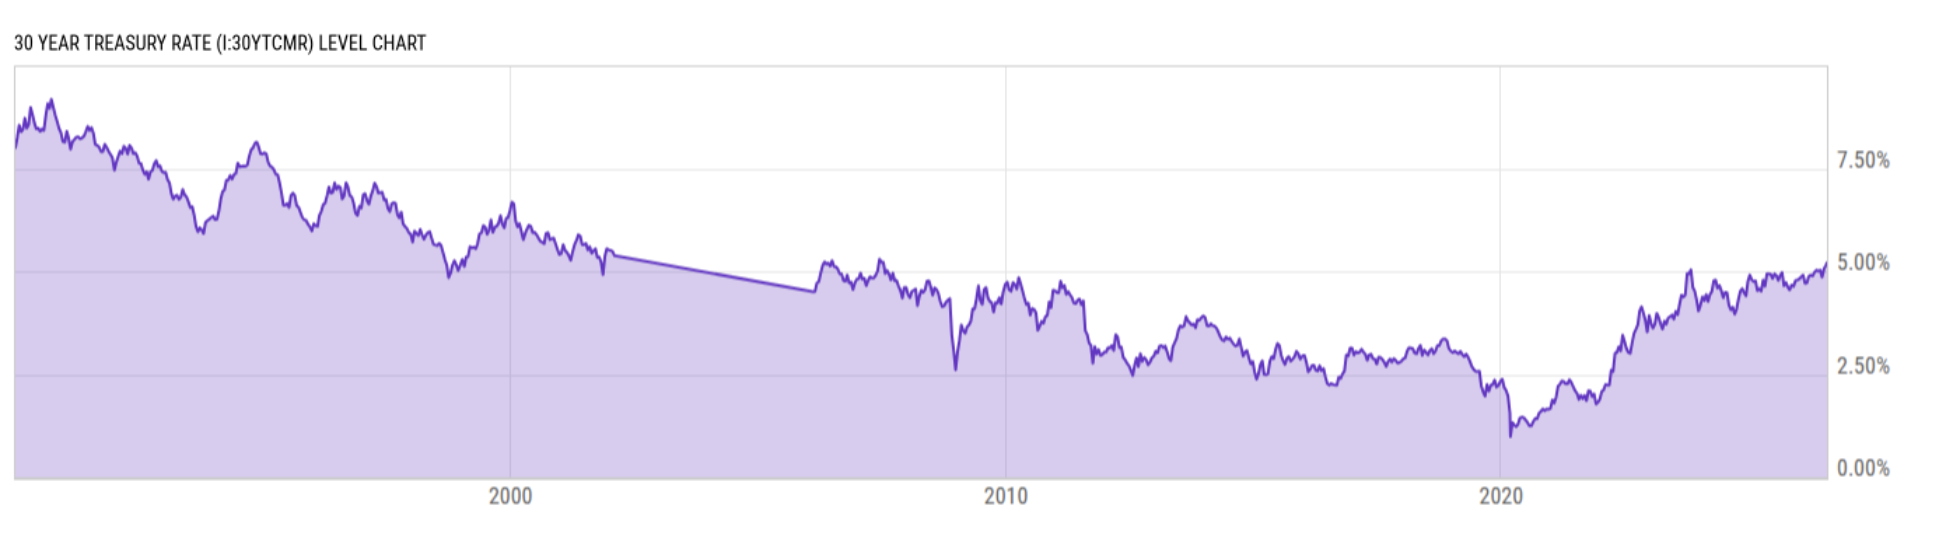
Uncertainty abounds! That uncertainty continues to drive expectations for oil, inflation, and interest rates up and down like a Yoyo. However, recent inflationary trends suggest that U.S. interest rates could continue higher. The U.S. 30-year Treasury bond’s yield is only 4 basis points off it’s cyclical peak since rates began rising aggressively in March 2022.

At Ryan ALM, we recently completed a cash flow matching (CFM) analysis for a public fund in which we were able to defease the pension plan’s liabilities out to 2100. The portfolio that we created to accomplish that objective had a YTM of 6.03%. Barring any defaults (occur at <0.2% in IG space), that is what the plan sponsor should expect to receive over the life of the program. Unlike a broadly diversified pension asset allocation striving to hit an ROA target and all of its standard deviation, there is NO volatility associated with that long-term return and cash flows. There is no potential for a major drawdown impacting future contributions and the plan’s funded status.

Just how has the bond market changed? This morning, our head trader, Steve Devito, shared with us the characteristics for a couple of bonds that had been shown to him. Here is an incredible example of where rates have gone: $2mm par value of ORCL 6.70 maturing in 2056 @ +245 above the comparable Treasury offered at a 7.70% YTM (quality:Baa2 / BBB-). WOW! Here you have an investment-grade corporate bond trading at a yield of 7.7%. The average ROA for a public pension plan is roughly 6.75%. In another example, Steve shared: $2mm GOOGL 6.50 maturing in 2066 @ +124 above the comparable Treasury at a YTM of 6.50% AA (40-year maturity). Google is offering a AA credit 40-year bond at a YTM of 6.5%!

I suspect that there are many other examples of high quality corporate bonds trading at yields greater than 6%. So, I ask: At what level of rates do U.S. corporate bonds become too much competition for U.S. equities and all their uncertainty? As a pension plan sponsor, wouldn’t you prefer to have the certainty of a CFM portfolio securing your pension liabilities from next month chronologically as far into the future as your allocation goes? In the meantime, your residual alpha assets have just been granted a longer investing horizon allowing them to wade through today’s uncertainty without being encumbered with a cash sweep of dividends and capital distributions.

As we regularly write, we are always willing to showcase how CFM can positively impact your plan by providing a free analysis. You will get a better understanding of your plan’s cash flow requirements and an understanding of the potential cost reduction of the future benefit payments. You’ll also have a greater appreciation for the possible significant reduction in asset management fees that is achieved through the use of CFM. Now is the time to act before the markets negatively react to these rising U.S. interest rates.
Is Your Asset Allocation Responsive?

By: Russ Kamp, CEO, Ryan ALM, Inc.

We are happy to share with you Ron Ryan’s latest thoughts related to asset allocation and how it should be responsive and not strategic. We at Ryan ALM, Inc. have witnessed many investing cycles during our decades in the pension industry. We have seen well-funded defined benefit pension plans witness their funded status/ratio deteriorate quickly as markets retrenched. As Ron highlights in his latest thoughtful piece, public pension plans have made terrific strides to improve funding from roughly 71% to a recent high of 88.7% according to Milliman.

Given the improved funding, are U.S.-based pension plans de-risking? Unfortunately, no. They continue to operate with an objective to maximize the return on the assets and not with the more appropriate objective to SECURE the promises made to their members. The former objective continues these plans on a rollercoaster of returns. Regrettably, a return focus only guarantees volatility: volatility of returns leading to volatility of contributions and ultimately the funded status of the plan. It makes little sense.

Adopting an objective that is focused on securing the pension promises creates an element of certainty within the management of pensions not often found, if at all. By securing the promises, one dramatically improves the liquidity needed to meet those monthly obligations. It also creates a longer investing horizon for the assets not used to meet the plan’s liquidity.

We believe that Cash Flow Matching (CFM) is the only strategy that creates the necessary liquidity with certainty, as the asset cash flows of principal and interest are matched to the liability cash flows of benefits and expenses. There is no sweeping of the dividends and capital distributions, which should be reinvested in the products with higher potential returns and NOT used for distributions to beneficiaries.

As your plan’s funded status improves, respond by allocating more of the plan’s assets to CFM. Don’t let your winnings ride. Take risk form the plan’s asset allocation in a responsive way to positive changes in the plan’s funded status. Markets have been producing outsized positive returns, but standard deviations measure both upside and downside possibilities. Is your plan’s sponsor able to withstand a major market correction similar to what we’ve seen previously (2000-’02 and 2007-’09)? Will the likely increase in contributions be crushing?

Who knows what is going to happen with interest rates, inflation, the price of oil, equity markets, etc. Bringing some certainty to pension management should be everyone’s objective. If done correctly, everyone will be able to sleep well at night knowing that your future promises have been secured no matter what transpires in markets that remain out of our control.

Why wait?

By: Russ Kamp, CEO, Ryan ALM, Inc.

Due to great uncertainty brought on by the conflict in the Middle East and the war’s potential impact on the price of oil ($85.63 at 10:01 EST) that could drive inflation higher, U.S. long-dated Treasury yields continue to rise. In fact, the U.S. 30-year Treasury yield has not been this high (5.26%) since July 6, 2007, when the yield was at 5.28%. Where yields go from here is anyone’s guess, but I will share that oil, as represented by WTI, has risen 24.9% since June 30, 2026. Given the exposure that oil or oil-derived inputs have in more than 6,000 products, the significant rise in the recent price could impact inflation for quite some time, even if oil soon began to flow more freely.

We recently saw the average 30-year BBB+ bond trading at 110 bps above the prevailing 30-year Treasury. If that relationship is maintained, pension plans could potentially cover most of their desired return on asset (ROA) annual target (average public pension plan has a 6.75% ROA) through bonds. Should inflation spike once again, there is no telling how high U.S. interest rates could rise. Despite domestic equity’s apparent immunity to market fundamentals and geopolitical risks, there will come a time when higher U.S. yields become too attractive to ignore leading to the potential for rebalancing out of equities into fixed income. That action will likely lead to lower equity prices and falling bond yields.

So, I ask, why wait? Why wait to take risk from your current asset allocation before the markets act? Why not SECURE your benefit promises through cash flow matching (CFM) well into the future and reduce the volatility related to returns, contributions, and funded status? Why not take advantage of very attractive bond yields? As a reminder, core, active fixed income strategies are highly interest rate sensitive. Rising yields negatively impact bond prices, as seen in the performance of the Aggregate Bond Index, which is up only 0.1% annually for the 5-years ending June 30, 2026. However, a CFM strategy, which secures benefits that are future values, eliminates interest rate risk, as future values are not interest rate sensitive.

Public pension plans have done a good job of improving their funded ratios since bottoming after the Great Financial Crisis but remain only one market crash away from repeating this vicious cycle. Get off the performance rollercoaster. Secure your promises chronologically for some period into the future (your plan’s funded status should dictate the allocation). You and your participants will sleep much better knowing that the promises made will be kept.

A “Joe Friday” Moment

By: Russ Kamp, CEO, Ryan ALM, Inc.

Jack Webb, who portrayed Joe Friday in the 1950s crime drama “Dragnet”, was famous for saying in season two “all we want are the facts, ma’am.” The catchphrase eventually morphed into a shorter phrase with the help of comedian, Stan Freberg, who released his parody “St. George and the Dragonet” in which he stated, “just the facts, Ma’am”. That phrase has been carried forward in Dragnet remakes. But, I digress.

Today, I present to you a Joe Friday moment. Here are the facts: Oil prices have risen by 27% since July 6th. U.S. Treasury yields are rising across the yield curve, and the 30-year Treasury yield is within 6 bps of this cycle’s high of 5.2%. The 10-year Treasury yield is currently 4.66% as of 10:24 am on 7/22/26. Investment grade corporate bond spreads have finally started to widen although slowly. According to Morgan Stanley, the “average” yield on a BBB+ corporate is 6.23% or roughly 1.1% higher than the yield on the comparable 30-year Treasury bond. Inflation, which moderated in June, is likely to spike higher given the current direction of activity in the Middle East and its impact on shipping lanes.

These are the facts. They suggest to me, and hopefully you, that the current U.S. interest rate environment is ripe for de-risking activities through cash flow matching (CFM). Why continue to live with the uncertainty surrounding oil, inflation, rates, etc., when you can SECURE your fund’s promises in the near-term?

I wish that I had a crystal ball to help me forecast the future but alas I don’t, and I suspect that you don’t either. Given the lack of clarity related to future events, I suggest that we live in the moment. We have an environment in which the cost of those future promises (benefit payments) can be cut dramatically. An environment that brings an element of certainty to a very uncertain process. An environment in which U.S. interest rates are providing plan sponsors with a significant portion of the annual return on investment target.

We’ve seen this scenario before. At the start of the 2000s, we had pension plans extremely well-funded and contribution expenses well-controlled. That opportunity went unheeded. The result of that inaction proved to be disastrous as we saw DB pension funding get pounded by two major equity market corrections. Are you confident that another major correction isn’t around the corner?

Like Joe Friday, I rely on the facts, which I’ve now presented to you. Ignore them at your peril.

DB Pension Plans: Only One Certainty

By: Russ Kamp, CEO, Ryan ALM, Inc.

As you look at the landscape for defined benefit pension plans, it is readily apparent that there is only one CERTAINTY. Each month your fund must fulfill a promise. Benefit payments (and expenses) can’t wait to be paid. Like clockwork, B&E come due each month whether markets have behaved or suddenly made finding liquidity a challenge. What have you done to make sure that those obligations are met?

Pension plan management is primarily focused on the fund’s assets. Sponsors and their advisors put together an asset allocation framework that is singularly focused on the annual required return on assets (ROA). But those asset allocation frameworks come with a lot of volatility and uncertainty. Many factors contribute to market movements. Each one out of the control of the pension sponsor.

Do you know where stocks will be trading in 1-hour let alone 1-month, 1-year, or 1-decade? How about inflation? Interest rates? What about the Middle East, Ukraine, China, etc.? Why live with such uncertainty?

How comforting would it be to know what a pension fund’s annual contributions will be for the next 10-, 20- or 30+-years? No guessing, no budgeting woes, and no unfortunate spikes in annual contributions for public systems that harm one’s ability to support the social safety net. The process that can create this level of certainty has been used for decades: Cash Flow Matching (CFM).

As previously mentioned, current pension management approaches are return focused, which only guarantees volatility. Volatility in returns, contributions, and funded status! A CFM approach, which is the careful matching of asset cash flows (principal and interest) with the liability cash flows of benefits and expenses, will bring certainty (outside of a rare IG default) to the management of DB pensions. Importantly, liquidity is created and available when needed. There is no forced selling to fulfill those commitments. No scraping of dividend income which is detrimental to the long-term success of the equity program.

Importantly, a CFM program also “buys time” for the residual assets (presumably the alpha assets) to grow unencumbered with the goal to meet future liabilities. A longer investing horizon will dramatically enhance the probability of those assets meeting long-term return expectations.

Given that there is currently only one certainty (monthly obligations) for sponsors of DB pension plans, wouldn’t it be beneficial to create another level of certainty through the SECURING of the monthly promises? Why wait, especially given all the uncertainty facing market participants today? Ryan ALM, Inc. is always willing to provide you with a free analysis of what CFM could do for your fund. We’re ready to help you sleep better at night.

Ryan ALM’s TPA+ Approach

By: Russ Kamp, CEO, Ryan ALM, Inc.

Asset allocation discussions have recently compared traditional pension asset allocation with a “new” approach referred to as the Total Portfolio Approach (TPA). We believe the distinction between traditional asset allocation and the total portfolio allocation is subtle but important. The two approaches begin with different questions.

Traditional asset allocation approaches ask: “How should we invest the assets to achieve the required return objective?”

A TPA approach asks: “How does every asset contribute to funding a pension plans liabilities (benefits)?”

In a traditional asset allocation framework the expectation is that long-term returns will eventual fund the promises. However, a pension plan doesn’t exist to outperform an index/benchmark. It exists to pay the promised benefits!

In the TPA approach, a pension fund will have a broadly diversified array of investments, but each investment has a specific purpose relative to the pension plan’s liabilities. There are no investment sleeves, but a single portfolio with the goal to fund the pension’s liabilities.

We, at Ryan ALM, Inc. believe that our approach, implemented over decades, goes one step beyond Total Portfolio Management.

Whereas a TPA asks: “What allocation best maximizes the performance of the entire portfolio?”

Ryan ALM asks: “What investment strategy best minimizes the cost and risk of paying future pension benefits?”

TPA shifts the focus from individual asset classes to the overall portfolio. Ryan ALM shifts the focus again—from the portfolio itself to the pension liabilities. Assets need to know what they are funding… net liabilities (projected benefits – projected contributions). Since the actuary does not calculate net liabilities, this becomes the first step and calculation of the Ryan ALM process. Our philosophy is arguably closer to Total Pension Management than Total Portfolio Management.

Ryan ALM’s liability-based investment philosophy shares important characteristics with TPA while also differing in a fundamental way.

Traditional Asset AllocationTotal Portfolio ApproachRyan ALM Liability-Based Investing
Optimizes asset-class weightsOptimizes the total portfolioOptimizes the funded status and liability outcomes
Benchmark relativeGoal relativeLiability relative
Focus on returnsFocus on total risk-adjusted returnsFocus on securing pension promises
Asset classes drive decisionsPortfolio drives decisionsLiabilities drive decisions

The Pension objective isn’t returns—it’s securing pension promises! Ryan ALM’s pension management is distinguished from both traditional asset allocators and TPA by highlighting and managing to the pension plan’s liabilities, and then paying those liabilities when required through Cash Flow Matching. No games and no uncertainty!

Complexity Doesn’t Make it Good or Appropriate

By: Russ Kamp, CEO, Ryan ALM, Inc.

We have a serious retirement problem in the U.S. Defined benefit plans have mostly been replaced in the private sector, and rising contribution levels are making public pension offerings problematic for the sponsoring entities. These issues are compounded by the fact that many defined benefit plans have migrated significant assets to opaque, complex, and costly alternative investments. In the process, creating liquidity to meet ongoing benefits and expenses has become more challenging.

Managing a DB pension plan isn’t complicated, yet we continue to make it so. I read an Institutional Investor article with interest, and some alarm, that a public pension system operating with negative cash flow (contributions < benefits and expenses) has decided that the best way to address the liquidity shortfall is to move assets into “”a lot more esoteric lending strategies” like asset-based finance and royalty-based lending in sectors such as entertainment, healthcare, and aircraft engine leasing.” The CIO for this fund continued, “we’re going into a lot of illiquid structures, so we structure the portfolio to make sure we have enough liquidity to meet our benefit payments at all times,” Really????

Going into illiquid structures to ensure adequate liquidity seems oxymoronic. We’ve seen what has transpired in both private equity and private debt regarding distributions and the lack thereof. Again, our industry often brings complexity to a problem when there are far simpler ways to tackle an issue. For decades, Cash Flow Matching (CFM) has carefully matched asset cash flows of bond interest and principal with the liability cash flows of benefits and expenses (B&E) chronologically. There is no hoping that the liquidity will be available when needed.

U.S. rates are currently at levels providing plan sponsors with the ability to SECURE future B&E at low cost and with certainty barring any defaults in IG bonds (<0.2%/year for the last 40-years). Why engage in expensive, opaque “solutions” when a CFM strategy can be adopted for pennies on the $. CFM is a-sleep-well-at-night strategy, which will be comforting to not only the plan sponsor but the plan’s participants. Please stop thinking that a solution needs to be complex to be good. Some of the very best approaches are transparent, straight-forward, and inexpensive: like CFM!

The Ryan ALM, Inc. Blog

By: Russ Kamp, CEO, Ryan ALM, Inc.

Are you a recent subscriber (thank you) to the Ryan ALM, Inc. blog? Here’s a little history. I began writing this blog in 2013. I’ll never forget my elementary school friend, Tony, who helped me set up the blog, saying that I shouldn’t start one if I wasn’t going to be consistent in producing content. Well, 13-years later and there are now 1,800+ mostly pension-related posts and more than 600k words. When I joined Ryan ALM, Inc. in the summer of 2019, I was extremely grateful to Ron Ryan for supporting this effort and that support continues to this day, while also being a contributor of important content.

As a new subscriber, what should you expect to read among the plethora of posts? I believe the dominant themes are:

  1. DB Pensions exist to secure promised benefits, not maximize returns.
  2. Pension Liabilities should drive investment decisions and not the ROA.
  3. Funded status matters much more than asset returns.
  4. Cash Flow Matching (CFM) is the most prudent way to secure benefits.
  5. Custom Liability Indexes (CLI) are essential for measuring pension success – good governance.
  6. Reducing uncertainty through fully funding benefits is the true definition of pension risk management.
  7. Defined benefit plans should be protected and preserved.

As a reminder, Ryan ALM, Inc. is an independent pension risk management and SEC registered investment firm that helps defined benefit plans improve funded status, reduce liability risk, enhance liquidity, and secure retirement promises through custom liability measurement, cash flow matching, actuarially informed investment strategies, and ongoing monitoring.

Don’t hesitate to reach out to us with your questions and/or comments. They are always welcome on this blog, which can be found here.

Source Ryan ALM, Inc.

By: Russ Kamp, CEO, Ryan ALM, Inc.

At Ryan ALM, Inc., we pride ourselves on being a resource for our clients beyond providing our three products – Cash Flow Matching (CFM), Custom Liability Index (CLI), and our ASC 715 Discount Rates. As regular readers of this blog will recall, we are always highlighting our willingness to provide a free analysis on how any of our products can be used to support your pension fund or E&F, especially if the goal is to secure the promised monthly benefits or grant payments.

These insights have been put to practical use three times in the last week by our clients. In the first case, we were asked to price a possible extension of an existing CFM portfolio by 6-months and 12-months using only investment grade bonds in one case while including high yield in the second scenario.

In the second example, we manage a CFM portfolio for a plan where we have defeased 100% of the net liabilities out to 2056. This plan is scheduled to make contributions until 2048. We were asked to evaluate the impact on the CFM portfolio (and the pension fund) using two new contribution rates equal to 75% and 50% of the current annual payment.

In the third example, we currently manage a significant portion of an E&F’s total fund. They inquired as to what the impact would be on the current CFM portfolio if they expedited grant payments during the next four years. We currently cover future grant payments out to 2036.

In each of these cases, we produced an analysis that will help them come to a decision that is in the best interest of the fund. We encourage our clients, and those that would like to be, to use our services to think through critical issues, such as ongoing liquidity needs, which has become a challenge for many plans/funds as alternative assets have become a bigger share of the asset allocation. Please don’t hesitate to SOURCE Ryan. We suspect that you’ll be quite pleased by what our services can do for you, your fund, and most importantly, your beneficiaries. Try us. I’m certain that you’ll like us!

The Ryan ALM mission is to solve liability driven problems through low-cost, low-risk solutions.

Pension Problem: Gross versus Net Liabilities

By: Ronald J. Ryan, CFA, Chairman, Ryan ALM, Inc.

Most pension plans are focused on gross liabilities as expressed by the funded ratio (total assets / total liabilities) and funded status (total assets – total liabilities). But the truth is plan assets are to fund NET liabilities after contributions. Contributions can be quite large especially for public pension funds. Pension assets need to know what they are funding… answer = NET liabilities. Unfortunately, actuaries do not calculate NET liabilities, nor do they include contributions as an asset to calculate the funded ratio / status. These oversights have an impact on asset allocation, especially if it is focused on the true economic funded status of solvency. The Ryan team created the first Custom Liability Index (CLI) in 1991 that has become a core product of Ryan ALM. Our CLI will calculate NET liabilities as a term structure, so assets and the plan sponsor know the liquidity needed and when to fund NET liabilities. 

GASB accounting requires a test of solvency (asset exhaustion test or AET) for public funds (which should be a requirement for all types of pensions) that includes contributions as a future asset to help fund the future liability cash flow schedule. Assets are grown at the return on asset assumption (ROA) to see if they can fully fund projected benefits – projected contributions (net liabilities). At the point that assets are exhausted, GASB requires a bifurcated discount rate using AA 20-year municipal rates. Ryan ALM modifies the GASB AET to calculate the ROA needed to fully fund net liabilities. We find that our calculated ROA is usually much lower than the ROA assumption currently being used. Our calculated ROA should be the hurdle rate for asset allocation instead of the common practice of choosing an ROA based on an asset only forecast of returns by asset classes. Our modified AET should be the first step in asset allocation after the CLI is built.

Bonds are the only asset class with the certainty of cash flows. That is why bonds have always been used to defease and immunize liabilities. Our Liability Beta Portfolio™ (LBP) is a cost optimization model that will fully fund NET liabilities at the lowest cost to the plan sponsor. We strongly believe that the bond allocation should be used to fully fund NET liabilities chronologically. In the process, an extended investment horizon is created buying time for the Alpha assets to grow unencumbered. We have found that converting the plan’s core fixed income allocation to a cash flow matching portfolio will normally cover the plan’s next 10+-years of benefit payments. Instead, some pension plans use a “Cash Sweep” to fund current liabilities which significantly damages the total return produced by those growth assets. Let bonds fund NET liabilities with certainty through our LBP… and sleep well at night.        

“Where is the knowledge we have lost in information?” T.S. Eliot