The Proof’s in the Pudding!

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

Not sure why I used the title that I did, but I recently had pudding (vanilla) over the holiday weekend, so maybe that inspired me, and boy, was it good! That said, we, at Ryan ALM, Inc., are frequently challenged about the benefits of Cash Flow Matching (CFM) versus other LDI strategies, most notably duration matching. There seems to be singular focus on interest rate risk without any consideration for the need to create the necessary liquidity to meet monthly benefit payments. Given that objective, it isn’t surprising that duration matching strategies have been the dominant investment strategy for LDI mandates. But does that really make sense?

Are duration matching strategies that use an average duration or several key rate durations along the Treasury curve truly the best option for hedging interest rate risk? There are also consulting firms that espouse the use of several different fixed income managers with different duration objectives such as short-term, intermediate, and long-term duration mandates. Again, does this approach make sense? Will these strategies truly hedge a pension plan’s interest rate sensitivity? Remember, duration is a measure of the sensitivity of a bond’s price to changes in interest rates. Thus, the duration of a bond is constantly changing.

We, at Ryan ALM, Inc., believe that CFM provides the more precise interest rate hedge and duration matching, while also generating the liquidity necessary to meet ongoing benefits (and expenses (B&E)) when needed. How? In a CFM assignment, every month of the mandate is duration matched (term structure matched). If we are asked to manage the next 10-years of liabilities, we will match 120 durations, and not just an “average” or a few key rates. In the example below, we’ve been asked to fund and match the next 23+ years. In this case, we are funding 280 months of B&E chronologically from 8/1/24 to 12/31/47. As you can see, the modified duration of our portfolio is 6.02 years vs. 6.08 years for liabilities (priced at ASC 715 discount rates). This nearly precise match will remain intact as US interest rates move either up or down throughout the assignment.
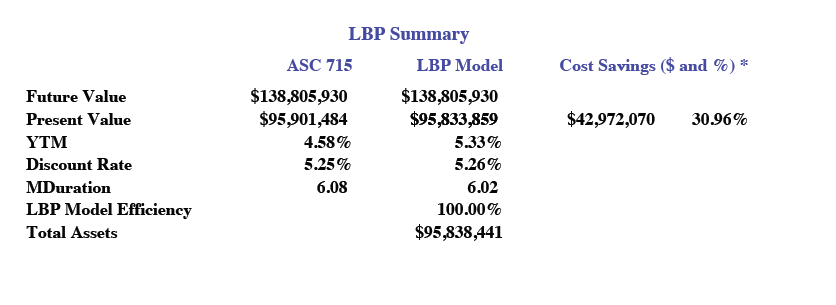
Furthermore, CFM is providing monthly cash flows, so the pension plan’s liquidity profile is dramatically improved as it eliminates the need to do a cash sweep of interest, dividends, and capital distributions or worse, the liquidation of assets from a manager, the timing of which might not be beneficial. Please also note that the cost savings (difference between FV and PV) of nearly 31% is realized on the day that the portfolio is constructed. Lastly, the securing of benefits for an extended time dramatically improves the odds of success as the alpha/growth assets now have the benefit of an extended investing horizon. Give a manager 10+ years and they are likely to see a substantial jump in the probability of meeting their objectives.

In this US interest rate environment, where CFM portfolios are producing 5+% YTMs with little risk given that they are matched against the pension plan’s liabilities, why would you continue to use an aggressive asset allocation framework with all of the associated volatility, uncertainty, and lack of liquidity? The primary objective in managing a pension plan is to SECURE the promised benefits at a reasonable cost and with prudent risk. It is not an arms race designed on producing the highest return, which places most pension plans on the asset allocation rollercoaster of returns.

Good Ideas Are Often Overwhelmed!

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

We have a tendency in our industry to overwhelm good ideas with much too much money. Asset flows can be evil as they drive valuations up as too much money pursues to few good ideas. The “winner” in the bidding competition frequently (eventually) becomes the loser in the long run. I recently wrote about this phenomenon as it related to private credit. Well, we have a similar, if not more egregious example as it pertains to private equity. With more than $3.2 trillion tied up in aging, closely held companies at the end of 2023, according to Preqin data. 

I recently read a refreshingly honest post on LinkedIn.com about the current state of private equity. The comments referred to a discussion given by a “leading” voice within the industry who mentioned that the “types of PE returns it (our industry) enjoyed for many years, you know, up to 2022, you’re not going to see that until the pig moves through the python. And that is just the reality of where we are.” That is quite the image. It speaks to my point about too much money chasing too few good ideas. Pension America has pursued a return objective in lieu of one that stresses the securing of the pension promise. Striving for return has forced most participants to load up on gimmicky alternatives, including real estate, private credit, private equity and worst of all, hedge funds.

For the early adopters, returns above those produced by the public markets were achievable, but again, once someone has a decent idea we tend to jump on that bandwagon until the horse can’t pull the cart any longer. What happens next is usually not pretty. This leading voice also mentioned that “fewer realizations and lower returns” were on the horizon until the proverbial pig was digested. Unfortunately, PE firms are holding onto these aging companies and they will need to be refinanced at much higher interest rates which will further reduce expected returns.

In other news, Heather Gillers, WSJ, reported that the honeymoon may be over between pension America and private equity managers. The promise of high returns may not be realized after all. According to Ms. Gillers, payouts from these expensive offerings have all but dried up. As a result, many pension funds are unloading their investments at significant discounts through secondary markets. According to this article, large public pension systems have migrated roughly 14% of the plan’s AUM into PE. What once looked like an investment that could produce a premium return is struggling to match returns of the S&P 500.

Worse, about 50% of the private equity investors have assets tied up in “Zombie funds”, which hadn’t paid out on the expected timeframe. Needing liquidity (should have invested in a cash flow matching strategy), these pension funds are getting an average of about 85% of the value of assets that were assigned just three to six months prior. According to Jefferies Financial Group about $60 billion was transacted in secondhand sales by PE investors last year.

Despite the lack of liquidity and the idea that too much money has been chasing too few good ideas, the “honest’ assessment by our industry “leading voice” stopped at their doorstep. You see, his firm believes that by 2026 (beginning or end of year???) their alternative assets under management will rocket from $651 billion to $1 trillion. Wow! Now how will that pig pass through the python? Are we to believe that growth of that magnitude will not negatively impact that firm or our industry? I guess that the news to date hasn’t been sufficiently ugly to stop this rampage into PE. I’ve seen this movie before. Spoiler alert – the train barrels forward until it goes over a cliff where the tracks used to be. I’d suggest getting off the next stop.

Money Managers Recaptured 1/2 the 2022 losses – Should We Be Pleased?

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

P&I has produced an article highlighting the fact that money managers recaptured nearly half of the institutional assets lost (-$9 trillion) in 2022’s market correction. They mention that this was accomplished despite “lingering economic and political uncertainties that kept a lot of money sidelined, including a record $6 trillion parked in money market funds alone.”

According to Pensions & Investments’ 2023 survey of the largest money managers, institutional assets for 411 managers around the globe rose 9.7%, or $4.89 trillion, to $55.23 trillion as of Dec. 31, 2023 for a recovery rate of 52.5%. This recapture of assets was primarily driven by equities, both US (+26%) and global X US (+18%), while bonds were up 5.6% domestically and abroad.

Obviously, it was great to see the “rally” despite wide-spread uncertainty related to the economy, inflation, interest rates, and the labor market. Issues that are still impacting perceptions today. But the real question one should ask has to do with the cyclical nature of markets and what plan sponsors and their advisors can do to mitigate the peaks and valleys. As I reported earlier this week, since 2000, public pension plans have seen a tripling (or more) in contribution expenses as a % of pay, while the funded status of Piscataqua research’s universe of 127 state and local plans has fallen by 25%.

Isn’t it time to get off the asset allocation rollercoaster? The nearly singular focus on return (ROA) by pension plan sponsors has placed pension funding on a ride that does little to guarantee success, but has certainly exacerbated volatility. In the process, contributions into these critically important retirement systems have skyrocketed. Let’s stop thinking that the only way to fund pensions is through outsized market returns. Today’s interest rate environment is providing plan sponsors with a wonderful opportunity to SECURE a portion of their future promises by carefully constructing a defeased bond portfolio that matches and funds asset cash flows of principal and interest with liability cash flows of benefits and expenses.

By doing so, you eliminate the impact of drawdowns, as the assets and liabilities will now move in tandem. How refreshing! Because you are defeasing a future benefit, you are also eliminating interest rate risk, as future values are not interest rate sensitive. Furthermore, you have now created a liquidity profile that is enhanced, as the bond portfolio now pays all of the benefits and expenses chronologically as far into the future as the allocation to the cash flow matching program lasts. Lastly, the growth or alpha assets can now grow unencumbered, as they are no longer a source of funding. The need for a cash sweep has been replaced by cash flow matching with bonds.

Let’s stop having to celebrate recovery rates of roughly 50%, when we can institute investment programs that eliminate these massive and harmful drawdowns. They aren’t helpful to the sustainability of DB pension plans, which we so desperately need if we are to provide a dignified retirement to the American worker. Let’s get back to the fundamentals, as the true objective of a pension is to fund benefits in a cost-efficient manner with prudent risk. It isn’t a performance arms race!

The Status Quo Isn’t Working

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

Anyone who has read just a handful of the >1,400 blog posts that I’ve produced knows that I am a huge fan of defined benefit (DB) plans. That I’ve come to loathe the fact that DB plans were/are viewed as dinosaurs, and as a result have been mostly replaced by ineffective defined contribution plans. As a result, the American worker is less well-off given the greater uncertainty of their funding outcome. A dignified retirement is getting further out of reach for a majority of today’s workers.

That said, just because I desire to see DB plans maintained as the primary retirement vehicle, doesn’t mean that I appreciate how many of them have been managed. The pension plan asset allocations remain focused on the wrong objective, which continues to be the ROA and NOT the plan’s liabilities. It is this mismatch in the primary objective that has exacerbated the volatility of the funded ratio/status and contribution expenses. As I’ve stated many times, it is time to get off the asset allocation rollercoaster. We need to bring an element of certainty to the investment structure despite the fact that outcomes within the capital markets are highly uncertain.

How bad have things been? According to a recently produced analysis by Piscataqua Research, Inc., which regularly reviews the performance of both assets and liabilities for 127 state and local retirement systems, since 2000 contributions as a % of pay have tripled, while funded status has declined by more than 25%. Again, I’m not here to bash public funds. On the contrary, I am here to offer a potential solution to the volatility exhibited. I wrote a piece many years (1/17) ago titled, “Perpetual Doesn’t Mean Sustainable” in which I discussed the need to bring stability to these critically important retirement plans because at some point there might just be a revolt from the taxpayers that are lacking defined benefit participation themselves. We can’t afford to have tens of millions of American public fund workers added to the federal social safety net God forbid their retirement plans are terminated and benefits frozen prematurely.

There is only one asset class – bonds – in which the future performance is known on the day that the bond is acquired. You can’t tell me what Amazon or Tesla will be worth in 10 years or the value of a building or private equity portfolio, but I can tell you how much interest and principal you will have earned on the day that the bond matures, whether that be 3-, 5-, 10- or 30-years from now. That information is incredibly valuable and can be used to match and SECURE the pension plan’s liabilities. That portion of the plan’s assets will now provide stability and certainty reducing the ups and downs exhibited through normal market behavior. Why continue to embrace an asset allocation that has NO certainty? An asset allocation that can create the explosion in contribution expenses that we’ve witnessed.

DB plans need to be protected and preserved! Ryan ALM’s focus is solely on achieving that lofty goal. It should be your goal, too. Let us help you get off the asset allocation rollercoaster before markets reach their peak and we once again ride those market down creating a funding deficit that will take years and major contributions to overcome.

Does This Look Like Success?

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

The following was a headline for a MarketWatch.com article, “The 401(k)’s success has been overlooked and will help even more Americans”, which I saw on a LinkedIn.com post earlier today. Sure, some American workers have benefited from their ability to fund a DC account, but the vast majority of Americans are struggling.

Does This look like success?

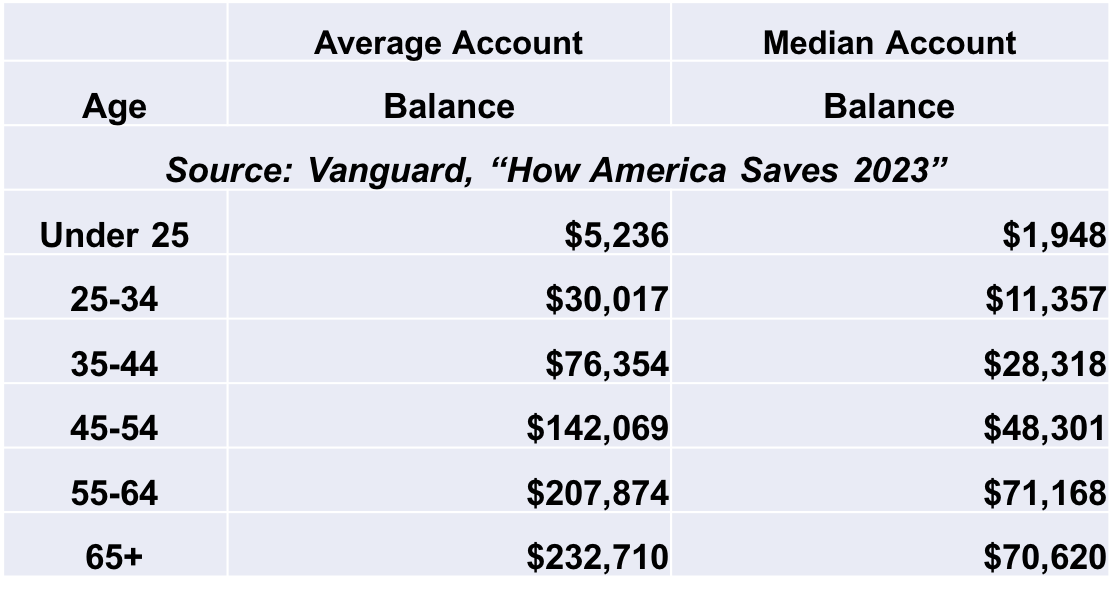
Perhaps the level of savings would be okay if DC plans were actually supplemental retirement vehicles, but since they have morphed into the primary retirement program for most workers, this is a disaster. I’m tired of the fact that we only ever see “average” balances reported. Of course, a few well-funded balances will drive the average up. Let’s focus on the MEDIAN account balances. Does a $70,620 account balance for a 65+ year-old participant look like a successful outcome? How much would that balance provide on a monthly basis for a roughly 20-year retirement?

If I were fortunate to have a defined benefit plan that provided $2,000/month (which isn’t a lot) for 20-years, I would receive $480K in retirement which is 6.8Xs what the 65+ year-old with the median account balance has today. It is a far cry when compared to the view that $1.4 million is the balance needed to have a dignified retirement today. It is silly to believe that the average American has the disposable income, investment acumen, and predictive ability to gauge how long they will live in order to allocate this meager balance to ensure that the recipient doesn’t outlive their savings.

The investment industry can celebrate all they want as it relates to the total accumulated wealth in defined contribution plans, but for the “median” American, it just isn’t close to being enough. Defined benefit plans should be the backbone of our retirement system, while DC plans occupy the supplemental role for which they were designed. As someone in that LinkedIn.com post stated, “the numbers don’t lie”. I would certainly agree, but that doesn’t mean that the #s are revealing success!

Kinda Silly Question

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

If you ask the average person the following questions, I suspect that most people would answer in the affirmative.

Are you handsome?

Are you intelligent?

Are you honest?

So, I found it somewhat humorous when I saw the headline from a recent conference that said, “Private Credit managers say their is more room for growth”. Are you surprised? How many investment management organizations turn down new business when it presents itself? Does it really matter that private debt has seen something like 10X asset growth in the last couple of decades? Perhaps these managers have such a unique niche that they honestly believe that their product can manage through any challenge, especially one as “trivial” as natural capacity. How many times have you heard the following: “Our maximum capacity that we previously cited was just a target amount. Now that we actually have assets under management, it is clearer that we have much more capacity than initially anticipated.” Seems convenient, doesn’t it?

I can recall a few difficult conversations with both sales and senior management when I was leading an investment team at a previous shop. Our research and portfolio management teams did an outstanding job of determining the appropriate capacity for each strategy, and we had 50+ optimizations that each represented a strategy/product. We were particularly cognizant of the capacity associated with our market neutral product, which was roughly $3 billion in AUM. We had to be most careful with shorting stocks given the borrowing rates being charged by our prime brokers. The size of trades were always a concern. Yet, it really didn’t matter to outside parties that just wanted to see assets flow into our products. It didn’t matter whether or not we would be able to generate the return/risk characteristics as previously defined by our investment team.

These awkward conversations occur all too frequently, especially for investment companies that are public and have quarterly earnings expectations that must be met. I’ve never understood how the investment management industry can claim to be “long-term” investors yet be driven by quarter-to-quarter earnings announcements that impact the investment teams when layoffs are announced. Has our industry just morphed into a number of large sales organizations? Do we have “investment” firms focused on generating appropriate return and risk characteristics? Do these firms truly understand the capacity based on trading metrics?

I don’t work for a company that participates in the Private Credit arena. I couldn’t tell you whether or not there remains adequate capacity to enable managers in that space to generate decent return and risk characteristics. But asking managers in that space whether or not they can take on more assets and generate more fees is kinda silly. I hope that the asset consulting community has the tools to evaluate capacity for not only this asset class, but any other being considered for use in a DB pension. Given that most “active” managers have failed over time to generate a return in excess of their respective benchmark, I would hazard a guess that the natural capacity for their strategy has been eclipsed. These excess assets lead to ever increasing trading costs of market impact and time delays (not commissions). Couple those costs with the fees that active managers charge and you create a hurdle that is difficult to overcome.

He Said What?

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

I’d like to thank Bill Gross for his honest assessment that he just provided on the likely failure of “Total Return” bond products going forward. Here are his thoughts that were summarized in a Bloomberg Business email:

Bill Gross says his “total return” strategy—the one that revolutionized the bond market— “is dead”! Instead of just picking up steady interest payments like his peers did at the time, the co-founder of Pacific Investment Management created the firm’s Total Return Fund in 1987 to take active positions in duration, credit risk and volatility. The idea is that, more than just clipping coupons, bond investors can also benefit from capital appreciation as bond prices rise and yields fall. But in an outlook published Thursday, Gross noted what’s different now is that yields are much lower than when he first coined the concept, leaving investors with less room for price appreciation. 

We’ve been stressing this point for a long time now. Bonds should be used for the certainty of cash flows that they produce of interest and principal. Those cash flows are known and can be modeled with certainty (barring no defaults) to meet the liability cash flows of a pension plan (benefits) or foundation (grants). As Gross rightly points out, given the current level of US interest rates and inflation, just how much appreciation can be achieved, if an investor is on the correct side of a duration bet.

Capital market participants benefited tremendously during the nearly four decades decline in rates from 1981 to 2021. That move down in rates was certainly great for “total return” bond programs, but it also acted as rocket fuel for risk assets. What most market participants have either forgotten or don’t know is the fact that US interest rates trended higher for 28 years prior to the peak achieved in 1981. They are used to the Fed stepping into the fray every time there was a wiggle or wobble in the markets. Well, those days might be behind us.

Yes, US employment came in light this morning with 175k jobs being created in April when the forecast was for 240k, but that is one data point. We certainly witnessed an aggressive move down in rates during 2023’s fourth quarter only to see most of that move reversed to start 2024. Was your bond program able to get both directions correct or did your portfolio get whipsawed? Wouldn’t it be more comforting to know that you can install a cash flow matching portfolio that will SECURE the promises that have been made to the plan participants without having to guess the direction of rates? Even if one were to guess correctly, just how far will rates fall given that inflation remains sticky? Are you likely to see negative real yields?

The US economy remains robust. Fiscal policy remains easy with excessive Government spending and in direct competition with monetary policy. The labor market continues to be strong, as is wage growth. The stock market’s performance continues to support the economy. Given these realities, why should US rates plummet, which is what it would take to create an investing horizon that would be supportive of “total return” fixed income products.

CFM: Buy Time and Reduce Risk

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

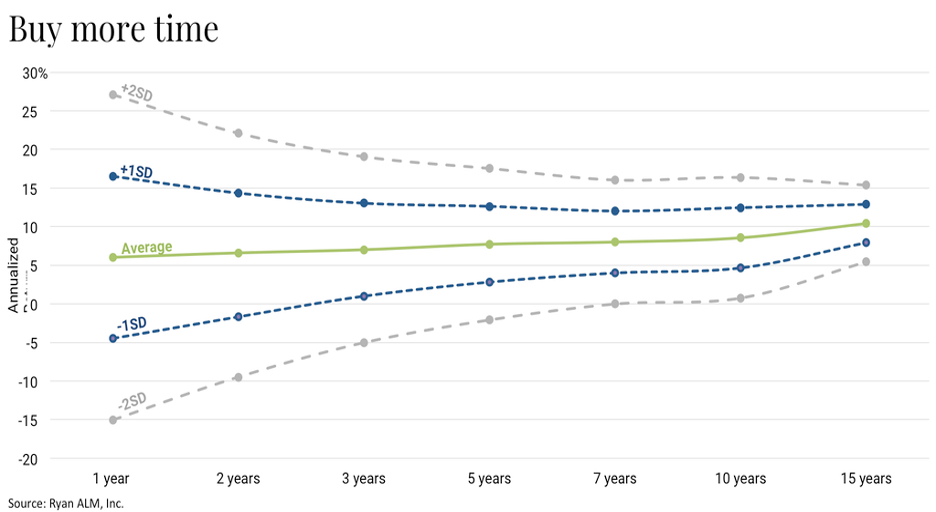
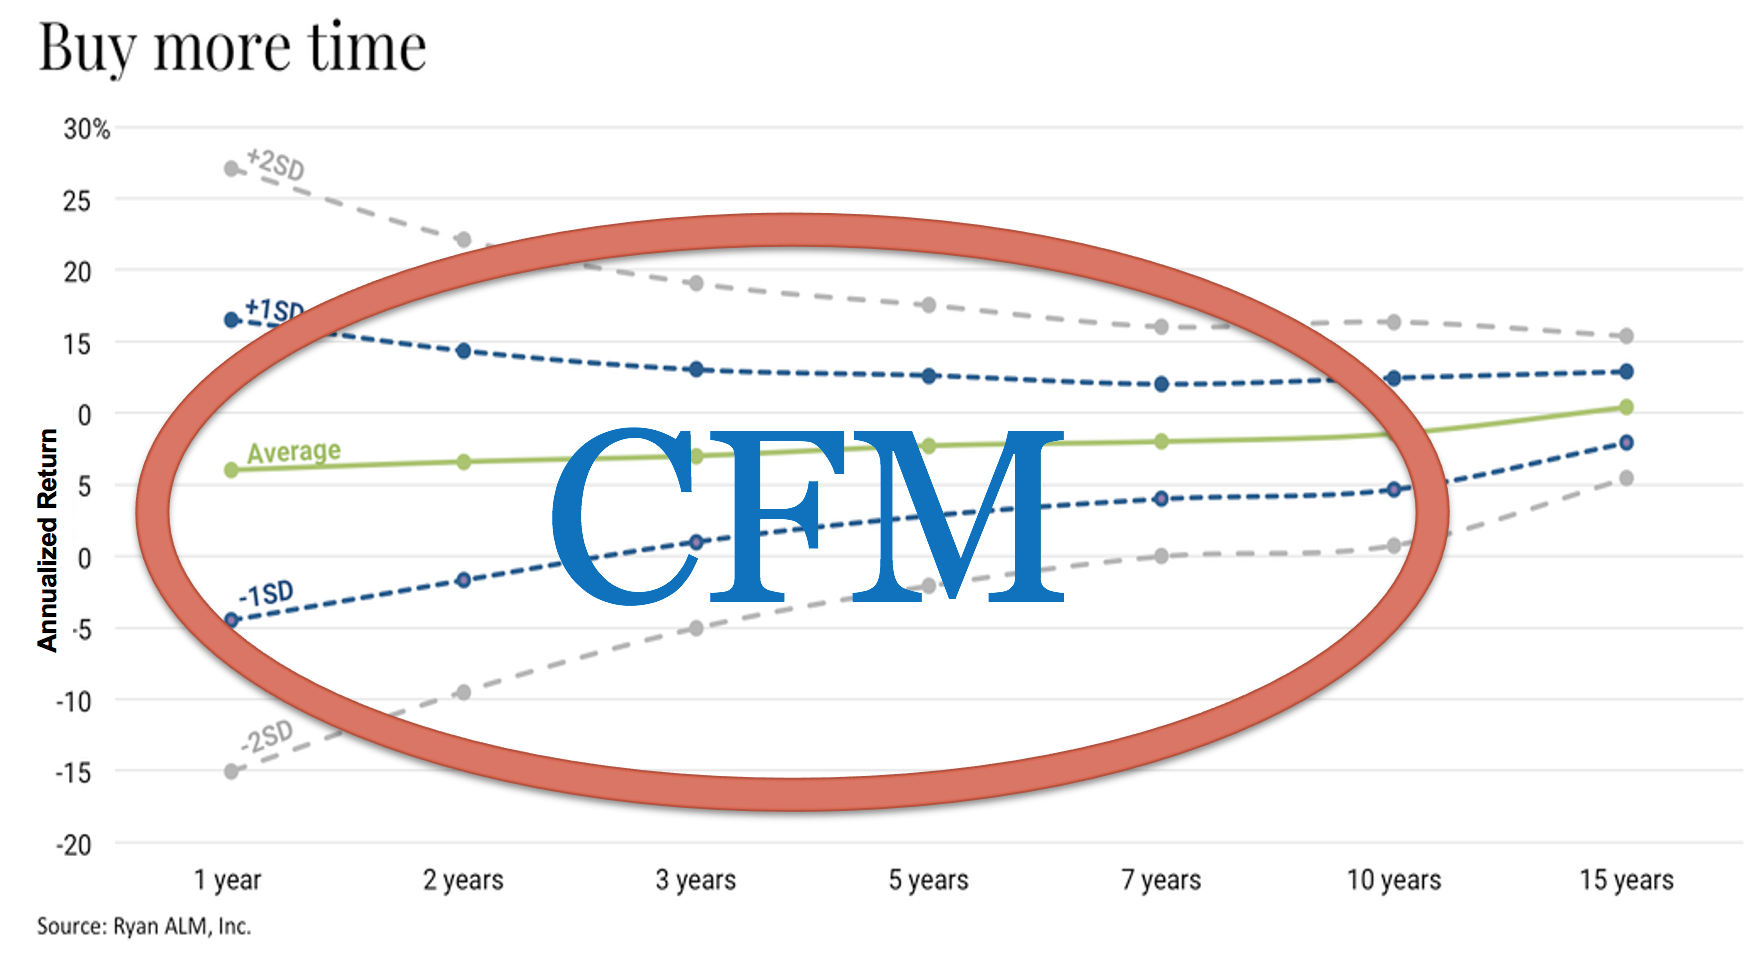
A traditional DB plan’s asset allocation comes with a lot of annual volatility (see the graph below). That volatility gets reduced as one extends the investing horizon, but it is still quite uncertain until you extend sufficiently, such as 10 or more years. However, as plan sponsors and investment managers, we have been living in a quarter-to-quarter measurement cycle for decades. In that environment, a 1 standard deviation (1 SD) measurement for a 1-year time frame (Ryan ALM asset allocation model since 1999) is +/- 10.5%. In the example below, 68% of the observations (1 SD) will fall between 16.5% and -4.5%. A 2 SD measurement would have the range for 95% of the observations between 27% and -15%. That gap, or should I say canyon, is a 1-year observation. Extend the measurement period to 5-years and the range of results is still wide but less so at +/- 9.8% for 2 SDs. It isn’t until you get beyond 10 years that the volatility associated with a fairly traditional asset allocation gets to a reasonable level.

Is there a way to bring more certainty to the asset allocation process that would allow for longer observation periods and less volatility? Absolutely! A plan sponsor and their advisors can adopt a bifurcated asset allocation in which a liquidity bucket is created that will fund and match the plan’s liability cash flows of benefits and expenses chronologically from the next month as far out as the allocation will cover (10+ years) allowing for the remainder of the alpha assets (all non-bond assets) to now grow unencumbered. The task for those assets is to meet future liabilities.

As the graph below highlights, a carefully constructed cash flow matching (CFM) portfolio can help plan sponsors wade through the volatility associated with shorter timeframes. The CFM portfolio will consist of investment grade bonds whose cash flows of interest and principal will be matched to the liability cash flows. This process now ensures (absent defaults) that the necessary liquidity is available when needed as those future promises have been SECURED. The remaining assets can now be managed as aggressively as the plan’s funded status dictates.

With this process, short-term market dislocations will no longer impact the plan’s ability to meet its obligations. There will be no forced selling to meet benefit payments. The alpha assets can now grow without fear of being sold at an unreasonable level. The CFM program takes care of your needs while establishing a buffer (longer investing horizon) from market corrections that happen on a fairly regular basis. This structure should also lead to less volatility related to contributions and the plan’s funded status.

Given the elevated US interest rate environment, now is the time to engage in this process. CFM will provide a level of certainty that doesn’t exist in a traditional asset allocation. This is a “sleep well at night” strategy that should become the core holding for DB pensions. As I mentioned in an earlier blog post today, bonds should only be used for the cash flows they produce. They should not be used as total return-seeking instruments. Leave that task to the alpha assets that will benefit from a longer investing period.

Another Challenging Month for US Fixed Income

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

S&P Dow Jones is out with its monthly “Dash Board” on a variety of benchmarks, both domestic and foreign. April proved challenging for both US equities and bonds. With regard to stocks, the S&P 500 was down -4.1% bringing the YTD performance to +6.04%. It was a tougher environment for both mid cap (-6.0%) and small cap (-5.6%). Small caps (S&P 600) continue to be pressured and the index is now down -3.3% YTD. As US interest rates continue on a course higher, US equities will continue to be challenged.

The higher US rates are also continuing to pressure US fixed income. The Aggregate Index produced a -1.8% April, and the index is now down -2.4% since the start of 2024 despite the rather robust YTM of 5.3%. As we’ve discussed on many occasions, bonds are the only asset class with a known cash flow of a terminal value and contractual coupon payments. As a result, bonds should be used for the certainty of those cash flows and specifically to defease pension liabilities. As a reminder, pension liabilities are bond-like in nature and they will move with changes in interest rates. Don’t use bonds as a total return strategy, as they will not perform in a rising rate environment. Sure, the nearly 40-year decline in rates made bonds and their historical performance look wonderful, but that secular trend is over.

Use the fixed income allocation to match asset cash flows of interest and principal to the liability cash flows of benefits and expenses. As a result, that portion of the total assets portfolio will have mitigated interest rate risk, while SECURING the promised benefits. Having ample liquidity is essential. Using bonds to defease pension liabilities ensures that the necessary liquidity will be available as needed. The current US interest rate environment may be pressuring total return-seeking fixed income managers, but it is proving cash flow matching programs with a very healthy YTM that dramatically reduces the cost of those future value payments. Don’t waste this golden opportunity.

Healthier Than Ever? Nah!

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

P&I produced an article yesterday titled, “Corporate Pension Funds Are Fully Funded, Healthier Than Ever. Now What?” According to Milliman, corporate pension plans are averaging roughly a funded ratio of 106%. This represents a healthy funded status, but it is by no means the healthiest ever. One may recall that corporate plans were funded in excess of 120% as recently as 2000. In what might be more shocking news, public pension plans were too when using a market discount rate (ASC 715 discount rate). Today, those public pension plans have a funded status of roughly 80% according to Milliman’s latest public fund report.

The question, “Now what”? is absolutely the right question to be asking. Many corporate plans have already begun de-risking, as the average exposure to fixed income is >45% according to P&I’s asset allocation survey through November 2023. Unfortunately, public pension systems still sit with only about 18% exposure to US fixed income, preferring a “let it ride” mentality as equities and alternatives account for more than 75% of the average plan’s asset allocation. Is this the right move? No. The move into alternatives has dried up liquidity, increased fees, and reduced transparency. Furthermore, just because a public plan believes that its sponsor is perpetual, does that make the system sustainable? You may want to be reminded about Jacksonville Police and Fire. There are other examples, too.

Whether the pension plan is corporate, multiemployer, or public, the asset allocation should reflect the funded status. There is no reason that a 60% funded plan should have the same asset allocation as one that is 90% or better funded. All plans should have both liquidity and growth buckets. The liquidity bucket will be a bond allocation (investment grade corporates in our case) that matches asset cash flows to liability cash flows of benefits and expenses. That bucket will provide all of the necessary liquidity as far into the future as the pension system can afford. The remaining assets will be focused on outperforming future liability growth. These assets will be non-bonds that now have the benefit of an extended investing horizon to grow unencumbered. Forcing liquidity in environments in which natural liquidity has been compromised only serves to exacerbate the downward spiral.

Pension America has the opportunity to stabilize the funded status and contribution expenses. They also have the chance to SECURE a portion of the promises. How comforting! We saw this movie a little more than 20 years ago. Are we going to treat this opportunity as a Ground Hog Day event and do nothing or are we going to be thoughtful in taking appropriate measures to reduce risk before the markets bludgeon the funded status? The time to act is now. Not after the fact.