Milliman Reports Improved Funding For Public Fund Pension Plans as of March 31, 2024

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

Milliman recently released results for its Public Pension Funding Index (PPFI), which covers the nation’s 100 largest public defined benefit plans.

Positive equity market performance in March increased the Milliman 100 PPFI funded ratio from 78.6% at the end of February to 79.7% as of March 31, representing the highest level since March 31, 2022, prior to the Fed’s aggressive rate increases. The previous high-water mark stood at 82.7%. The improved funding for Milliman’s PPFI plans was driven by an estimated 1.7% aggregate return for March 2024. Total fund performance for these 100 public plans ranged from an estimated 0.9% to 2.6% for the month. As a result of the relatively strong performance, PPFI plans gained approximately $85 billion in MV in March. The asset growth was offset by negative cash flow amounting to about $9 billion. It is estimated that the current asset shortfall relative to accrued liabilities is about $1.271 trillion as of March 31. 

In addition, it was reported that an additional 4 of the PPFI members had achieved a 90% or better funded status, while regrettably, 15 of the constituents remain at <60%. Given that changing US interest rates do not impact the calculation for pension liabilities under GASB accounting, the improvement in March’s collective funded status may be underreported, as US rates continued the upward trajectory begun as the calendar turned to 2024.

Tricky? Not Sure Why!

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

The WSJ produced an article on April 22, 2024 titled, “Path for 10-Year U.S. Treasury Yield to 5% Is Possible but Tricky” At the time of publication, the 10-year Treasury note yield was just under 4.7%. It is currently at 4.66%. Those providing commentary talked about the need to further reduce expectations for potential rate cuts of another 25 to 40 basis points. As you may recall, there were significantly greater forecasts of rate cuts at the beginning of 2024, but those have been scaled back in dramatic fashion.

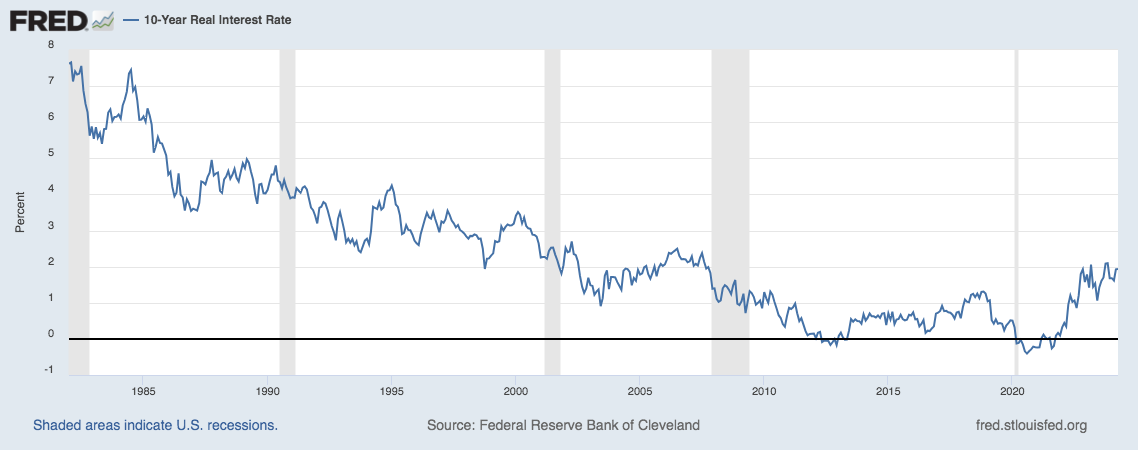
Given the current inflationary landscape in which the Consumer Price Index for All Urban Consumers (CPI-U) increased 0.4 percent in March and 3.5% annually, a move toward 5% for the US 10-year Treasury note’s yield shouldn’t be surprising or tricky. According to the graph below, the US 10-year yield has averaged a “real” yield of nearly 2% (1.934%) since 1984. A 2% inflation premium would place today’s 10-year Treasury note yield at roughly 5.6%.

Given the current economic conditions (2.9% GDP growth for Q1’24) and labor market strength (3.8% unemployment rate), it certainly doesn’t seem like the Fed’s “aggressive” action elevating the Fed Funds Rate from 0 to 5.5% today has had the impact that was anticipated. Inflation in 2024 has been sticky and may in fact be increasing. Should geopolitical issues grow in magnitude, inflation may get worse. These current conditions don’t say to me that a move to a 5% 10-year Treasury note yield should be tricky at all. As a reminder, the yield on this note hit 4.99% in late October 2023. Financial conditions have not gotten more restrictive since then.

Should the Treasury yield curve ratchet higher, with the 10-year eventually eclipsing 5%, plan sponsors would have a wonderful opportunity to secure the future promised benefits at significantly reduced cost in present value terms, especially if the cash flow matching portfolio used investment grade corporate bonds with premium yields. Although US corporate bond spreads are tight relative to average spreads, they still provide a healthy premium. Don’t let this rate environment pass without taking some risk from your plan’s asset allocation. We’ve seen that scenario unfold before and the outcome is scary.

What’s the Motivation?

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

There appears in the WSJ today an article stating that pension plans were pulling “hundreds of billions from stocks”. According to a Goldman analyst, “pensions will unload $325 billion in stocks this year, up from $191 billion in 2023″. We are told that proceeds from these sales will flow to both bonds and alternatives. First question: What is this estimate based on? Are average allocations now above policy normal levels necessitating a rebalancing? Are bonds more attractive given recent movements in yields?

Yes, equities have continued to rally through 2024’s first quarter, and the S&P 500 established new highs before recently pulling back. Valuations seem stretched, but the same argument could have been made at the end of 2023. Furthermore, US interest rates were higher heading into 2023’s fourth quarter. If bond yields were an attractive alternative to owning equities, that would have seemed the time to rotate out of equities.

The combination of higher interest rates and equity valuations have helped Corporate America’s pensions achieve a higher funded status, and according to Milliman, the largest plans are now more than 105% funded. It makes sense that the sponsors of these plans would be rotating from equities into bonds to secure that funded status and the benefit promises. Hopefully, they have chosen to use a cash flow matching (CFM) strategy to accomplish the objective. Not surprisingly, public pension plans are taking a different approach. Instead of securing the benefits and stabilizing the plan’s funded status and contribution expenses by rotating into bonds, they are migrating both equities and bonds into more alternatives, which have been the recipients of a major asset rotation during the last 1-2 decades, as the focus there remains one of return. Is this wise?

I don’t know how much of that estimated $325 billion is being pulled from corporate versus public plans, but I would suggest that much of the alternative environment has already been overwhelmed by asset flows. I’ve witnessed this phenomenon many times in my more than 40 years in the business. We, as an industry, have the tendency to arbitrage away our own insights by capturing more assets than an asset class can naturally absorb. Furthermore, the migration of assets to alternatives impacts the liquidity available for plans to meet ongoing benefits and expenses. Should a market correction occur, and they often do, liquidity becomes hard to find. Forced sales in order to meet cash flow needs only serve to exacerbate price declines.

Pension plans should remember that they only exist to meet a promise that has been made to the participant. The objective should be to SECURE those promises at a reasonable cost and with prudent risk. It is not a return game. Asset allocation decisions should absolutely be driven by the plan’s funded status and ability to contribute. They shouldn’t be driven by the ROA. Remember that alternative investments are being made in the same investing environment as public equities and bonds. If market conditions aren’t supportive of the latter investments, why does it make sense to invest in alternatives? Is it the lack of transparency? Or the fact that the evaluation period is now 10 or more years? It surely isn’t because of the fees being paid to the managers of “alternative” products are so attractive.

Don’t continue to ride the asset allocation rollercoaster that only ensures volatility, not success! The 1990’s were a great decade that was followed by the ’00s, in which the S&P 500 produced a roughly 2% annualized return. The ’10s were terrific, but mainly because stocks were rebounding from the horrors of the previous decade. I don’t know what the 2020s will provide, but rarely do we have back-to-back above average performing decades. Yes, the ’90s followed a strong ’80s, but that was primarily fueled by rapidly declining interest rates. We don’t have that scenario at this time. Why assume the risk?

The Truth Will Set You Free!

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

Managing a pension plan should be all about securing the promised benefits at a reasonable cost and with prudent risk. I believe that most plan sponsors would agree, yet that is not how plans are managed, especially public and multiemployer plans that continue to pursue the return on asset assumption (ROA) as if it were the Holy Grail. I’ve written quite a bit on this subject, including discussing asset consulting reports that should have the relationship of plan assets to plan liabilities on page one of the quarterly performance reports.

We know that pension liabilities are like snowflakes, as there are no two pension liability streams that are the same given the unique characteristics of each labor force. Furthermore, most pension actuaries only produce an annual update making more frequent (monthly/quarterly) updates more challenging. Would plan sponsors want a more frequent view of the liabilities if they were available? I think that they would. Again, if securing the promised benefits are the primary objective when it comes to managing a pension plan, then plan sponsors need a more frequent view of the relationship between assets and liabilities.

Why is this important? First and foremost, the capital markets are constantly moving, and the changes impact the value of the plan’s assets all the time. But it isn’t just the asset-side that is being impacted, as liabilities are bond-like in nature and they change as interest rates change. We’ve highlighted this activity in both the Ryan ALM Pension Monitor and the Ryan ALM Quarterly Newsletter. However, accounting rules for both multiemployer and public plans allow a static discount rate equivalent to the plan’s ROA to be used that hides the impact of those changing interest rates on the value of a plan’s liabilities and funded status.

What if a more frequent analysis was available at a modest cost. Would plan sponsors want to see how the funded status was behaving? Would they want that comparison available to help with asset allocation changes, especially if it meant reducing risk as funding improved? I suspect that they would. Well, there is good news. Ryan ALM, Inc. created a Custom Liability Index (CLI) in 1991. The CLI is designed to be the proper benchmark for liability driven objectives. The CLI calculates the present value of liabilities based on numerous discount rates (ASC 715 (FAS 158), PPA – MAP 21, PPA – Spot Rates, GASB 67, Treasury STRIPS and the ROA). The CLI calculates the growth rate, summary statistics, and interest rate sensitivity as a series of monthly or quarterly reports depending on the client’s desired frequency.

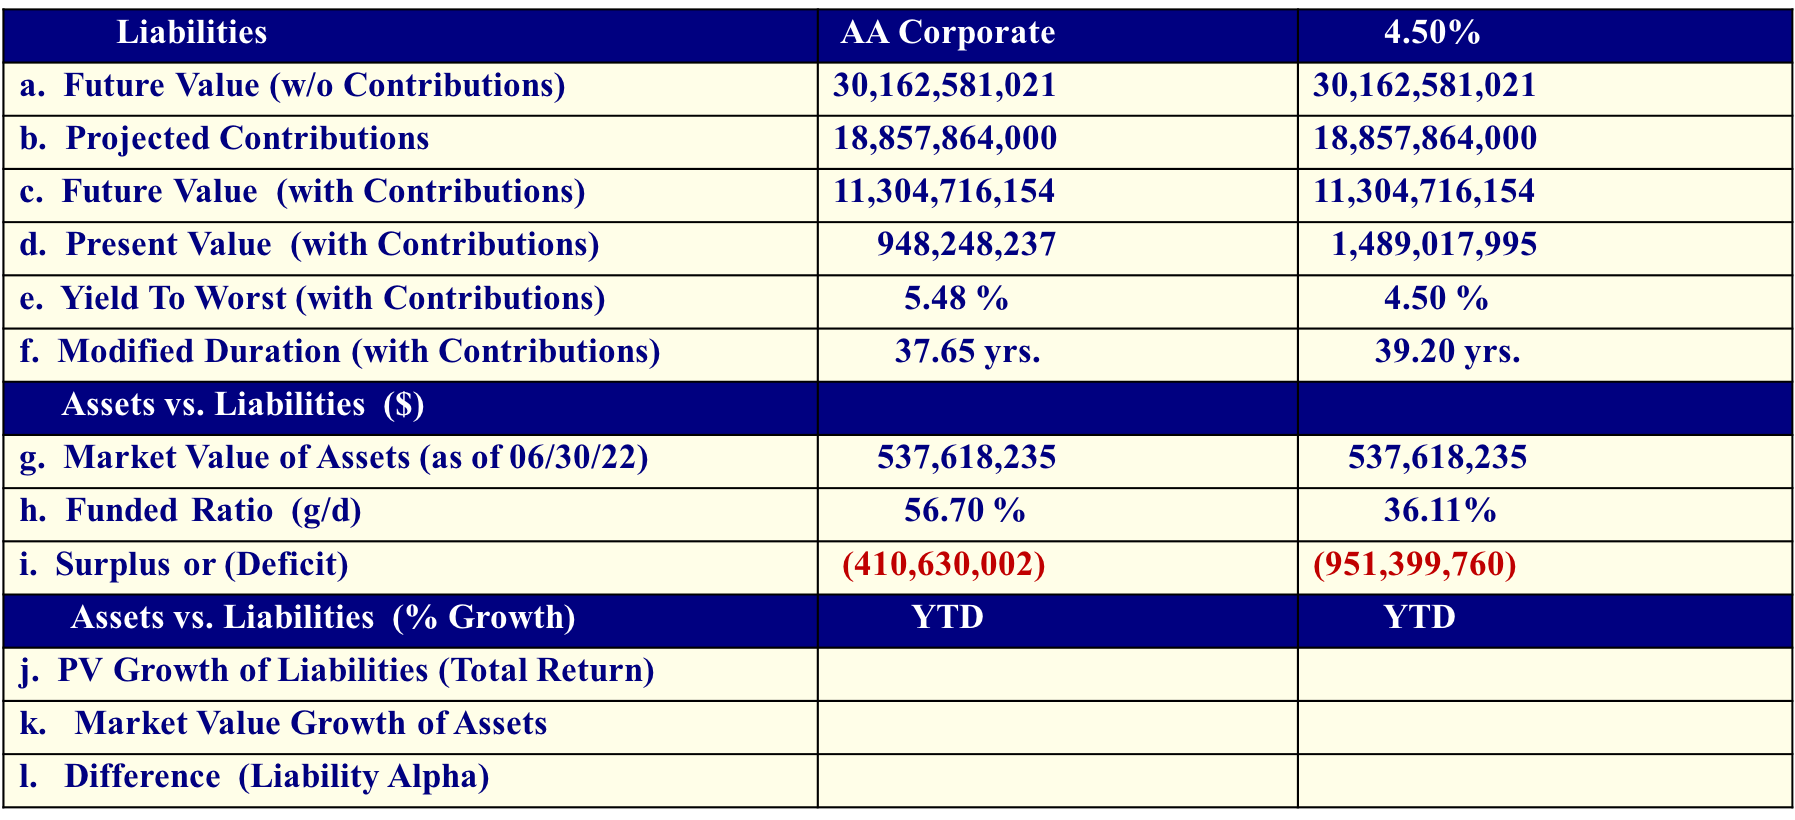
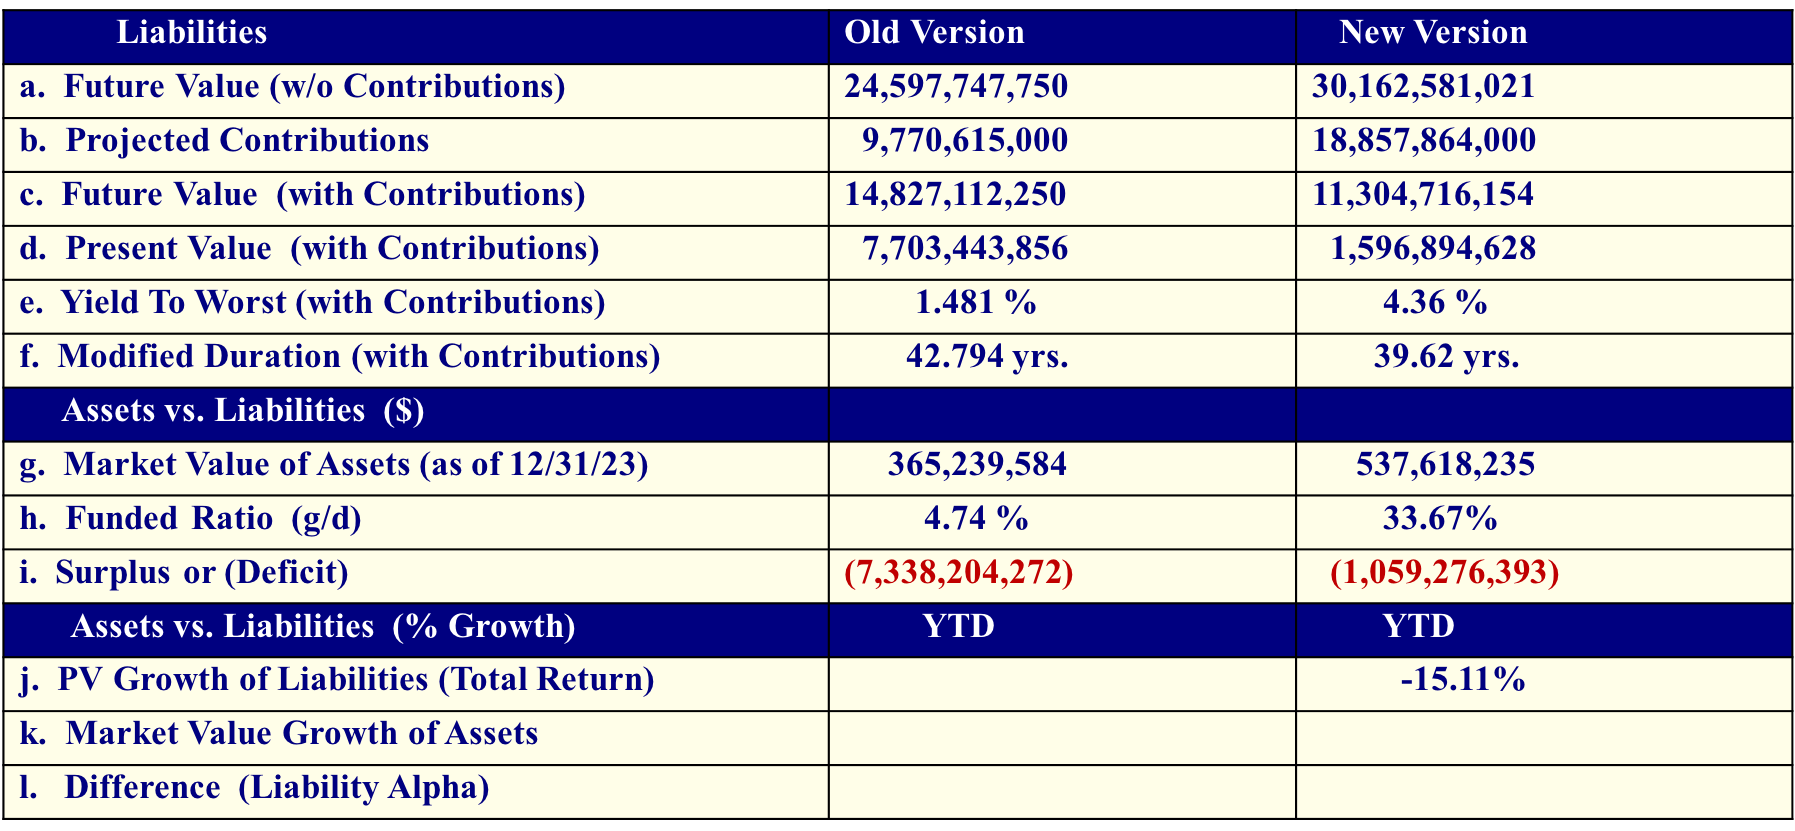
The above information is for an actual client, who we’ve been providing a CLI for 15+ years. This client has elected to receive quarterly reviews. They’ve also chosen to see the impact on liabilities for multiple discount rates, including a constant 4.5% ROA, which could easily be a pension plan’s ROA of say 7%. As you will note, the present value (PV) of those future value (FV) liabilities are different, and they could be dramatic, depending on the interest rate used. In this case, the AA Corporate rate (5.48% YTW) produces a funded ratio of 56.7%, while the flat 4.5% rate increases the PV liabilities thus reducing the funded status by more than 20%.

Using Treasury STRIPS as the discount rate produces the lowest funded ratio of 33.7% or 23% lower than using the AA Corporate discount rate.

With this information, plan sponsors and their advisors (consultants and actuaries) can make informed decisions related to contributions and asset allocation. Most plan sponsors are currently blind to these facts. As a result, decisions may be taken without having all of the necessary facts. Pension plans need to be protected and preserved (Ryan ALM’s mission). Having a complete understanding of what those future promises look like is essential.

You’ve made a promise: measure it – monitor it – manage it – and SECURE it…   

Get off the pension funding rollercoaster – sleep well!

ARPA Update as of April 5, 2024

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

Welcome to ECLIPSE DAY. Good luck found me in Dallas today for the TexPERS conference, as it is in the path of totality (complete darkness). Bad luck has it heavily overcast today following a Sunday that had beautiful blue skies. Oh, well. Perhaps we’ll get lucky.

APRA’s implementation by the PBGC has slowed, and we don’t have earthquakes (NJ residents are still shaking their heads), eclipses, or any other natural event to blame. That is not to say that nothing has been done, as there was one new application received during the week. Printing Local 72 Industry Pension Plan, a Priority Group 5 member, submitted its revised application seeking $37 million in SFA for the 787 plan participants. Beyond that, I suspect that they are busy reviewing the 19 applications that have been submitted that are currently waiting on approval. Only 5 of those applications are the initial version.

As we’ve discussed in previous updates, census data used to determine SFA grant payments has had to be checked and rechecked following the announcement that Central States received more SFA grant $ than they were eligible to receive since some of the participants were no longer alive. That revelation and the corrective measures taken to ensure that SFA monies are only being allocated for eligible participants has really slowed an already cumbersome review. Despite some of these impediments, it is great that 72 plans have gotten the SFA awards totaling nearly $54 billion.

We might not have great visibility as it pertains to the eclipse, but with US interest rates tending higher, inflation remaining more “sticky” than hoped, and a Fed that may just not cut in 2024, visibility is clearer that cash flow matching the SFA is the way to secure the benefits and expenses well into the future. As a reminder, as rates rise, the cost to defease those promised benefits falls. Higher rates aren’t only good for savers. They are particularly good for SFA recipients and all plan sponsors of DB plans.

As an example of how that math works, when I entered this industry on October 13, 1981, the 10-year Treasury was yielding 14.9%. It would have only cost you $17.82 to defease a $1,000 30-year liability. On August 4, 2020, when the 10-year Treasury yield dipped to 0.52%, it would have cost you an extraordinary $860.40 to defease the same $1,000 30-year liability. As of April 5, 2024, the 10-year Treasury is yielding 4.41% and the cost to defease that 30-year liability is much more manageable at $301.00. You should be cheering for a higher for longer scenario.

Corporate Funding Improves in March – Milliman

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

Milliman released the results of its latest Milliman 100 Pension Funding Index (PFI), which analyzes the 100 largest U.S. corporate pension plans. Pension funding improved for the third consecutive month to start the year, which now stands at 105.6% from 105.3% at the end of February. March was a bit different, however, as the discount rate declined 11 basis points increasing the collective liabilities by $14 billion to $1.299 trillion at the end of the quarter. Despite the increase in liabilities, investment performance was once again strong leading to a gain of $19 billion. Total assets now stand at $1.373 trillion.

Zorast Wadia, author of the PFI, stated, “the funded status gains may dissipate unless plan sponsors adhere to liability-matching investment strategies. Zorast’s observation is outstanding. Should rates fall from these levels, the cost to defease pension liabilities will grow. Now is the time to take risk off the table. Create certainty by getting off the asset allocation rollercoaster. Engaging in Cash Flow Matching (CFM) does not necessitate being an all or nothing strategy. Start your cash flow matching mandate and extend it as the funded status improves.

Return-seeking bond strategies will lose in an environment of rising rates. However, once a plan engages in CFM, the relationship between plan assets and liabilities is locked. Done correctly, assets and liabilities will move in tandem. It doesn’t matter what interest rates do, as benefit payments are future values that are not interest rate sensitive.

Act now to create some certainty! You’ll appreciate the great night’s sleep that you’ll start to have.

Ryan ALM, Inc. Pension Monitor Q1’24

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

We are pleased to share with you the Ryan ALM, Inc. Q1’24 pension monitor. This quarterly report compares different liability growth rates (based on a 12-year average duration) versus the asset growth rate for public, multiemployer, and corporate funds based on the P&I asset allocation survey of the top 1,000 plans which is updated annually.

With regard to Q1’24, Public pension funds (2.2%) underperformed Corporate Pension plans (3.7%) by 1.5% as ASC 715 discount rates showed a negative growth rate of -1.5% for Q1’24 while the discount rate using the average ROA (GASB accounting) would have appreciated by 1.8%. This outperformance by corporate pension plans was accomplished despite the much greater exposure to US fixed income within corporate pension plans (45.4%) versus both public (18.7%) and multiemployer (18.2%) and the far less exposure to US equities (12.6%) versus publics (21.9%) and multiemployer (22.2%).

Please don’t hesitate to reach out to us with any questions that you might have regarding this monitor.

What Are the Stats Telling Us?

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

Mark Twain quoted Benjamin Disraeli in his 1907 autobiography, when he stated “Lies, damned lies, and statistics” as a phrase used to describe the persuasive power of statistics to support weak arguments. Folks who regularly read my posts know that I am a frequent user of statistics to support my arguments, whether they are strong or weak. As a young man, I would study the sports section box scores and the backs of my baseball cards for every possible stat. It is just who I am. I love #s!

The investment management industry is inundated with statistics. You can’t go a day without a meaningful insight being shared in reference to our industry, the economy, interest rates, politics, companies, commodities, etc. I try to absorb as many of these stats as possible. However, it is easy to fall prey to confirmation bias, which humans are prone. Putting a series of statistics together and building an investment case is never easy. That said, we at Ryan ALM, Inc. have been saying since the onset of higher rates that the US Federal Reserve would likely be forced to keep rates higher for longer, as inflation would remain stickier than originally forecast.

We also didn’t see a recession on the horizon due to an incredibly strong US labor market, which continues to witness near historic lows for unemployment. Despite the retiring of the Baby Boomer generation, the labor participation rate is up marginally during this period of higher rates, indicating that more folks are looking for employment opportunities at this time. They are being supported by the fact that job openings remain quite elevated relative to pre-Covid-19 levels at roughly 880k. When people work, they spend! Wage growth recently surprised to the upside. Will demand for goods and services follow? It usually does.

Furthermore, as we’ve disclosed on many occasions, financial conditions are NOT tight despite the rapid rise in US interest rates from the depths induced by the pandemic. Long-term US rates remain below the 50-year average, and in the case of the US 10-year Treasury note, the yield difference is roughly -2.1%. Does that give the Fed some room to possibly increase rates should inflation remain elusive?

In just the past week, we’ve had oil touch $85/barrel, the Atlanta Fed’s GDPNow model increase its forecast for Q1’24 growth from 2.3% to 2.8%, a Baltimore bridge collapse that will impact shipping and create additional expense and delays, housing that once again exceeded expectations, Fed (Powell) announcements that a recession wasn’t on the horizon, job growth (ADP) that was the highest in 8 months, manufacturing that stopped contracting for the first time since 2022 (17 months), and on and on and… Am I kidding myself that our case for higher for longer is the right call? Am I only using certain stats to “confirm” the Ryan ALM argument?

We don’t know. But here is the good news. Our investment strategy doesn’t care. As cash flow matching experts, we are agnostic as to the direction of rates. Yes, higher rates mean lower costs to defease those future benefit promises, so higher rates are good. However, once we match asset cashflows of interest and principal to the liability cash flows (benefit payments and expenses), the direction of rates becomes irrelevant, as future values are not interest rate sensitive. Building an investment case for cash flow matching was challenging when rates were at historic lows. It is much easier today, as one can invest in high quality investment-grade corporate bonds and get yields in the range of 5%-5.5%, which is a significant percent of the average return on asset assumption (ROA) with much less risk and volatility of investing in equities and other alternatives.

I don’t personally see a case for the Fed to cut rates in the near future. I think that it would be a huge mistake to once again ease monetary policy before the Fed’s objective has been achieved. I lived through the ’70s and witnessed first-hand the impact on the economy when the Fed took its collective foot off the brake. As a result, I entered this industry in 1981 when the 10-year Treasury yield was at 14.9%. The Fed can’t afford to repeat the sins of the past. I believe that they know that and as a result, they won’t act impulsively this time.

Corporate Pension Funding Continues to Improve

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

The Milliman organization does a terrific of providing frequent and very useful updates through their Milliman 100 Pension Funding Index (PFI). They are reporting that the funded status improved by $26 billion in February for the largest 100 corporate defined benefit pension plans. The funded status at the end of February sat at 104.9% up from 102.8% at the end of January 2024.

All of the improvement in the funded status is the result of a higher discount rate that reduced the present value of those future pension promises. Unlike public pension plans, corporate accounting uses a AA corporate rate to value liabilities and not the ROA. Assets don’t need to rise in order for pension funds to show improvement in the funded status. In fact, during the month, Milliman estimates that liabilities fell in value by $30 billion. The current funding surplus for the members of this index stands at $63 billion at month end.

What’s next for these companies? Much of Corporate America has already begun to de-risk their plans. For those that haven’t the time is now to consider taking some risk out of the asset allocation. We certainly don’t want to see a repeat from 1999, when pensions were well over-funded on to see that funded status deteriorate rapidly with the advent of two major equity market declines. Importantly, de-risking doesn’t mean getting out of the pension game. it does mean that you, as the sponsor, don’t want to continue to ride the asset allocation rollercoaster up and down which can impact contribution expenses.

Migrate your fixed income from a return-seeking mandate to one that is now going to use bond cash flows of interest and principal to match the liability benefit payments. In an uncertain environment as to the direction of US interest rates, utilizing a cash flow matching (CFM) strategy will lock up the relationship with those pesky liabilities and eliminate interest rate risk for that portion of the portfolio. How comforting is that?

A Contrarian Approach That is Becoming More Common?

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

I suspect that some (perhaps) many folks in our industry are becoming a little tired of my constant drum beat requesting a change in how pension plans are managed. I’m sorry if that is the case, but I have a reason to speak out often, if not loudly. My goal/mission, and that of Ryan ALM, Inc., is to protect and preserve defined benefit plans for the masses. I believe wholeheartedly that DB plans are superior to any other retirement program since they provide the monthly promise with little involvement from the participant, who may have particularly wonderful skills used in their day-to-day lives, but investing isn’t likely one of them.

By espousing Cash Flow Matching (CFM) as an important investment strategy, particularly in this period of attractive interest rates, we are bringing pension management generally and asset allocation strategies specifically back to its roots. The SECURING of the pension promise must be the primary objective for plan fiduciaries. Better yet, it should be accomplished at a reasonable cost and with prudent risk. As I’ve discussed before, a CFM strategy brings an element of certainty to the management of pensions that have embraced uncertainty through asset allocation strategies that are subject to the whims of the markets.

The riding of the asset allocation rollercoaster in pursuit of a performance objective does little to secure the pension promise, but it certainly adds to annual volatility of both the funded status and contribution expenses. Is that the outcome that the sponsors of these plans and the participants want? Heck no! Are we at Ryan ALM tilting at or own windmills? I sure hope not.

I’ve been heartened recently to read several articles favoring a return to pension basics, including the focus on the pension promise to drive asset allocation through a CFM implementation. I’m not afraid to be a lone wolf, and nearly 1,400 blog posts support that claim, but it is comforting to have some company, as being a contrarian outside of the “herd” has been described as being as painful as chewing off one’s left arm – OUCH! In one specific instance, Stephen Campisi, recently posted his article on LinkedIn.com, in which he espoused a similar bifurcated approach – liquidity and growth buckets – to pension asset allocation. He also reminded everyone that “aiming” at the correct objective was essential. In this case, he correctly cited that the objective was the promise that had been given to the participant.

Nothing would please me more than to have the entire industry once again realize the significant importance of the defined benefit plan and its role in securing a dignified retirement. Eliminating the rollercoaster cycles of performance will go a long way to preserving their use. Adopting a CFM strategy that secures the monthly promises at a reasonable cost and with prudent risk is the first step in the process. I look forward to you jumping on our bandwagon.