Are Investors About to Get Their Comeuppance?

By: Russ Kamp, CEO, Ryan ALM, Inc.

As we’ve discussed in this blog on many occasions, the U.S. interest rate decline from 1982 to 2022 fueled risk assets well beyond their fundamentals. During the rate decline, investors became accustomed to the US Federal Reserve stepping in when markets and the economy looked dicey. There seems to be a massive expectation that the “Fed” will once again support those same risk assets by initiating another rally through a rate decline perhaps as soon as September. Is that action justified? I think not!

Recent inflation data, including today’s PPI that came in at 0.9% vs. 0.2% expected, should give pause to the crowd screaming for lower rates. Yes, employment #s published last week were very weak, and they got weaker when Erika McEntarfer, the commissioner of the Bureau of Labor Statistics, was fired after releasing a jobs report that angered President Donald Trump. In addition, we have Secretary of the Treasury, Scott Bessent, demanding rates be cut by as much as 150-175 bps, claiming that all forecasting “models” suggest the same direction for rates. Is that true? Again, I think not.

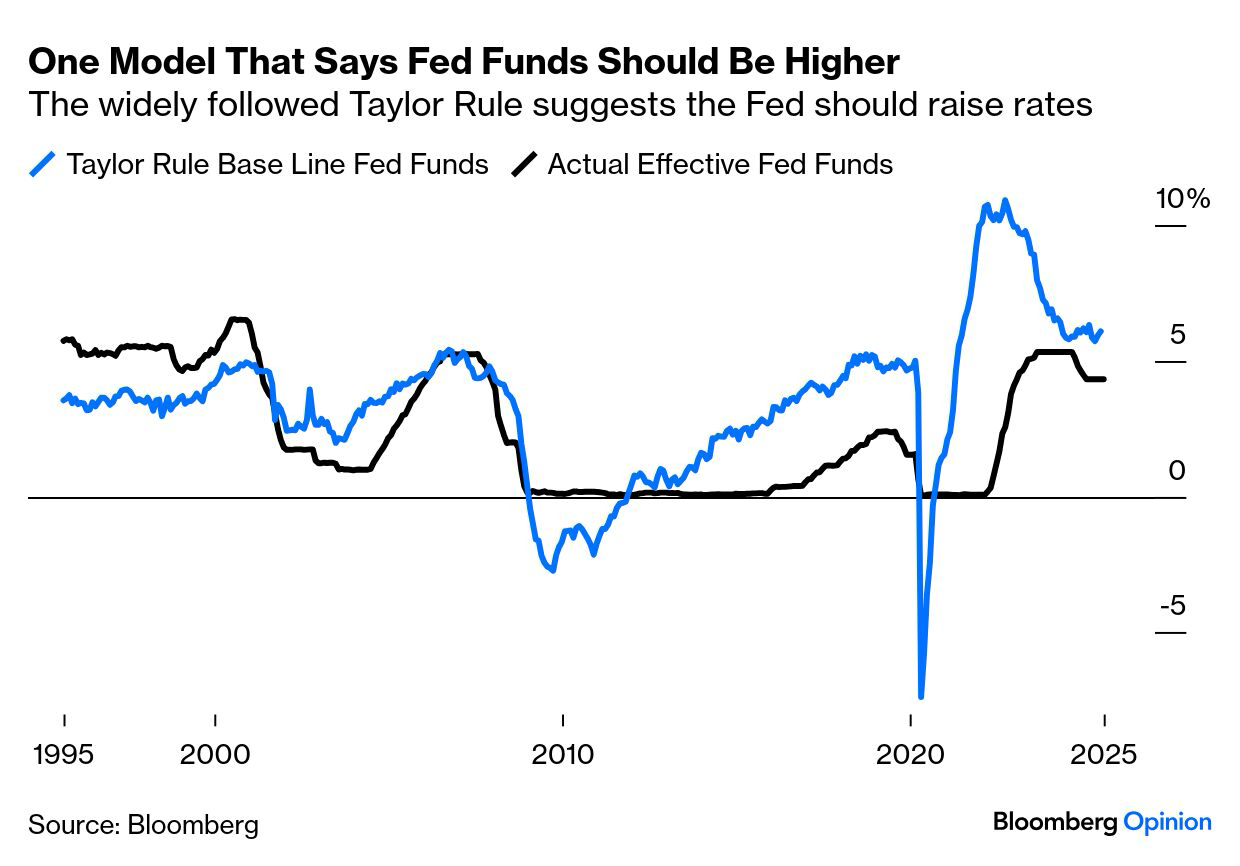
You may recall that I published a blog post on July 10, 2025 titled “Taylor-Made”, in which I wrote that the Taylor Rule is an economic formula that provides guidance on how central banks, such as the Federal Reserve, should set interest rates in response to changes in inflation and economic output. The rule is designed to help stabilize an economy by systematically adjusting the central bank’s key policy rate based on current economic conditions. It is designed to take the “guess work” out of establishing interest rate policy.

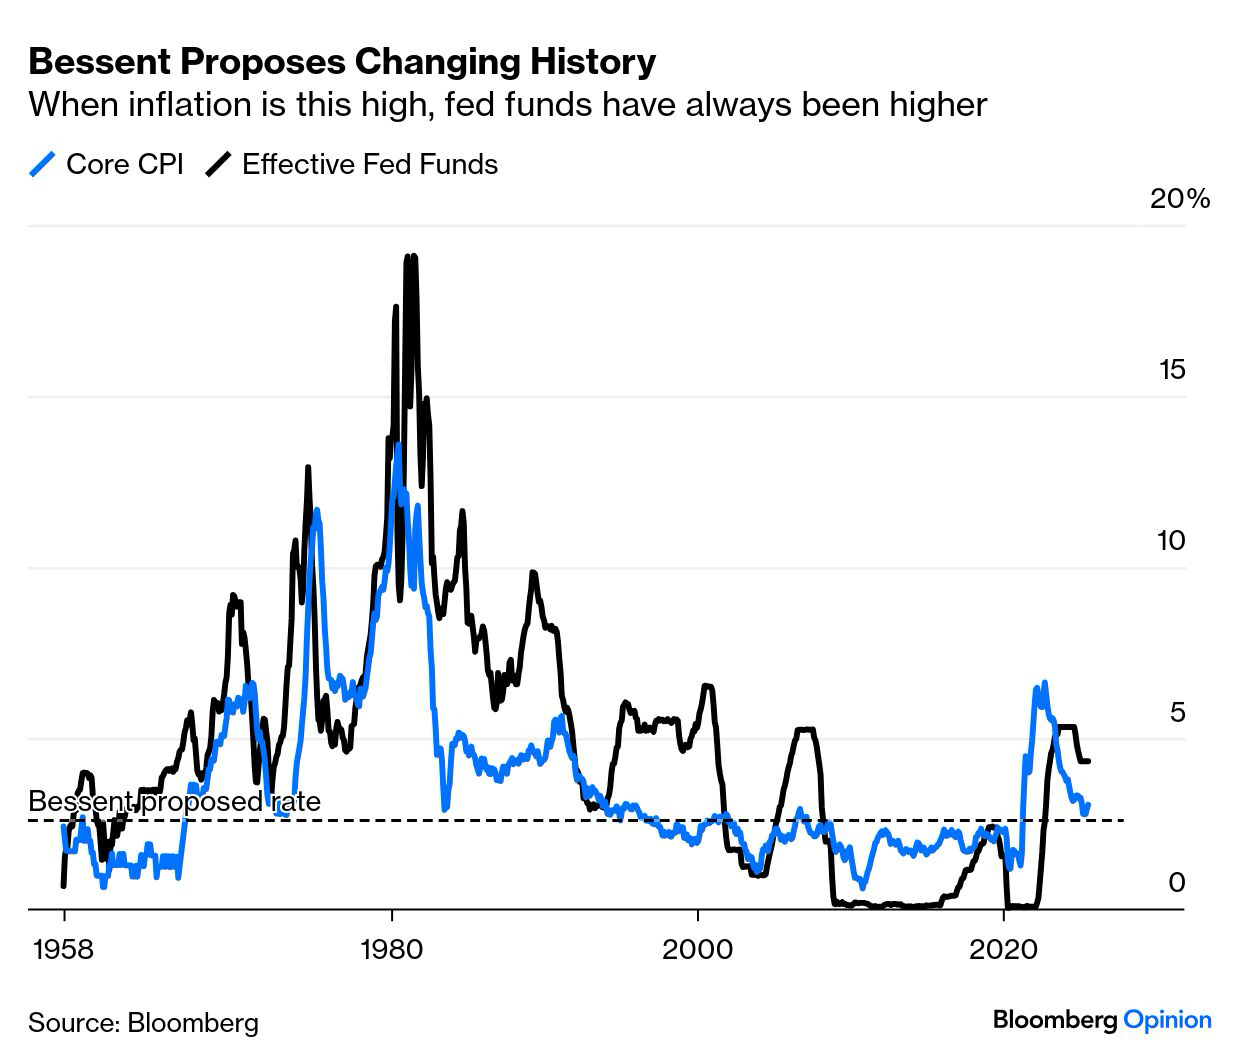
In John Authers (Bloomberg) blog post today, he shared the following chart:

Calling for a roughly 2.6% Fed Funds rate in an environment of 3% or more core and sticky inflation is not prudent, and it is not supported by history. Furthermore, the potential impact from tariffs will only begin to be felt as most went into effect as of August 1, 2025.

Getting back to the Taylor Rule, Authers also provided an updated graph suggesting that the Fed Funds rate should be higher today. In fact, it should be at a level about 100 bps above the current 4.3% and more than 270 bps above the level that Bessent desires.

Investors would be wise to exit the lower interest rate train before it fuels a significant increase in U.S. rates as inflation once again rises. The impact of higher rates will negatively impact all risk assets. Given that a Cash Flow Matching (CFM) strategy eliminates interest rate risk through the defeasement of benefits and expenses that are future values and thus not interest rate sensitive, one could bring an element of certainty to this very uncertain economic environment before investors get their comeuppance! Don’t wait for the greater inflation to appear, as it might just be too late at that point to get off the lower interest rate train before it plummets into a ravine.

When Should I Use CFM?

By: Russ Kamp, CEO, Ryan ALM, Inc.

Good morning. I’m currently in Chicago in the midst of several meetings. Yesterday’s meetings were outstanding. As you’d expect, the conversations were centered on DB pension plans and the opportunity to de-risk through a Cash Flow Matching strategy (CFM) in today’s economic environment. The line of questioning that I received from each of my meeting hosts was great. However, there does seem to be a misconception on when and how to use CFM as a de-risking tool. Most believe that you engage CFM for only the front-end of the yield curve, while others think that CFM is only useful when a plan is at or near full funding. Yes, both of those implementations are useful, but that represents a small sampling of when and how to implement CFM. For instance:

As a plan sponsor you need to make sure that you have the liquidity necessary to meet you monthly benefits (and expenses). Do you have a liquidity policy established that clearly defines the source(s) of liquidity or are you scurrying around each month sweeping dividends, interest, and if lucky, capital distributions from your alternative portfolio? Unfortunately, most plan sponsors do not have a formal liquidity policy as part of their Investment Policy Statement (IPS). CFM ensures that the necessary liquidity is available every month of the assignment. There is not forced selling!

Do you currently have a core fixed income allocation? According to a P&I asset allocation survey, public pension plans have an average 18.9% in public fixed income. How are you managing that interest rate risk, which remains the greatest risk for an actively managed fixed income portfolio? As an industry, we enjoyed the benefits of a nearly four decades decline in U.S. interest rates beginning in 1982. However, the prior 28-years witnessed rising rates. Who knows if the current rise in rates is a blip or the start of another extended upward trend? CFM defeases future benefit payments which are not interest rate sensitive. A $2,000 payment next month or 10-years from now is $2,000 whether rates rise or fall. As a result, CFM mitigates interest rate risk.

As you have sought potentially greater returns from a move into alternatives and private investments, not only has the available liquidity dried up, but you need a longer time horizon for those investments to mature and produce the expected outcome. Have you created a bridge within your plan’s asset allocation that will mitigate normal market gyrations? A 10-year CFM allocation will not only provide your plan with the necessary monthly liquidity, but it is essentially a bridge over volatile periods as it is the sole source of liquidity allowing the “alpha” assets to just grow and grow. That 10-year program coincides nicely with many of the lock-ins for alternative strategies.

There has been improvement in the funded status of public pension plans. According to Milliman, as of June 30, 2025, the average funded ratio for the constituents in their top 100 public pension index is now 82.9%, which is the highest level since December 2021. That’s terrific to see. Don’t you want to preserve that level of funding and the contribution expenses that coincide with that level? Riding the rollercoaster of performance can’t be comforting. Given what appears to be excessive valuations within equity markets and great uncertainty as it relates to the economic environment, are you willing to let your current exposures just ride? By allocating to a CFM program, you stabilize a portion of your plan’s funded status and the contributions associated with those Retired Lives Liability. Bringing a level of certainty to a very uncertain process should be a desirable goal for all plan sponsors and their advisors.

If I engage a CFM mandate, don’t I negatively impact my plan’s ability to meet the return objective (ROA) that we have established? NO! The Ryan ALM CFM portfolio will be heavily skewed to investment-grade corporate bonds (most portfolios are 100% corporates) that enjoy a significant premium yield relative to Treasuries and agencies. As mentioned previously, public pension plans already have an exposure to fixed income. That exposure is already included in the ROA calculation. By substituting a higher yielding CFM portfolio for a lower yielding core fixed income program benchmarked to the Aggregate index, you are enhancing the plan’s ability to achieve the ROA while also eliminating interest rate risk. A win-win in my book!

So, given these facts, how much should I allocate to a CFM mandate? The answer is predicated on many factors, including the plan’s current funded status, the ability to contribute, whether or not the plan is in a negative cash flow situation, the Board’s risk appetite, the current ROA, and others. Given that all pension systems’ liabilities are unique, there is no one correct answer. At Ryan ALM, we are happy to provide a detailed analysis on what could be done and at what cost to the plan. We do this analysis for free. When can we do yours?

A few Observations from Newport

By: Russ Kamp, CEO, Ryan ALM, Inc.

As I mentioned in my ARPA update on Monday, I had the pleasure of attending the Opal Public Fund Forum East in beautiful Newport, RI, and neither the conference nor Newport disappointed. I don’t attend every session during the conference, but I do try to attend most. In all honesty, I can’t listen to another private equity discussion.

As always, there were terrific insights shared by the speakers/moderators, but there were also some points being made that are just wrong. With this being my first day back in the office this week, I don’t have the time to get into great detail regarding some of my concerns about what was shared, but I’ll give you the headline and perhaps link a previous blog post that addressed the issue.

First, DB pension plans are not Ponzi Schemes that need more new participants than retirees to keep those systems well-funded and functioning. Actuaries determine benefits and contributions based on each individual’s unique characteristics. If managed appropriately, systems with fewer new members can function just fine. Yes, plans that find themselves in a negative cash flow situation need to rethink the plan’s asset allocation, but they can continue to serve their participants just fine. Remember: a DB pension plan’s goal is to pay the last benefit payment with the last $. It is not designed to provide an inheritance.

Another topic that was mentioned several times was the U.S. deficit and the impending economic doom as a result. The impact of the U.S. deficit is widely misunderstood. I was fortunate to work with a brilliant individual at Invesco – Charles DuBois – who took the time to educate me on the subject. As a result of his teaching, I now understand that the U.S. has a potential demand problem. Not a debt issue. I wrote a blog post on this subject back in 2017. Please take the time to read anything from Bill Mitchell, Warren Mosler, Stephanie Kelton, and other disciples of MMT.

Lastly, the issue of flows into strategies/asset classes seems not to be understood. The only reason we have cycles in our markets is through the movement of assets into and out of various products/strategies. Too much money chasing too few good ideas creates an environment in which those flows can overwhelm future returns. It is the same for individual asset management firms. Many of the larger asset management firms have become sales organizations in lieu of investment management organizations as they long ago eclipsed the natural capacity of their strategies. In the process, they have arbitraged away their insights which may have provided the basis for some value-added in the past. I believe that too much money is chasing many of the alternative/private strategies. In the process, future returns and liquidity will be negatively impacted. We’ve already seen that within private equity. Is private debt next?

Again, always enjoy seeing friends and industry colleagues at this conference. I continue to learn from so many of the presenters even after 44-years in the industry. However, not everything that you hear will be correct. It is up to you to challenge a lot of the “common wisdom” being shared.

AI Needs An Education Regarding ALM/CFM!

By: Russ Kamp, CEO, Ryan ALM, Inc.

I asked an AI tool that I use the following: Asset/Liability Management (ALM) is an effective tool for pensions. What strategies are currently being deployed?

As usual, the response was nearly instantaneous, but was it correct? Here is what I got:

Overview

“Asset/liability management (ALM) remains central to pension fund sustainability, aiming to balance expected pension liabilities with optimal asset growth. In 2025, pension funds deploy a range of strategies to ensure their ability to meet long-term obligations while managing risk efficiently.” No argument there. However, here is a list of the strategies. This is where I have an issue.

Key ALM Strategies Currently in Use

1. Liability-Driven Investing (LDI)

  • Matching Asset Duration to Liabilities: Many corporate pension plans invest in high-quality bonds with durations closely matching those of plan liabilities to mitigate interest rate risk. This ensures that both assets and liabilities react similarly to interest rate changes, stabilizing the funded status from year to year.
  • Glidepath Strategies: Plans gradually shift the asset mix towards more fixed-income securities as funded status improves or as the plan matures, further reducing risk and aligning assets with near-term liabilities.

2. Dynamic Asset Allocation

  • Strategic Shifts in Asset Mix: Pension funds adjust allocations based on changing liabilities, market conditions, and funding status. For instance, U.S. public pension plans have recently shifted asset allocations to maintain return expectations and recover from volatility.
  • Scenario-Based Modeling: Funds use forward-looking models to stress-test outcomes under varying economic scenarios, reviewing assumptions about returns, inflation, and participant demographics.

3. Risk Transfer Solutions

  • Pension Risk Transfer (PRT): Many sponsors employ annuity purchases and lump-sum windows to reduce long-term liability, transferring obligations to insurers. In 2024, settlement payouts (such as annuity buyouts) remained a significant tool for risk management among major pension plans.

4. Liability Modeling Innovations

  • Member-Level Simulation: Advanced models project individual participant cash flows, account for currency exposure, and enable granular liability projections. Such approaches allow more precise matching of assets to future obligations, improving ALM decision-making.
  • Regular Reviews and Assumption Updates: ALM programs, such as those at CalPERS, involve systematic reviews of demographic and financial assumptions (e.g., life expectancy, inflation), with revisions made every four years to incorporate emerging trends.

5. Use of Custom Benchmarks

  • Liability-Mimicking Portfolios: Funds create tailored portfolios (“benchmark” portfolios) that track the liability profile as closely as possible, often blending nominal bonds, inflation-linked bonds, and equities according to the plan’s specifics (such as maturity and inflation sensitivity).

That’s it? Where is Cash Flow Matching (CFM)? In each of these scenarios, liquidity needed to fund benefits and expenses is missing. Duration strategies minimize interest rate risk, but don’t produce timely liquidity to fully fund B+E. Furthermore, duration strategies that use an “average” duration or a few key rates don’t duration match as well as CFM that duration matches EVERY month of the assignment.

In the second set of products – dynamic asset allocation – what is being secured? Forecasts related to future economic scenarios come with a lot of volatility. If anyone had a crystal ball to accomplish this objective with precision, they’d be minting $ billions!

A PRT or risk transfer solution is fine if you don’t want to sustain the plan for future workers, but it can be very expensive to implement depending on the insurance premium, current market conditions (interest rates), and the plan’s funded status

In the liability modeling category, I guess the first example might be a tip of the hat to cash flow matching, but there is no description of how one actually matches assets to those “granular” liability projections. As for part two, updating projections every four years seems like a LONG TIME. In a Ryan ALM CFM portfolio, we use a dynamic process that reconfigures the portfolio every time the actuary updates their liability projections, which are usually annually.

Lastly, the use of Custom benchmarks as described once again uses instruments that have significant volatility associated with them, especially the reference to equities. What is the price of Amazon going to be in 10-years? Given the fact that no one knows, how do you secure cash flow needs? You can’t! Moreover, inflation-linked bonds are not appropriate since the actuary includes an inflation assumption in their projections which is usually different than the CPI.  

Cash Flow Matching is the only ALM strategy that absolutely SECURES the promised benefits and expenses chronologically from the first month as far out as the allocation will go. It accomplishes this objective through maturing principal and interest income. No forced selling to meet those promises. Furthermore, CFM buys time for the residual assets to grow unencumbered. This is particularly important at this time given the plethora of assets that have been migrated to alternative and definitely less liquid instruments.

As mentioned earlier, CFM is a dynamic process that adapts to changes in the pension plan’s funded status. As the Funded ratio improves, allocate more assets from the growth bucket to the CFM portfolio. In the process, the funded status becomes less volatility and contribution expenses are more manageable.

I’m not sure why CFM isn’t the #1 strategy highlighted by this AI tool given its long and successful history in SECURING the benefits and expenses (B&E). Once known as dedication, CFM is the ONLY strategy that truly matches and fully funds asset cash flows (bonds) with liability cash flows (B&E). Again, it is the ONLY strategy that provides the necessary liquidity without having to sell assets to meet ongoing obligations. It doesn’t use instruments that are highly volatile to accomplish the objective. Given that investment-grade defaults are an extremely rare occurrence (2/1,000 bonds), CFM is the closest thing to a sure bet that you can find in our industry with proven performance since the 1970s.

So, if you are using an AI tool to provide you with some perspective on ALM strategies, know that CFM may not be highlighted, but it is by far the most important risk reducing tool in your ALM toolbox.

Really Only One Significant Influence

By: Russ Kamp, CEO, Ryan ALM, Inc.

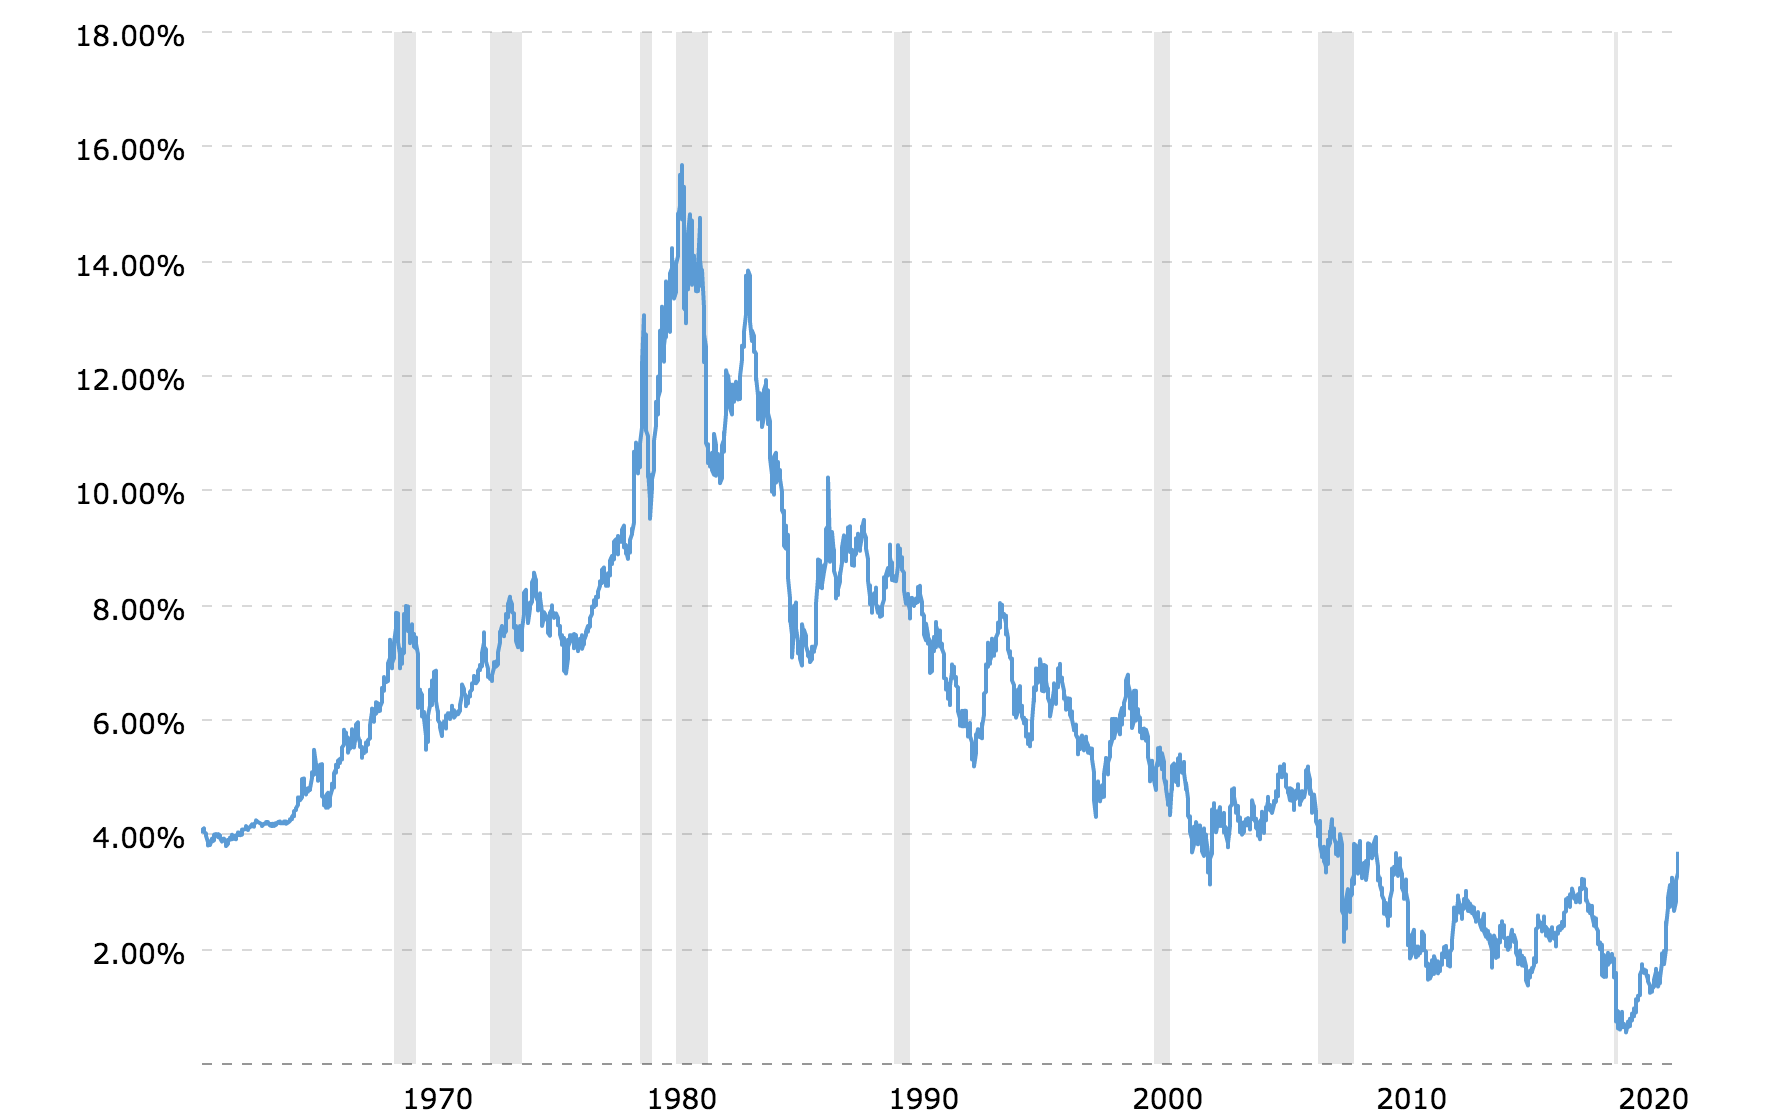
Managing fixed income (bonds) can be challenging as there are a plethora of risks that must be evaluated including, but not limited to, credit, liquidity, maturity/duration, yield, prepayment and reinvestment risk, etc. within the investment-grade universe. But the greatest risk – uncertainty – remains interest rate risk. Who really knows the future direction of rates? As the graph below highlights, U.S. interest rates have moved in long-term secular trends with numerous reversals along the way. Does that mean that we are headed for a protracted period of rising rates similar to what was witnessed from 1953 to 1981 or is this a head fake along the path to historically low rates?

When rates are falling, it is very good for bonds as they not only capture the coupon, but they get some capital appreciation, too. However, when rates rise, it is a very different game. Yes, rising interest rates are very good for pension funds from a liability perspective, as the present value (PV) of those future benefit payments (I.e. liabilities) is reduced, but the asset side may be hurt and not only for bonds but other asset classes as well.

No alternative text description for this image

This is the primary reason why bonds should be used for their cash flows of interest and principal and not as a performance generator. The cash flows should be used to meet monthly benefits and expenses chronologically through a cash flow matching strategy (CFM). Unfortunately, Bonds are frequently used for performance and perhaps diversification benefits while compared to a generic index, such as the BB Aggregate index, which doesn’t reflect the unique characteristics of the pension plan’s liabilities.

U.S. interest rates are presently elevated but aren’t high by historic standards. However, the current level of rates does provide the plan sponsor with a wonderful opportunity to take risk from their traditional asset allocation by defeasing a portion of the plan’s liabilities from next month out as far as the allocation will cover. While the bond portfolio is funding monthly obligations, the remaining assets can just grow unencumbered.

Given the uncertainty regarding the current inflationary environment, betting that U.S. rates will fall making a potential “investment” in bonds more lucrative is nothing short of a crapshoot. Investing in a CFM strategy helps to mitigate interest rate risk as future values are not interest rate sensitive.

Problem/Solution: Asset Allocation

By: Ronald J. Ryan, CFA, Chairman, Ryan ALM, Inc.

In this post, Ron continues with his series on identifying solutions to various pension-related problems. This one addresses the issue of asset allocation being driven exclusively from an asset perspective.

Most, if not all asset allocation models are focused on achieving a total return target or hurdle rate… commonly called the ROA (return on assets). This ROA target return is derived from a weighting of the forecasted index benchmark returns for each asset class except for bonds which uses the yield of the index benchmark. These forecasts are generally based on some historical average (i.e. last 20 years or longer) with slight adjustments based on recent observations. As a result, it is common that most pensions have the same or similar ROA. 

This ROA exercise ignores the funded status. It is certainly obvious that a 60% funded plan should have a much higher ROA than a 90% plan. But the balancing item is contributions. If the 60% funded plan would pay more in contributions than the 90% plan (% wise) then it can have a lower ROA. I guess the question is what comes first. And the answer is the ROA with contributions as a byproduct of that ROA target. The actuarial math is whatever the assets don’t fund… contributions will fund.

If the true objective of a pension is to secure and fully fund benefits and expenses (B+E) in a cost-efficient manner with prudent risk, then you would think that liabilities (B+E) would be the focus of asset allocation. NO, liabilities are usually missing in the asset allocation process. Pensions are supposed to be an asset/liability management (ALM) process not a total return process. Ryan ALM recommends the following asset allocation process:

Calculate the cost to fully fund (defease) the B+E of retired lives for the next 10 years chronologically using a cash flow matching (CFM) process with investment grade bonds. CFM will secure and fully fund the retired lives liabilities for the next 10 years. Then calculate the ROA needed to fully fund the residual B+E with the current level of contributions. This is calculated through an asset exhaustion test (AET) which is a GASB requirement as a test of solvency. The difference is GASB requires it on the current estimated ROA before you do this ALM process. Ryan ALM can create this calculated ROA through our AET model. If the calculated ROA is too high, then either you reduce the allocation to the CFM or increase contributions or a little bit of both. If the calculated ROA is low, then increasing the allocation to CFM is appropriate. Running AET iterations can produce the desired or most comfortable asset allocation answer.  

Cash flow matching (CFM) will provide the liquidity and certainty needed to fully fund B+E in a cost-efficient manner with prudent risk. The Ryan ALM model (Liability Beta Portfolio™ or LBP) will reduce funding costs by about 2% per year or roughly 20% for 1-10 years of liabilities. We will use corporate bonds skewed to A/BBB+ issues. According to S&P, investment grade defaults have averaged 0.18% of the IG universe annual for the past 40-years. Fortunately, Ryan ALM has never experienced a bond default in its 21-year history (knock wood).

Assets are a team of liquidity assets (bonds) and growth assets (stocks, etc.) to beat the liability opponent. They should work together in asset allocation to achieve the true pension objective.

For more info on cash flow matching, please contact Russ Kamp, CEO at  rkamp@ryanalm.com

Milliman: Corporate Pension Funding Up

By: Russ Kamp, CEO, Ryan ALM, Inc.

Milliman released its monthly Milliman 100 Pension Funding Index (PFI), which analyzes the 100 largest U.S. corporate pension plans, and they are reporting that the collective funded ratio has risen to 105.1% as of June 30th from 104.9% at the end of May. The driving force behind the improved funding was the powerful 2.6% asset return for the index’s members, which more than offset the growth in pension liabilities as the discount rate fell by 19 bps.

As a result of the significant appreciation during the month, the Milliman PFI plan assets rose by $27 billion to $1.281 trillion during the month from $1.254 trillion at the end of May. The discount rate fell to 5.52% in June, from 5.71% in May and it is now down slights from 5.59% at the beginning of the year. 

“The second quarter of 2025 was a win-win for pensions from both sides of the balance sheet, as market gains of 3.42% drove up plan assets while modest discount rate increases of 2 basis points reduced plan liabilities and resulted in the highest funded ratio since October 2022,” said Zorast Wadia, author of the PFI.

Zorast further stated that “if discount rates decline in the second half of the year, plan sponsors will need to be ever more focused on preserving funded status gains and employing prudent asset-liability management.” We couldn’t agree more. We, at Ryan ALM, believe that the primary goal in managing a DB pension plan is to secure the promised benefits at a reasonable cost and with prudent risk. It is NOT a return objective. Having achieved this level of funding allows plan sponsors and their advisors to significantly de-risk their plans through Cash Flow Matching (CFM), which is a superior duration strategy, as each month of the assignment is duration matched.

Don’t Engage in a Cash Sweep – Dividends Matter!

By: Russ Kamp, CEO, Ryan ALM, Inc.

We’ve already shared with you the importance of dividends to the long-term return of the S&P 500 by referencing studies conducted by Guinness Global Investors.

According to the Guinness study, which was last updated as of April 2020, the contribution to return of the S&P 500 from dividends and dividends reinvested for 10-year periods since 1940 was a robust 47% down insignificantly from 48% a decade ago. Extending the measurement period to 20 years from 1940 forward highlights an incredible 57% contribution to the total return of the S&P 500 from dividends. Importantly, this study is on the entirety of the S&P 500, not just those companies that pay dividends. If the universe only included dividend payers, this analysis would reveal strikingly greater contributions since roughly 100 S&P 500 companies are not currently paying a dividend.

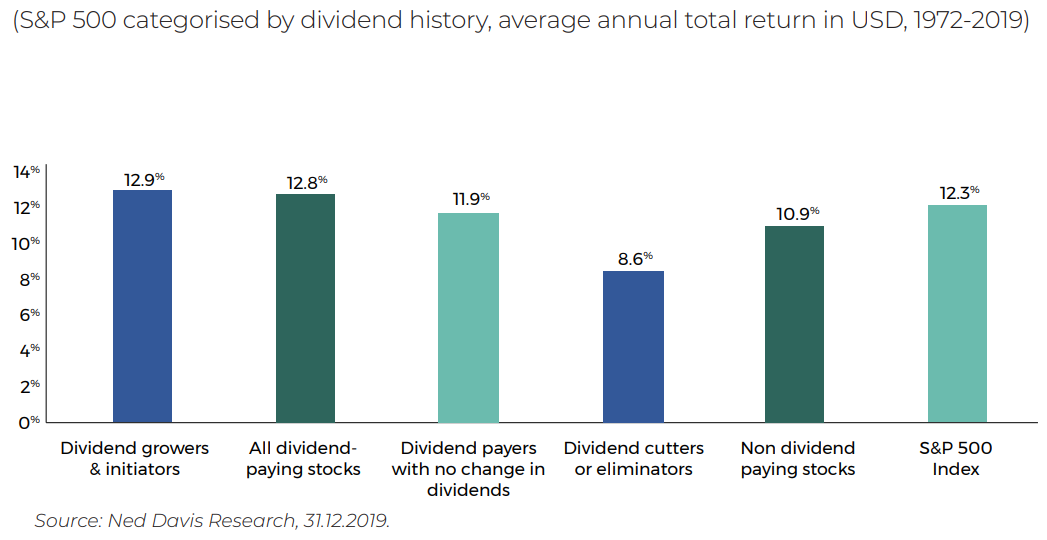
As if this study isn’t enough to convince you of the importance of dividends to the long-term return of stocks, Glen Eagle Trading put out an email today that referenced a recent Wall Street Journal article, titled “Why Investors Are Right to Love Dividends”. The article highlighted the fact that recent studies show S&P 500 dividend-paying stocks returned 9.2% annually over the past 50 years, which is more than double the 4.3% return of non-dividend payers, with lower volatility. Then there is this study by Ned Davis which broke down the contribution of dividends for the 47-years ending December 21, 2019.

Once again, it becomes abundantly clear why investing in companies paying dividends is a terrific long-term strategy. It also begs the question, why do many plan sponsors and their advisors regularly “sweep” income from their equity managers to meet ongoing benefits and expenses? In doing so, instead of structuring the pension plan to have a liquidity bucket to meet those obligations, this activity diminishes the potential long-term contribution to equities from dividends. As longer-term returns are reduced, greater contributions are needed to make up the shortfall compounding the problem.

Please don’t sweep interest and dividend income or capital distributions for that matter, establish an asset allocation that has a dedicated liquidity bucket that uses cash flow matching to secure and fund ongoing benefits and expenses. The remainder of the assets not deployed in the liquidity bucket go into a growth bucket that benefits from the passage of time.

Segal: Benefits of Pension De-Risking

By: Russ Kamp, CEO, Ryan ALM, Inc.

Jason Russell and Seth Almaliah, Segal, have co-authored an article titled, “Benefits of Pension De-Risking and Why Now is the Right Time”. Yes! We, at Ryan ALM, agree that there are significant benefits to de-risking a pension plan and we absolutely agree that NOW is the right time to engage in that activity.

In their article they mention that the current interest rate environment is providing opportunities to de-risk that plan sponsors haven’t seen in more than two decades. In addition to the current rate environment, they reflect on the fact that many pension plans are now “mature” defining that stage as a point where the number of retired lives and terminated vested participants is greater than the active population. They also equate mature plans to one’s that have negative cash flow, where benefits and expenses eclipse contributions. In a negative cash flow environment, market corrections can be more painful as assets must be sold to meet ongoing payments locking in losses, as a result.

They continue by referencing four “risk reducing” strategies, including: 1) reducing Investment Volatility, 2) liability immunization, 3) short-term, cash flow matching, and 4) pension risk transfers. Not surprisingly, we have some thoughts about each.

  1. Reducing investment volatility – Segal suggests in this strategy that plan sponsors simply reduce risk by just shifting assets to “high-quality” fixed income. Yes, the annual standard deviation of an investment grade bond portfolio with a duration similar to that of the BB Aggregate would have a lower volatility than equities, but it continues to have great uncertainty since bond performance is driven primarily by interest rates. Who knows where rates are going in this environment?
  2. Liability Immunization – The article mentions that some plan sponsors are taking advantage of the higher rate environment by “immunizing” a portion of the plan’s liabilities. They describe the process as a dedicated portfolio of high-quality bonds matched to cover a portion of the projected benefits. They mentioned that this strategy tends to be long-term in nature. They also mention that because it is “longer-term” it carries more default risk. Finally, they mentioned that this strategy may lose some appeal because of the inverted yield curve presently observed. Let me comment: 1) Immunization is neither a long-term strategy or a short-term strategy. The percentage of liabilities “covered” is a function of multiple factors, 2) yes, immunization or cash flow matching’s one concern when using corporate bonds is default risk. According to S&P, the default rate for IG bonds is 0.18% for the last 40-years, and 3) bond math tells us that the longer the maturity and the higher the yield, the lower the cost. Depending on the length of the assignment, the current inverted yield curve would not provide a constraint on this process. Finally, CFM is dependent on the actuary’s forecasts of contributions, benefits, and expenses. Any change in those forecasts must be reflected in the portfolio. As such, CFM is a dynamic process.
  3. Short-term, cash flow matching – CFM is the same as immunization, whether short-term or not. Yes, it is very popular strategy for multiemployer plans that received Special Financial Assistance (SFA) under ARPA for obvious reasons. It is a strategy that SECURES the promised benefits at both low cost and with prudent risk. It maximizes the benefit coverage period with the least uncertainty.
  4. Pension Risk Transfers (PRT) – In a PRT, the plan sponsor transfers a portion of the liabilities, if not all of them, to an insurance company. This is the ultimate risk reduction strategy for the plan sponsor, but is it best for the participant? They do point out that reducing a portion of the liabilities will also reduce the PBGC premiums. But, does it impact the union’s ability to retain and attract their workers?

We believe that every DB pension plan should engage in CFM. The benefits are impressive from dramatically improving liquidity, to buying time for the growth (non-CFM bonds) assets, to eliminating interest rate risk for those assets engage in CFM, to helping to stabilize contributions and more. Focusing 100% of the assets on a performance objective only guarantees volatility. It is time to adopt a new strategy before markets once again behave badly. Don’t waste this wonderful rate environment.

Thank you, Segal, for your thoughtful piece.

There Is No “Standard” Exposure

By: Russ Kamp, CEO, Ryan ALM, Inc.

I recently attended a public pension conference in which the following question was asked: What is the appropriate weighting to emerging markets? There may be an average exposure that results from a review of all public fund data, but there is NO such thing as an appropriate or standard weight. Given that every defined benefit plan has its own unique liabilities, funded status, ability to contribute, etc., how could there be a standard exposure to any asset class, let alone emerging markets.

I’m sure that this question originates through the belief that the pension objective is to achieve a return on asset (ROA) assumption. That there is some magic combination of assets and weightings that will enable the pension plan to achieve the return target. However, as regular readers of this blog know, we, at Ryan ALM, think that the primary objective when managing a DB pension plan is NOT a return objective but it is to SECURE the promised benefits at a reasonable cost and with prudent risk.

Pursuing a performance (return) objective guarantees volatility, as the annual standard deviation for a pension plan is roughly 12%-15%, but not success in meeting the funding objective. Refocusing on the liabilities secures, through cash flow matching, the monthly promises from the first month out as far as the allocation will cover. Through this process the necessary liquidity is provided each month, while also extending the investing horizon for the remainder of the assets that are no longer needed as a source of liquidity. We refer to these residual assets as the alpha or growth assets, that now can grow unencumbered.

This growth bucket can be invested almost anyway that you want. You can decide to just buy the S&P 500 index at low fees or construct a more intricate asset allocation with exposures and weightings of your choice. There is no one size fits all solution. We do suggest that the better the funded ratio/status of your plan, the greater the allocation to the liquidity assets. If your plan is less well funded today, start with a more modest CFM portfolio, and expand it as funding levels improve. In any case, you are bringing an element of certainty to what has been historically a very uncertain process.

So, please remember that every DB plan is unique. Don’t let anyone tell you that your fund needs to have X% in asset class A or Y% in asset class B. Securing the benefits should be the most important decision. How you build the alpha portfolio will be a function of so many other factors related specifically to your plan.