ARPA Update as of October 4, 2024

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

Welcome to October. It is always a beautiful time of year in New Jersey.

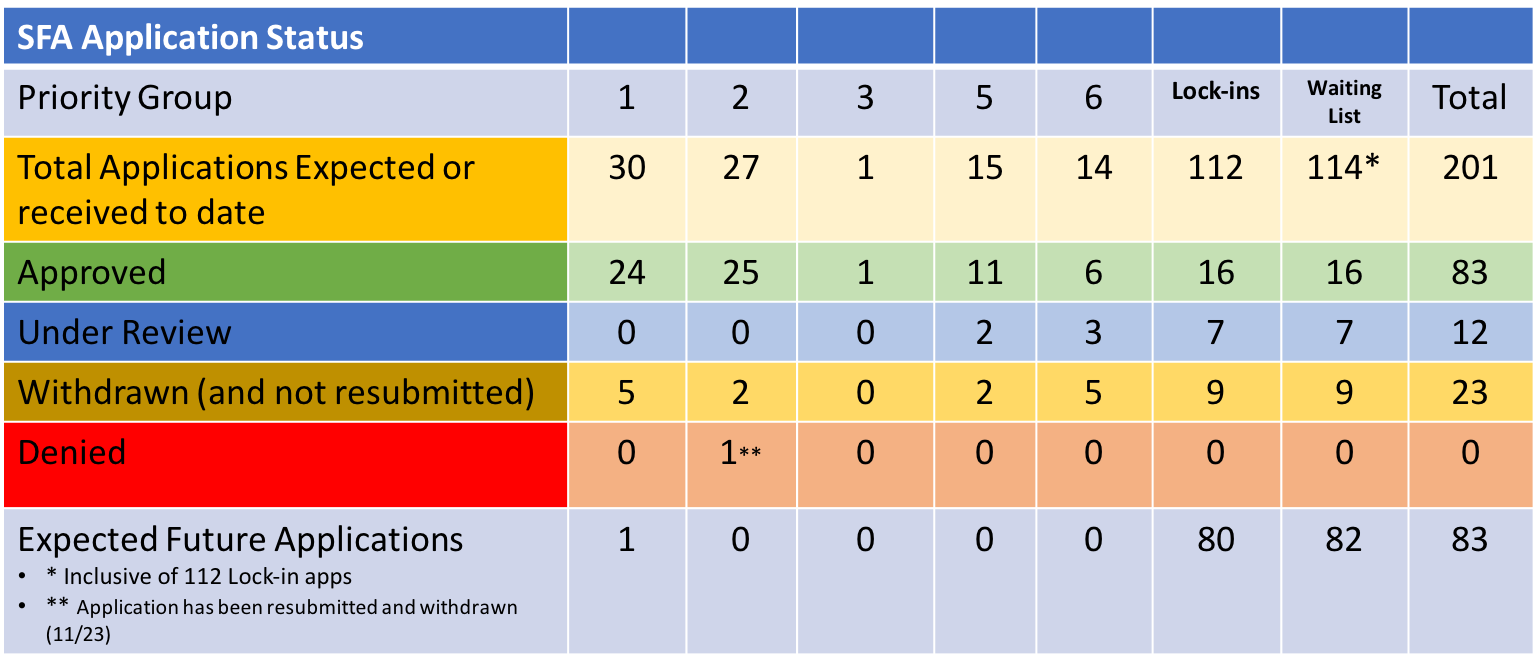
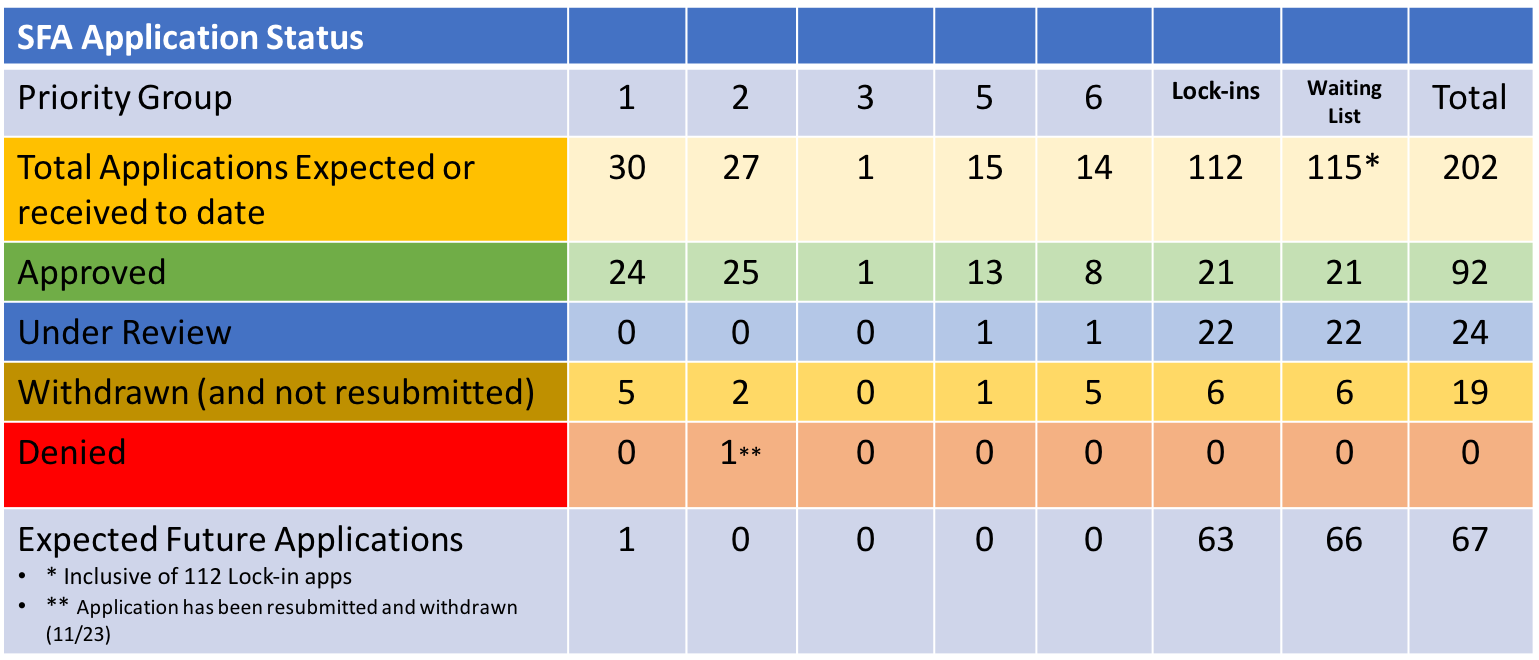
With regard to the PBGC’s implementation of the ARPA legislation, there was some activity last week. After a short pause in accepting applications, the PBGC accepted two initial applications from two non-Priority Group members. Cement Masons Local No. 524 Pension Plan and the Roofers Local No. 75 Pension Plan, both Ohio-based, filed applications seeking $11.3 million combined in SFA for 486 plan participants. As a reminder, the PBGC has 120 days to act on those applications.

In addition to the 2 new applications, the PBGC recouped another $1.2 million in SFA overpayments due to census errors. This brings the repayment to of excess SFA to $144.1 million for 19 plans. The recovery of SFA amounts to 0.37% of the grant monies awarded. In other news, there were no applications approved, denied or withdrawn during the last week. There also were no funds seeking to be added to the waitlist.

As the chart above highlights, there are 110 funds yet to have applications approved. US Treasury yields are once again on the rise after a dramatic retreat as bond investors plowed into bonds anticipating very aggressive rate cuts by the Federal Reserve. Higher rates reduce the PV cost of those FV payments of benefits and expenses. A defeasement strategy significantly reduces interest rate risk as FVs are not interest sensitive. As we’ve discussed on many occasions, using a cash flow matching strategy to meet those benefits and expenses reduces the uncertainty associated with a traditional benchmark relative fixed income product. We are happy to discuss this subject in far greater detail.

What Will Their Performance Be In About 11 years?

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

How comforting would it be for both plan sponsors and their advisors to know how a particular strategy is going to perform over some defined period of time? I would think that having that knowledge would be quite comforting, at least as a “core” holding. Do you think that a core fixed income manager running a relative return strategy versus the Bloomberg Barclays Aggregate Index could tell you how that portfolio will perform in the next 10 1/2 years? No. Ryan ALM can with a very high degree of certainty. How’s that? Well, cash flow matching (CFM) of asset cash flows to liability cash flows locks in that relationship on the day that the portfolio is constructed. Ryan ALM views risk as the uncertainty of achieving the objective. If the true pension objective is to fund benefits and expenses in a cost-efficient manner with prudent risk, then our CFM model will be the lowest risk portfolio.

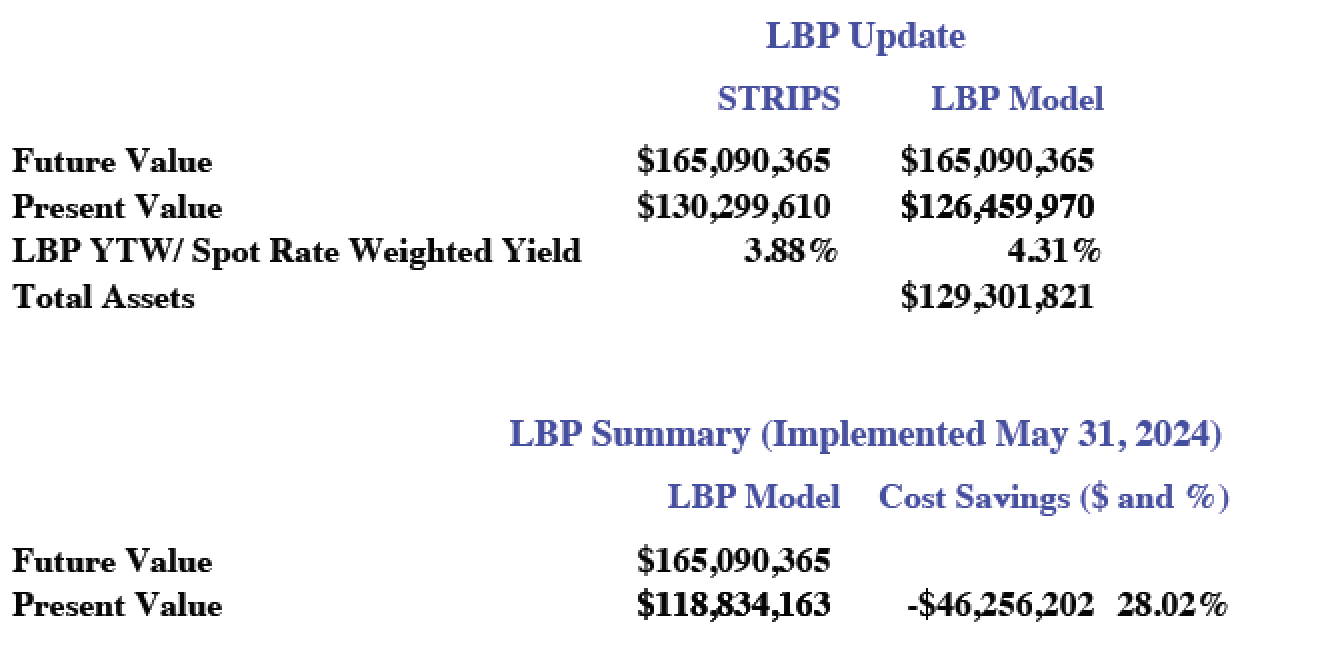
We were awarded a CFM assignment earlier this year. Our task was/is to defease the future grant payments for this foundation. On the day the portfolio was built, we were able to defease $165.1 million in FV grant payments for only $118.8 million, locking in savings (difference between FV and PV of the liability cash flows) of $46.3 million equal to 28.0% of those future grant payments. That’s fairly substantial. The YTM on that day was 5.19% and the duration was 5.92 years.

Earlier this week, we provided an update for the client through our monthly reporting. The current Liability Beta Portfolio (the name that we’ve given to our CFM optimization process) has the same FV of grant payments. On a market value basis, the portfolio is now worth $129 million, and the PV of those future grant payments is $126 million. But despite the change in market value due to falling interest rates, the cost savings are still -$46.3 million. The YTM has fallen to 4.31%, but that doesn’t change the initial relationship of asset cash flows to liability cash flows. That is the beauty of CFM.

Now, let me ask you, do you think that a core fixed income manager running a relative return portfolio can lay claim to the same facts? Absolutely, not! They may have benefitted in the most recent short run due to falling interest rates, but that would clearly depend on multiple decisions/factors, including the duration of the portfolio, changes in credit spreads, the shape of the yield curve, the allocation among corporates, Treasuries, agencies, and other bonds, etc. Let’s not discount the direction of future interest rate movements and the impact those changes may have on a bond strategy. In reality, the core fixed income manager has no idea how that portfolio will perform between now and March 31, 2035.

Furthermore, will they provide the necessary liquidity to meet those grant payments or benefits and expenses, if it were a DB pension? Not likely. With a yield to maturity of 4.31% and a market value of assets of $129.3 million, they will produce income of roughly $5.57 million/year. The first year’s grant payments are forecast to be $9.7 million. Our portfolio is designed to meet every $ of that grant payment. The relative return manager will be forced to liquidate a portion of their portfolio in order to meet all of the payments. What if rates have risen at that point. Forcing liquidity in that environment will result in locking in a loss. That’s not comforting.

CFM portfolios provide the client with the certainty of cash flows when they are needed. There is no forced selling, unlike the relative return manager that might be forced to sell in a market that isn’t conducive to trading. Furthermore, a CFM mandate locks in the cost savings on day 1. The assets not used to meet those FV payments, can now be managed more aggressively since they benefit from more time and aren’t going to be used to meet liability cash flows.

Asset allocation strategies should be adapted from a single basket approach to one that uses two baskets – liquidity and growth. The liquidity bucket will house a defeased bond portfolio to meet all the cash flow requirements and the remainder of the assets will migrate into the growth bucket where they can now grow unencumbered. You’ll know on day 1 how the CFM portfolio is going to perform. Now all you have to worry about are those growth assets, but you’ll have plenty of time to deal with any challenges presented.

Defined Benefit Pension Plan: “Absolute Truths”

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

The four senior team members at Ryan ALM, Inc. have collectively more than 160 years of pension/investment experience. We’ve lived through an incredible array of markets during our tenures. We have also witnessed many attempts on the part of Pension America to try various strategies (schemes) to meet the promises that have been made to the pension plan participants. Regrettably, defined benefit (DB) pension plans continue to be tossed aside by corporate America in favor of defined contribution (DC) plans. Both public and multiemployer plan sponsors would be wise to adopt a strategy that seeks more certainty in order to protect and preserve these critically important retirement vehicles before they are subject to a similar fate.

We’ve compiled a list of DB pension “Absolute Truths” that we believe return the management of pension plans back to its roots when “SECURING the promised benefits at a reasonable cost and with prudent risk” was the primary objective. The dramatic move away from the securing of benefits to today’s arms race focus on the return on asset assumption (ROA) has eliminated any notion of certainty in favor of far greater variability in likely outcomes.

Here are the Ryan ALM DB Truths:

  • Defined Benefit (DB) plans are the best retirement vehicles!
  • They exist to fulfill a financial promise that has been made to the plan participant upon retirement.
  • The primary objective in managing a DB plan is to SECURE the promised benefits at a reasonable cost and with prudent risk.
  • The promised benefit payments are liabilities of the pension plan sponsor.
  • Liabilities need to be measured, monitored, and managed more than just once per year.
  • Liabilities are future value (FV) obligations – a $1,000 monthly benefit is $1,000 no matter what interest rates do. As a result, they are not interest rate sensitive.
  • Plan assets (stocks, bonds, real estate, etc.) are Present Value (PV) or market value (MV) calculations. We do not know the FV of assets except for bonds cash flows (interest and principal at maturity)
  • In order to measure and monitor the funded status, liabilities need to be converted from FV to PV – a Custom Liability Index (CLI) is absolutely needed.
  • A discount rate is used to create a PV for liabilities – ROA (publics), ASC 715 (corps), STRIPS, etc.
  • Liabilities are bond-like in nature. The PV of future liabilities rises and falls with changes in the discount rate (interest rates).
  • The nearly 40-year decline in US interest rates beginning in 1982 crushed pension funding, as the growth rate for future liabilities far exceeded the growth rate of the PV of assets.
  • The allocation of plan assets should be separated into two buckets – Liquidity (beta) and Growth (alpha).
  • The liquidity assets should consist of a bond portfolio that matches (defeases) asset cash flows with the plan’s liability cash flows (benefits and expenses (B&E)).
  • This task is best accomplished through a Cash Flow Matching (CFM) investment process.
  • The liquidity assets should be used to meet B&E chronologically buying time for the alpha assets to grow unencumbered in their quest to meet future liabilities.
  • The Growth assets will consist of all non-bonds, which can now grow unencumbered, as they are no longer a source of liquidity. Growth assets will fund future liabilities.
  • The Return on asset (ROA) assumption should be a calculated # derived through an Asset Exhaustion Test (AET)
  • The pension plan’s asset allocation should be responsive to the plan’s funded status and not the ROA.
  • As the funded status improves, port alpha (profits) from the Growth portfolio into the Liquidity bucket (de-risk) extending the cash flow matching assignment and securing more promises.
  • This de-risking ensures that plans don’t continue to ride the asset allocation rollercoaster leading to volatile contribution costs.
  • DB plans are a great recruiting and retention tool for managing a sponsor’s labor force.
  • DB plans need to be protected and preserved, as asking untrained individuals to fund, manage, and then disburse a “benefit” through a Defined Contribution plan is poor policy.
  • Unfortunately, doing the same thing over and over and… is not working. A return to pension basics is critical.

You’ve made a promise: measure it – monitor it – manage it – and SECURE it…   

Get off the pension funding rollercoaster – sleep well!

Must We Continue to Just Shift Deck Chairs on the Titanic?

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

You may not have been following Ryan ALM’s blog through the many years that I have been producing posts in which I’ve touched on this subject. We at Ryan ALM continue to question the logic of focusing on the return on asset assumption (ROA) as the pension plan’s primary objective.  We especially challenge the notion that shifting a couple of percent from one asset class to another produces meaningful results for the pension system’s asset allocation and long-term funding success.

Day after day, I read, as I’m sure that you do, articles, blogs, emails, etc. highlighting a new product or twist to an existing one that will just “rock your world” and assist you on the road to achieving the return on asset (ROA) assumption. It doesn’t matter whether your plan is a public fund, multiemployer pension, or a private plan, the continued focus on the ROA as the primary objective for both plan sponsors and their asset consultants is leading everyone down the wrong path. You see, most of the retirement community has been sold a bag of rotten goods claiming that a plan needs to generate the ROA, or it will not meet its funding goals. I say, “Hogwash”! I’d actually like to say something else, but you get my drift.

So, when valuations for most asset classes seem to be stretched, as they do today, where does a pension plan go to allocate their plan’s assets? Well, this “issue” has plan sponsors once again scratching their collective heads and doing the Curly shuffle.  You see, they have once again through the presumed support of their consultants, begun to approach asset allocation as nothing more than rearranging the deck chairs on the Titanic.

Despite tremendous gains from both equity and fixed income bull markets, these plans are willing to “let it ride” instead of altering their approach to possibly reduce risk, stabilize the funded status, and moderate contribution expense. Can you believe that one of the country’s largest public plans has recently decided (I’m sure that it took a long time, too) to roll back fixed income exposure by 2% and equity exposure by 1% from 55% to 54%?  Are you kidding me? Is that truly meaningful or heroic?

Please note that generating a return commensurate with the ROA is not going to guarantee success. Furthermore, since most public pension plans are currently underfunded on an actuarial basis (let alone one based on market values) meeting this ROA objective will only further exacerbate the UAAL, as the funded status continues to slip. You see, if your plan is 80% funded, and that is the “average” funded ratio based on Milliman’s latest work, you need to outperform your plan’s 7% ROA objective by 1.75% in order to maintain the current funded status. Here’s a simple example as a proof statement:

Assets = $80   Liabilities = $100   ROA = 7.00%   Asset growth = $5.60   Liability growth = $7.00

In order for asset growth = $7.00, assets would need a 8.75% ROA

Given that reality, these plans don’t need the status quo approach that has been tried for decades. Real pension reform must be implemented before these plans are no longer sustainable, despite the claim that they are perpetual.  As an industry, we have an obligation to ensure the promised benefits are there when needed. Doing the same old, same old places our ability to meet this responsibility in jeopardy. If valuations are truly stretched, don’t leave your allocations basically stagnant. Take the opportunity to try something truly unique.

It is time to approach asset allocation with a renewed focus. Instead of having all of your plan’s assets tied to achieving the ROA, divide them into two buckets – liquidity and growth. The liquidity bucket will utilize a cash flow matching (CFM) strategy to ensure that monthly payments of benefits and expenses (B+E) are available, as needed, chronologically. The asset cash flows from the CFM strategy will be carefully matched against the liability cash flows of B+E providing the necessary liquidity. This provides the growth bucket (all non-bond assets) with an extended investing horizon, and we all know how important a long time horizon is for investing. Importantly, the growth assets will be used down the road to meet future pension liabilities and not in the short-term to meet liquidity needs. The practice of a cash sweep to meet ongoing liquidity has negatively impacted long-term returns for many pension systems.  Let bonds fund B+E so the growth assets can grow unencumbered.

Focusing on products and minor asset class shifts will waste a lot of your time and not produce the results that our pension plans need. Ensuring the appropriate funding to meet the promises given to the plan participant takes real reform. It starts with eliminating the single focus on the ROA. Pension plan liabilities need to be invited to the asset allocation dance, since paying a benefit is the only reason that the fund exists in the first place.

Liquidity Management Needs to be a Focus!

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

I’ve produced several posts addressing the important issue of liquidity for pension plans. You may recall my 8/14/24 post titled “A Liquidity Crunch?” that referenced issues within private equity as a result of the lack of distributions or the March 28, 2024 post titled, “The Importance of Liquidity”, which referred to a terrific article penned by Jack Boyce. There have been several others, but the issue isn’t being addressed with the appropriate urgency, so I’ll continue to elevate our concerns. As we’ve stated many times, the only reason that a pension plan exists is because of promised benefits that have been made to the plan participant. It is that promise that must be met each and every month upon retirement. There are costs associated with meeting this commitment, so both the benefit and those expenses must be funded effectively and efficiently. At present, they are not!

Is the above picture representative of the available liquidity in your plan? Has the significant movement into alternatives reduced for you the number of investment strategies within your asset allocation framework that can provide liquidity when called upon? Is the changing shape (steepening) of the US Treasury yield curve reducing the return available on cash thus making the holding of cash reserves less palatable? Has your practice of doing a “cash sweep” of dividends, interest, and capital distributions each and every month created headaches for you?

We’d like to speak with you about a strategy – cash flow matching (CFM) – that can dramatically improve your liquidity, while enhancing the return associated with “cash reserves” thus reducing the potential negative impact on your pursuit of the required ROA. Wouldn’t you like liquidity to be abundant similar to the picture below? How comforting would it be to know that each and every month your plan has the necessary asset cashflows to meet the liability cashflows of benefits and expenses without having to liquidate assets that may be transacted at less than opportune times?

Cash flow matching (CFM) has been around for decades. CFM is often how insurance companies and lottery systems meet their future obligations. They take a present value calculation of that future promise and they fund an investment grade bond program that will carefully match asset cash flows with the liability cash flows so that your required liquidity is available monthly. There is no need to do a cash sweep! If you aren’t familiar with Guinness Global Investors (UK), they have determined through their research that the practice of sweeping dividends is harmful (very) to long-term equity returns. In fact, they found that on a 10-year rolling basis going back to 1940, that dividends contributed 47% of the total return. More starkly, on a 20-year rolling basis, that contribution escalates to 57% – wow! The ability to reinvest those dividends into potentially higher returning equities is quite powerful. A CFM strategy will enable your plan to eliminate the ill effects of the cash sweeping practice and allow growth assets to grow unencumbered.

At Ryan ALM, Inc., liquidity management has always been a focus of ours since all we do is provide asset cash flows through our CFM product to meet those pesky monthly obligations. Let us help you craft a “liquidity policy” that makes sense. Furthermore, through our Custom Liability Index (CLI) we will map for you the needed liquidity as far into the future as you want to fund. Lastly, we’ll construct an investment grade bond portfolio that will ensure the necessary asset cash flows are available monthly (barring any defaults, which are incredibly rare within the IG universe). This portfolio should be the core holding within your plan. All other assets now have seen the investing horizon extended since they are no longer a source of liquidity. As you know, time is a critical variable in the success or failure of an investment program. The more time that one has to invest, the higher the probability of success. We stand ready to assist you.

POB Discussions Back on the Table?

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

Cash Flow Matching (CFM) has enjoyed a renaissance within the pension community since US interest rates began rising in March 2022. The expanded use has not been limited to the beneficiaries of the Special Financial Assistance (SFA) paid through grants as a result of the ARPA pension reform being passed in March 2021. As a reminder, SFA proceeds are to be used exclusively to fund benefits (and expenses) as far into the future as the allocation will go. Protecting the precious grant proceeds has led to multiemployer pension plan sponsors and their advisors mostly using the 67+% in fixed income in defeasement strategies. We, at Ryan ALM, have certainly benefitted from this trend and applaud them for this decision.

In addition to multiemployer plans, both public and private (corporate) pension plans, as well as E&Fs have used CFM to bring an element of cash flow certainty (barring any defaults) to the management of pension assets and the generation of liquidity without being forced to sell assets, which can be very painful during periods of great uncertainty/volatility. These entities join insurance companies and lottery systems that have engaged in CFM activities for decades.

However, there remains a belief that CFM strategies only work during periods of high interest rates. We disagree, since liquidity is needed on a continuous basis. We believe that the use of CFM should be dictated by a number of factors, such as the entities funded status, ability to contribute, and the current fixed income exposure, as well as those liquidity needs. Unfortunately, it appears that interest rates have peaked for the time being. During the Summer of 2023, we were constructing CFM portfolios with a 6+% YTW, capturing most of the average ROA with little volatility. It was a wonderful scenario that unfortunately was not taken advantage of by most sponsors.

Today we are still able to build through our investment grade corporate bond focus portfolios with a YTW around 4.6%. Given the aggressive move down in Treasury yields during the last few months, we think that bond investors have gotten ahead of the Fed at this point as they are discounting about 150 bps of Fed rate cutting. Despite progress in the inflation fight, “sticky” inflation remains in excess of 4%. The US labor market’s unemployment rate is only 4.2%. Wage growth remains above 4%, while initial jobless claims remain at modest levels. Furthermore, the Atlanta Fed’s GDPNow model is forecasting growth for Q3’24 at 3.0% as of September 17, 2024. None of these metrics signal recession to me. How about you?

If you are of the mindset that a 4.6% YTW isn’t providing you with enough return, just think what you’d get from traditional active fixed income portfolios should rates rise once more. Please remember 2022’s -13% total return for the BB Aggregate Index. We frequently write about the need for plan sponsors to think outside the box as it relates to the allocation of assets. We believe that your plan’s assets should be bifurcated into two buckets – liquidity and growth. While the CFM portfolio is providing your plan with the necessary liquidity on a monthly basis, the growth assets can now grow unencumbered. These assets will be used at a later date to meet future benefits and expenses. With a CFM portfolio, plan sponsors can reduce or eliminate the need to do a “cash sweep” that takes away reinvestment in the growth portfolio.

In addition to believing that CFM is still a viable strategy in this environment, the decline in US Treasury yields is once again opening a door for sponsors to consider a pension obligation bond (POB). The 10-year Treasury Note yield is only 3.66% as of 6 pm EST (9/17) or roughly slightly more than half of the average public fund ROA. Estimates place the average funded ratio for public plans at 80%. For a plan striving for 7%, an 8.4% annual return must be created, or the plan’s funded status will continue to deteriorate unless contributions are increased to offset the shortfall. For plans that have funded ratios below the “average” plan, it is imperative that the deficit is closed more quickly. Issuing a POB and using the proceeds to close that gap is a very effective strategy. Corporate plans frequently issue debt and use the proceeds for a number of purposes, including the funding of pension funds.

We’d recommend once again that the proceeds received from a POB be used in a defeasement strategy to meet current liquidity needs and not invested in a traditional asset allocation framework with all of the uncertainty that comes from investing in our capital markets. Why risk potential losses on those assets when a CFM strategy can secure the Retired Lives Liability? It is truly unfortunate that most plan sponsors with underfunded plans didn’t take advantage of the historically low interest rates in 2020 and 2021. Cheap money was available for the taking. It is also unfortunate, that those plans that did take advantage of the rate environment likely invested those proceeds into the existing asset allocation. As you might recall, not only did the BB Aggregate decline -13% in 2022, the S&P 500 fell -18% that year, too.

Managing a DB pension plan comes with a lot of uncertainty. At Ryan ALM, we are trying to bring investment strategies to your attention that will provide certainty of cash flows, which will help stabilize the fund’s contributions and funded status. Don’t be the victim of big shifts in US interest rate policy. Use bonds for their cash flows and secure the promises for which your plan exists in the first place. A defeasment strategy mitigates interest rate risk because the promises (benefits and expenses) are future values, which are not interest rate sensitive. That should be quite comforting. Let us know how we can help you. We stand ready to roll.

Sometimes You Just Have To Shake Your Head

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

CIO Magazine recently published an article chronicling the trials and tribulations of the Dallas Police and Fire and Dallas Employees pension systems. This is not the first time that these systems have been highlighted given the current funded status of both entities, especially the F&P plan currently funded at 39%. The article was based on a “commissioned” study by investment adviser Commerce Street Investment Management, that compiled and in June presented its report to the city’s ad hoc committee on pensions. According to the CIO Magazine article, they were “tasked with assessing the pension funds’ structure and portfolio allocation; reviewing the portfolios’ performance and rate of return; and evaluating the effectiveness of the pension funds’ asset allocation strategy.” That’s quite the task. What did they find?

Well, for one thing, they were comparing the asset allocation strategies of these two plans with similarly sized Texas public fund plans, including three Houston-based systems: the Houston Firefighters’ Relief and Retirement Fund, the Houston Police Officers’ Pension System, and the Houston Municipal Employees Pension System. The practice of identifying “peers” is a very silly concept given that each system’s characteristics, especially the pension liabilities, are as unique as snowflakes. The Dallas plans should have been viewed through a very different lens, one that looked at the current assets relative to the plan’s liabilities.

Unfortunately, they didn’t engage in a review of assets vs. liabilities, but they did perform an asset allocation review that indicated that the two Dallas plans did not have enough private equity which contributed to the significant underfunding. Really? Commerce Street highlighted the fact that “Houston MEPS’ private equity allocation is 28.2%, and the average private equity allocation among the peer group is 21.3%, compared with the DPFP and Dallas ERF’s allocations of 12.2% and 10.5%, respectively.” How has private equity performed during the measurement period? According to the report, Dallas P&F’s plan performed woefully during the 5-years, producing only a 4.8% return, which paled in comparison to peers. Was it really a bad thing that Dallas didn’t have more PE based on the returns that its program produced?

Why would the recommendation be to increase PE when it comes with higher fees, less liquidity, little transparency, and the potential for significant crowding out due to excess migration of assets into the asset class? During the same time that Dallas P&F was producing a 4.8% 5-year PE return, US public equities, as measured by the S&P 500, was producing a 15.7% (ending 12/31/23) or 15.1% 5-year return ending 3/31/24. It seems to me that having less in PE might have been the way to go.

The Commerce report recommended that “to improve the pension funds’ returns and funded ratios, the city should: analyze what top performing peers have done; collaborate to find new investment strategies; improve governance policies and procedures; and provide recommendations for raising the funds’ investment performance.” Well, there you have it. How about returning to pension basics? Dallas is going to have to contribute significantly more in order to close the funding gap. They are not going to be able to create an asset allocation that will dramatically outperform the ROA target. Remember: if a plan is only 50% funded, achieving the ROA will result in the funded status deteriorating even more. They need to beat the ROA target by 100% in order to JUST maintain the deficit.

I’ve railed about pension systems needing to get off the asset allocation rollercoaster to ruin. This recommendation places the Dallas systems on a much more precarious path. So much for bringing some certainty to the management of pension plans. No one wins with this strategy. Not the participant, sponsor, or the taxpayers.

Oh, The Games That Are Played!

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

Managing a defined benefit pension plan should be fairly straightforward. The plan sponsor has made a promise to each participant which is based on time of service, salary, and a multiplier as the primary inputs. The plan sponsor hires an actuary to do the nearly impossible of predicting the future benefits, administrative expenses, salaries, mortality, etc., which for the most part, they do a terrific job. Certainly in the short-term. Since we have a reasonable understanding of what that promise looks like, the objective should be to SECURE that promise at a reasonable cost and with prudent risk. Furthermore, sufficient contributions should be made to lessen the dependence on investment returns, which can be quite unstable.

Yet, our industry has adopted an approach to the allocation of assets that has morphed from focusing on this benefit promise to one designed to generate a target return on assets (ROA). In the process, we have placed these critically important pension funds on a rollercoaster of uncertainty. How many times do we have to ride markets up and down before we finally realize that this approach isn’t generating the desired outcomes? Not only that, it is causing pension systems to contribute more and more to close the funding gap.

Through this focus on only the asset-side of the equation, we’ve introduced “benchmarks” that make little sense. The focus of every consultant’s quarterly performance report should be a comparison of the total assets to total liabilities. When was the last time you saw that? Never? It just doesn’t happen. Instead, we get total fund performance being compared to something like this:

Really?

Question: If each asset class and investment manager beat their respective benchmark, but lost to liability growth, as we witnessed during most of the 2000s: did you win? Of course not! The only metric that matters is how the plan’s assets performed relative to that same plan’s liabilities. It really doesn’t matter how the S&P 500 performed or the US Govt/Credit index, or worse, a peer group. Why should it matter how pension fund XYZ performed when ABC fund has an entirely different work force, funded status, ability (desire) to contribute, and set of liabilities?

It is not wrong to compare one’s equity managers to an S&P or Russell index, but at some point, assets need to know what they are funding (cash flows) and when, which is why it is imperative that a Custom Liability Index (CLI) be constructed for your pension plan. Given the uniqueness of each pension liability stream, no generic index can ever replicate your liabilities.

Another thing that drives me crazy is the practice of using the same asset allocation whether the plan is 60% funded or 90% funded. It seems that if 7% is the return target, then the 7% will determine the allocation of assets and not the funded status. That is just wrong. A plan that is 90% funded has nearly won the game. It is time to take substantial risk out of the asset allocation. For a plan that is 60% funded, secure your liquidity needs in the short-term allowing for a longer investment horizon for the alpha assets that can now grow unencumbered. As the funded status improves continue to remove more risk from the asset allocation.

DB plans are too critically important to continue to inject unnecessary risk and uncertainty into the process of managing that fund. As I’ve written on a number of occasions, bringing certainty to the process allows for everyone involved to sleep better at night. Isn’t it time for you to feel great when you wake up?

ARPA Update as of June 21, 2024

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

I suspect (can only hope) that you woke up yesterday morning just itching to see what news I was going to share as it related to ARPA and the PBGC’s implementation of that critical legislation. Sorry to have disappointed you. Like most everyone else, my day just got away from me.

However, I do have some exciting news to share which might just make up for the disappointment of having to wait one day to get the weekly update. As we’ve been writing, the PBGC was running up against many application review and determination deadlines this month. As a result, they have announced that five funds had their applications approved for Special Financial Assistance (SFA). Terrific!

The five funds are the Retail, Wholesale and Department Store International Union and Industry Pension Plan, the Bakery and Confectionery Union and Industry International Pension Fund, United Food and Commercial Workers Unions and Employers Midwest Pension Plan, GCIU-Employer Retirement Benefit Plan, and the Pacific Coast Shipyards Pension Plan. These funds represent three Priority Group 6 members and two that came through the non-priority waitlist. In total, they will receive nearly $5.8 billion in SFA for just over 200k in plan participants. The Kansas Construction Trades Open End Pension Trust Fund is the last application that needs action in June. There are four that have July deadlines.

There were no new applications submitted to the PBGC, as the portal remains temporarily closed, no applications denied or withdrawn, and none of the plans that have received SFA were forced to return a portion of the proceeds as a result of overpayment identified through a death audit of the plan’s population.

Fortunately, the US interest rate environment and current economic conditions remain favorable for those potential SFA recipients to SECURE promised benefits far into the future without subjecting the grant proceeds to unnecessary risk associated with a non-cash flow matching assignment. Remember that the sequencing of returns is a critical variable when contemplating an asset allocation framework. If your SFA portfolio suffers significant losses in the early years, you negatively impact the coverage period. We’ll be happy to model your plan’s liabilities for free. Don’t hesitate to reach out to us if we can be a resource for you.

Money Managers Recaptured 1/2 the 2022 losses – Should We Be Pleased?

By: Russ Kamp, Managing Director, Ryan ALM, Inc.

P&I has produced an article highlighting the fact that money managers recaptured nearly half of the institutional assets lost (-$9 trillion) in 2022’s market correction. They mention that this was accomplished despite “lingering economic and political uncertainties that kept a lot of money sidelined, including a record $6 trillion parked in money market funds alone.”

According to Pensions & Investments’ 2023 survey of the largest money managers, institutional assets for 411 managers around the globe rose 9.7%, or $4.89 trillion, to $55.23 trillion as of Dec. 31, 2023 for a recovery rate of 52.5%. This recapture of assets was primarily driven by equities, both US (+26%) and global X US (+18%), while bonds were up 5.6% domestically and abroad.

Obviously, it was great to see the “rally” despite wide-spread uncertainty related to the economy, inflation, interest rates, and the labor market. Issues that are still impacting perceptions today. But the real question one should ask has to do with the cyclical nature of markets and what plan sponsors and their advisors can do to mitigate the peaks and valleys. As I reported earlier this week, since 2000, public pension plans have seen a tripling (or more) in contribution expenses as a % of pay, while the funded status of Piscataqua research’s universe of 127 state and local plans has fallen by 25%.

Isn’t it time to get off the asset allocation rollercoaster? The nearly singular focus on return (ROA) by pension plan sponsors has placed pension funding on a ride that does little to guarantee success, but has certainly exacerbated volatility. In the process, contributions into these critically important retirement systems have skyrocketed. Let’s stop thinking that the only way to fund pensions is through outsized market returns. Today’s interest rate environment is providing plan sponsors with a wonderful opportunity to SECURE a portion of their future promises by carefully constructing a defeased bond portfolio that matches and funds asset cash flows of principal and interest with liability cash flows of benefits and expenses.

By doing so, you eliminate the impact of drawdowns, as the assets and liabilities will now move in tandem. How refreshing! Because you are defeasing a future benefit, you are also eliminating interest rate risk, as future values are not interest rate sensitive. Furthermore, you have now created a liquidity profile that is enhanced, as the bond portfolio now pays all of the benefits and expenses chronologically as far into the future as the allocation to the cash flow matching program lasts. Lastly, the growth or alpha assets can now grow unencumbered, as they are no longer a source of funding. The need for a cash sweep has been replaced by cash flow matching with bonds.

Let’s stop having to celebrate recovery rates of roughly 50%, when we can institute investment programs that eliminate these massive and harmful drawdowns. They aren’t helpful to the sustainability of DB pension plans, which we so desperately need if we are to provide a dignified retirement to the American worker. Let’s get back to the fundamentals, as the true objective of a pension is to fund benefits in a cost-efficient manner with prudent risk. It isn’t a performance arms race!