
By: Russ Kamp, CEO, Ryan ALM, Inc.
Nearly five years ago, I produced a post titled “Not a Correlation of 1, But Certainly Strongly Positive”, in which I suggested that a pension plan CIO’s observation that Bitcoin enjoyed “a low correlation to every other asset class” was perhaps misguided. I highlighted the correlation of Bitcoin to domestic equities and more specifically the NASDAQ-100. Well, that correlation has only grown during the last several years, and yesterday’s price action certainly highlighted this fact.
For those believing that Bitcoin was a diversifier that would act to support a pension plan’s asset base during periods of equity market stress, we have yet to see that materialize.
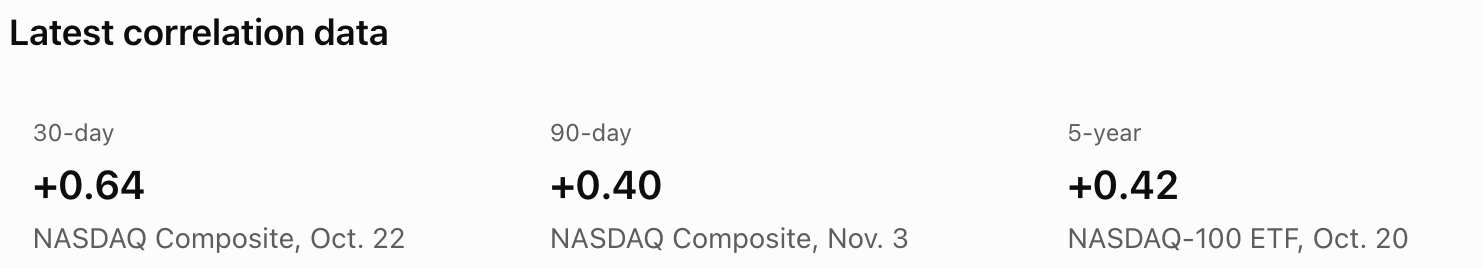
Importantly, the correlations highlighted above do not include yesterday’s price activity when both the NASDAQ-100 (-6.4%) and Bitcoin (-5.8%) received a gut punch. It certainly appears to me that Bitcoin may offer limited downside diversification during periods of significant technology-sector stress. Furthermore, Bitcoin has not proven to be an inflation hedge during this most recent period of higher inflation. In fact, Bitcoin has fallen nearly 40% in value since peaking in October 2025 (>$126k), while inflation continues to push higher.
If Bitcoin is not going to provide an inflation hedge, and it truly doesn’t act like a diversifying asset, what is it that you are getting? Once again, it appears to me that you are just getting more exposure to equities, and specifically technology, at a time when the technology sector is dealing with issues related to the massive investment in everything AI.
Ryan ALM believes, and has promoted the fact, that the only true pension inflation hedge is cash flow matching (CFM) because CFM matches and fully funds the pension plan’s unique actuarial liability projections, which include an inflation factor. No generic asset could ever replicate or correlate accurately with a pension’s unique actuarial projections.
Caveat emptor!

