News For the ROA Chasers

A pension system’s primary objective should be to secure the promised benefits at low cost and prudent risk. Seems obvious, but regrettably that objective has NOT been the primary focus for most public and multiemployer plans for decades now. We can debate the reasons why when the dust settles, but that isn’t going to help us right now.

Unfortunately, the focus for most asset consultants, actuaries, and plan sponsors has been return. As a result, we’ve insured that the funded status and contribution expenses have become incredibly volatile. Instead of securing the promise and winning the game, we’ve decided to play Russian roulette. How has that worked out? Again, it shouldn’t be surprising, but that pursuit of the ROA has failed to stabilize anything pension-related. Many state budgets are being strained, as contributions become a bigger share of annual state budgets and more than 125 multiemployer plans (likely more after this market crash) face insolvency within the next 15 years.

We’ve written a few posts in the last 6 months or so highlighting our concern that equity and equity-like allocations within pension systems for public and multiemployer plans were at levels that were greater than that which we’d witnessed prior to 2007. The excuse was that bond yields were so low that they couldn’t justify having them in their portfolio because they wouldn’t achieve the ROA objective. How’s that worked out? For the record, the S&P 500 through March 31, 2020 has achieved a 4.8% return for 20 years! Meanwhile, the Bloomberg Barclays Aggregate (it will always remain the Lehman Agg. to me) index is up 5.1% during that same 20-year period. Wow, bonds have actually outperformed equities by 0.3% per year for 20-years!

Furthermore, we’ve recently reported that the private equity markets are likely to see massive write-downs of their portfolio companies (33%-50%), as our economy has been shuttered. I have recently seen the results of a business survey conduced in Northern NJ that indicated that 45% of small businesses would not survive three more weeks and that 83% of businesses would be forced to close down if this situation were to extend to the end of June. Think about those jobs and wages lost and the impact on demand for goods and services.

The move to less liquid investments -private equity and debt, real estate, infrastructure, etc. – is also exacerbating the poor performance of pension funds that are forced to sell assets into this weakness in order to make benefit payments. As you know, it didn’t have to be this way. Are we finally going to get off this asset allocation roller coaster that I wrote about earlier this week? Defined contribution plans are NOT retirement vehicles, but if we don’t do a better job of managing DB plans, they will be the only game in town. Our plan participants, retirees, and the US economy will suffer the consequences.
Looking for Something Positive to Write About

I am tired of writing about the problems within our retirement industry, of which there are many. I need something positive to write about, but I’m having difficulty during this chaotic time finding such a topic. Perhaps we can get excited at the prospect that Congress is actually thinking about cobbling together a fourth stimulus proposal following the recent passage of the $2.2 trillion CARES legislation.

There are rumblings that members of the House are preparing to include the Butch Lewis Act (BLA) in the next round of support. The Critical and Declining plans (roughly 125) were already teetering on the brink of insolvency. The stock market’s recent terrible performance will only speed up the time frame to insolvency, while likely pushing many of the multiemployer plans that were deemed to be in “Critical” status into the Critical and Declining bucket. Support for these pension funds is absolutely critical, as nearly 1.4 million American retirees and active plan participants could lose a significant percentage of their earned benefit. Their contribution to our economy, through the monthly benefit payments, is huge. We can’t afford any more revenue and demand shocks to our economy at this time.

While my fingers are crossed that we might see some action to help these struggling plans, I am not holding my breath, as pension reform for multiemployer plans has been on going for years and years. Stay well and stay safe!

Here we Go Again?

The following quote was from my November 5, 2019 blog of the same name. I had just returned from speaking at the IFEBP in San Diego on Enhanced Asset Allocation.

“I certainly don’t know when the next recession might occur, but it will. Do we really want to have these plans sitting with their highest equity exposure when it hits the fan? Shouldn’t we be looking for ways to reduce risk after a long cycle of outperformance?”

Cash Flows NOT Returns

“When it is obvious that the goals cannot be reached, don’t adjust the goals, adjust the action steps.” Confucius

It should be fairly clear at this time that chasing return has created an environment of great uncertainty for Pension America. As Confucius suggests above, if the primary goal is paying the benefits that have been promised, then don’t change that important goal: adjust the action steps. Our industry has chased performance for decades with little success to show for the effort. Isn’t it finally time to adjust the approach?

Building a cash flow matching portfolio that secures those promised benefits would create far less anxiety for all participants involved in pensions. This approach would have worked beautifully during the first quarter when asset values plummeted and liquidity became scarce. Those “return-focused” assets that took it on the chin would now have time to recover, as the cash flow matching portfolio would have provided the necessary liquidity to meet the promised payouts.

Pension Asset Allocation – It’s All Wet!

AP Photo/Mike Groll, File

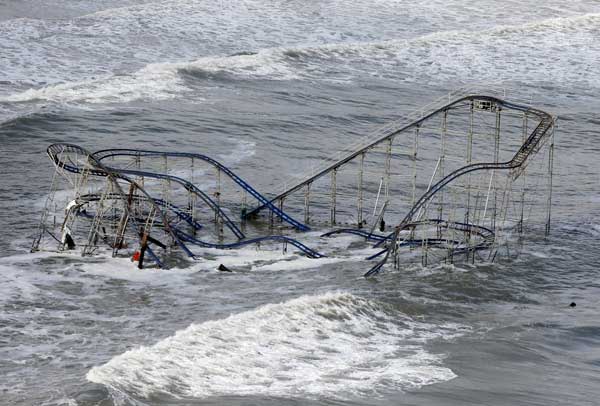
I continue to be amazed by the asset allocation decisions of Pension America. The laser-like focus on the return on asset (ROA) assumption has placed pension plans on the asset allocation roller-coaster to hell! The picture above, which is the Star Jet roller-coaster at Seaside Heights, NJ following Superstorm Sandy, reminds me of the process. Plans ride the good markets up and then down repeating the process with every changing cycle until they get crushed and end up all wet. We need to finally get off this ride before all of Pension America collapses.

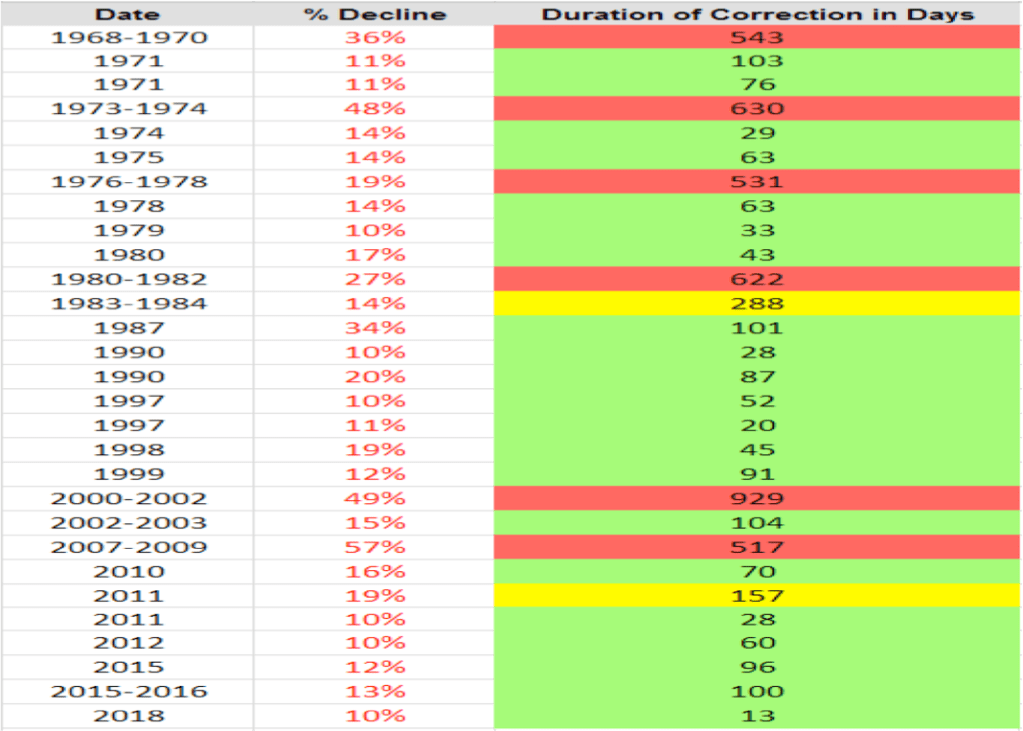
We are currently living through potentially the worst quarter of US equity market performance since 1987’s fourth quarter. I was working on Wall Street at that time – this feels worse! As the chart above highlights, we have had 29 10% or worse corrections since 1968. Three of those corrections were 48% or worse with two of them coming in just the last 2 decades. Remember that when markets fall 50%, they need to rebound by 100% just to get back to even. Regrettably, these market events have brought Pension America to its knees and driven many private sector pensions to the sidelines. The American worker has suffered as a result.

Are we finally going to see pension plans get back to the basics? Will we once again focus our attention on the promises that were made to the participants as the primary objective in managing a pension plan? Markets only trade at fair value accidentally, as they move from over-valued to under-valued. Let’s get away from trying to “guess” where we are in the market cycle and once again establish an asset allocation strategy that has two purposes. The first asset bucket is used to secure the promised benefits through a cash flow driven investing (CDI) approach to match the plan’s Retired Lives liabilities. The remaining assets can now be focused on the pension system’s long-term future liabilities that have been given the benefit of a longer-time frame in which to meet that future liability growth rate. Neither of these asset buckets has the ROA as its objective. Why should you?

Did We Learn Nothing?

The Great Financial Crisis of 2007-2009 highlighted the need for liquidity in pension plans. The lack of liquidity that was witnessed as the result of moving significant assets into private market investments spawned the growth of the secondary markets, while driving asset prices lower as liquidity was forced where natural liquidity didn’t exist. Well, it doesn’t appear as if our industry learned much, if anything, from that crisis. As we’ve reported on several occasions, pension plan allocations to equities and equity-like products are at levels greater than where they were in 2007, alternative investment allocations are up, and guess what, liquidity is once again a challenge. Did we not learn anything?

I spoke before about 600 trustees (2 sessions) at the IFEBP in San Diego in October 2019. My topic was enhanced asset allocation strategies. As an aside, I’ve spoken on that subject at more than one dozen conferences in the last couple of years. I asked the members of the audience how many had been trustees when the GFC took place. I was pleased to see that well more than 50% of the audience had been long-tenured trustees. I also asked them if they remembered what they were thinking about in 2006 and early 2007 as it related to their pension systems. Were they thinking that a stock market crash was around the corner? More importantly, what are you thinking about now (10/19)? I challenged them to start thinking very hard because the bull market at that time was 10+ years old and we don’t know when or why a sell-off will occur, but it will happen – it always does.

I suspect that little was done to protect pension plans from seeing their funded status crushed during this recent crisis. I read with interest this morning an article in Chief Investment Officer magazine by Michael Katz titled, “It’s a Terrible Time for Pensions to Have Weak Liquidity” followed by “Market downturn could force some public pensions to sell assets for a loss.” Here we go again. Did we not learn anything?

The article went on to say that according to S&P, US public pension plans have an average of 1% of their portfolio assets held in cash and short-term investments to pay ongoing expenses, such as benefit payments and administrative costs. Well, that just isn’t good enough. Again, my feeling is that Pension America has been misdirected in focusing on return instead of the primary objective of securing the promised benefits.

Had pension plans adopted the cash flow driven investing (CDI) approach that Ron and I have spoken about for years, there would be no issue today. They would have the cash on hand to meet expenses, no interest rate risk, a longer investing horizon for the alpha assets, and no forced liquidity that would exacerbate the poor performance of their plan. Will this time be different? Will they actually adopt a new strategy or will we once again be discussing this liquidity issue in 2025?

It Would Be A Mistake

I saw a brief article today in the WSJ regarding conversations that are taking place about possibly restricting the ability to short stocks in the U.S. I was extremely fortunate to be leading Invesco’s quant group during the Great Financial Crisis when the U.S. last restricted short selling. We were managing a series of products that utilized shorting techniques, and the restrictions were harmful, as we had about $3 billion in AUM in those strategies. I felt that it was a mistake back then and I continue to believe that it would be a mistake once again.

As a reminder, when selling a stock short, investors are hoping to sell high and then buy lower. Typically, an investor taking a short position does not own the shares prior to the transaction, but borrows the stock through a prime brokerage relationship from another investor. The risk to the short seller is that the security’s price increases, instead of falling, that triggers a loss when the investor must buy it back at a higher cost. There is also a cost to borrow the stock that is to be shorted. Depending on the demand for that issue, the rebate rate can be quite high. An investor needs to have a fairly high conviction that the price fall will exceed the cost to borrow.

I believe, as do many market participants, that the ability to short equities creates a more liquid and efficient market. There are many academic papers that support this claim. ““We shouldn’t be banning short selling,” Securities and Exchange Commission Chairman Jay Clayton said Monday in an interview on CNBC. “You need to be able to be on the short side of the market in order to facilitate ordinary market trading”” (WSJ). James Overdahl, the SEC’s Chief Economist from 2007-2010 was recently quoted as saying “what we found was, on net, it was harmful. There were many unintended consequences”. We have enough to be worried about at this time. Let us not had more hurdles.

Pension Lessons Learned

Ron Ryan and I will be participating in a new webinar series hosted by the Opal Group. The series, titled “Pension Lessons Learned” will have at least 2 episodes. The first session slated for 2pm DST on Wednesday, April 15, is “Protection From Market Disruptions” and the second webinar in the series in slated for April 22nd at the same time, and it will address “Enhanced Asset Allocation” strategies. We hope that you will consider joining us.

As a reminder, the true objective of a pension plan is to secure benefits in a cost-effective manner. Regrettably, Pension America has gotten away from focusing on the primary objective and has instead chased the return on asset (ROA) assumption. This has lead to a dramatic increase in allocations to risk assets, created a poorer liquidity profile, and lead to greater uncertainty in achieving the securing of plan benefits.

We hope that you can join us for both sessions. You can check out the following links for more information on the Opal Group website and the instructions to register for these events.

Website: https://opalgroup.net/conference/pension-lessons-learned-2020/

Registration link: https://zoom.us/webinar/register/6015852510588/WN_PM4XlQuNR9aL7N78aDR4tQ

The financial security for so many Americans is directly correlated to the successful management of these important retirement vehicles. Continuing down the same asset allocation path has failed all of us. We need to take a path that is less traveled and one that might just return us to a route taken when pension plans were first introduced. Tune in – you won’t be disappointed!

In Pursuit of the ROA and the Long-term Implications

We’ve suggested for years that the pursuit of the return on asset (ROA) assumption as the primary goal of pension America was misguided and the latest market events certainly support our point. As plan sponsors and their asset consultants chased the ROA the asset allocation strategies pursued more products that were private in nature – equity, debt, real estate, infrastructure, etc. The hope of more return has likely not been realized and we may soon find out that true valuations have been masked. We certainly understand that pension plan liquidity has been diminished significantly.

With regard to private equity valuations, according to a new report from Investec, “private equity is about to go through a period of violent repricing matched only by the collapse in the global financial crisis: some 50% over the next 3 months!”

In the report from Investec’s Fund Finance team, authors Michael Zornitta and Ian Wiese write “that valuations will fall this month, with major adjustments downward foreseen in June reporting, and that hedging transactions are on the rise as risk management becomes the priority for fund managers. Just one problem: one hedges before the crisis, not after.”

According to the folks at Investec, “almost all managers have shifted their focus from deploying capital to defending assets,” Zornitta and Wiese wrote. Managers are looking into “alternative forms of liquidity to prop up companies, prevent breaches and reduce the possibility of having to call any remaining capital” from investors, they wrote.

DB plans have seen substantial re-pricing for traditional domestic and international equities, and high yield. A repricing of anything near the 50% prediction by Investec will be devastating. We encourage all plans to once again focus on the promise that has been made to your participants (liabilities) to drive asset allocation and invest structure decisions, and to get away from chasing the ROA as if it were the Holy Grail. It is nothing more than a tarnished artifact!

Why Pension Reform Is Absolutely Necessary!

For those of you who are perhaps wondering why I’ve become so passionate about pension reform, there is a social and economic crisis impacting American retirees within the multiemployer universe of Critical and Declining plans (roughly 125) that is about to get even worse, as many of the plans once deemed Critical are likely to have fallen in status with the recent market action.

In 2014, Congress passed legislation (MPRA) that allowed for struggling multiemployer pension plans to file for benefit reductions. To date, there are roughly 15 funds that have been granted permission to “renegotiate” the benefits. These funds have about 75,000 retirees who have seen their benefits reduced. When my friend, John (a retired Teamster) first did his analysis on the impact from these CUTS, there were 43,000 retirees that were in funds that had seen benefit reductions. Their benefit reductions amounted to nearly $34,000,000 / month. What he discovered through his polling and outreach was shocking! Here are just some of the highlights:

95% were not able to work

72% were providing primary care for an ailing loved one

65% were not able to maintain healthcare insurance

60% had lost their home

55% were forced to file for bankruptcy

80% were living benefit check to benefit check

100% of the PBGC maximum benefit payout was inadequate ($12,870 of a retiree with 30-years of work)

50% of the retirees were U.S. service veterans

How could you not be shocked by these numbers? It is wonderful that we have seen action to help American families and businesses negatively impacted by the Coronavirus, but these American workers have been left behind and their fate won’t improve once the virus has subsided. Furthermore, there are 1.3 million American workers/retirees in failing plans that are right behind them in line! Are we truly okay with dooming them to a similar fate as those original 43,000 who have suffered so much? I am not! It bothers me to no end that our industry has failed to protect these pensioners. How is it that so many of us have prospered so greatly from our participation in this industry, yet the people who counted on us have not?