Did you know?

About National Retirement Security Week

National Retirement Security Week is a national effort to raise public awareness about the importance of saving for retirement. National Retirement Security Week is held every year during the third week of October (it is October 21-27 this year). The week provides an opportunity for employees to reflect on their personal retirement goals and determine if they are on target to reach those goals.

National Retirement Security Week commenced in 2006, when Senators Gordon Smith (R-OR) and Kent Conrad (D-ND) introduced the first resolution establishing National Save for Retirement Week. Their goals were to elevate public knowledge about retirement savings and to encourage employees to save and participate in their employer-sponsored retirement plans.

The Senate recently passed Resolution 575 continuing their support of National Retirement Security Week in 2016.  A copy of the resolution can be read here — NRSW Resolution.

Over the years, ICMA-RC has partnered with the National Association of Government Defined Contribution Administrators (NAGDCA) to ensure that the week is a great success. ICMA-RC and NAGDCA remain committed to educating employers and employees about the growing importance of saving for retirement.

Today, plan sponsors and plan participants around the U.S. take part in this exciting week. We invite you to participate and take advantage of the educational resources that we offer on our site to both plan sponsors and participants.

Shame on me for not knowing that there was such a thing as the National Retirement Security Week. We, at KCS, treat every week the same. It is terrific that such a week exists, but how is this information getting into the hands of sponsors and participants? What is being presented that isn’t the same old, same old? What efforts are being put forth to try to preserve and protect defined benefit plans from being terminated and the participants shifted into defined contribution offerings without the skills to fund, manage, and disburse this critical benefit?

Having recently spoken at both the FPPTA and IFEBP, I can assure you that most of the presenters addressing pension plan strategies were once again discussing traditional asset allocation approaches that amount to nothing more than shifting deck chairs on the Titanic. Placing a little more in this asset class versus that one or adding a new asset class with the “promise” of a greater return is not the answer. We need real change in our approach before all of these pension systems no longer exist.
IFEBP Presentation Follow-up

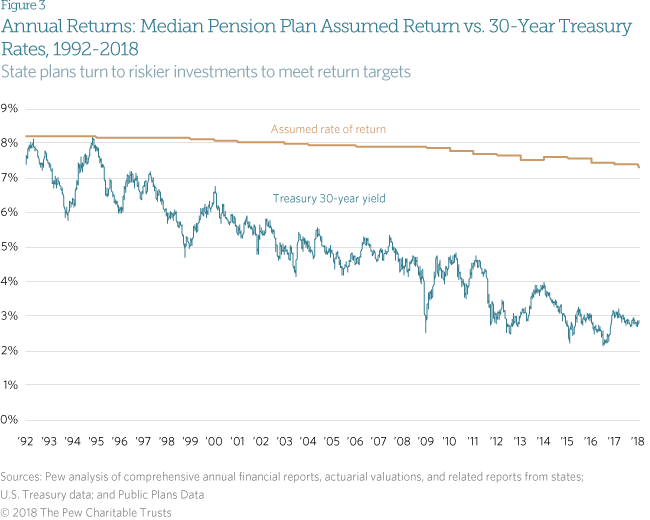
I had the distinct pleasure to once again participate in the IFEBP annual conference. This event had me traveling to New Orleans where it was incredibly warm and humid. There were times during the trip that had me feeling as if I were in a frying pan. Ironically, public pension systems should be feeling the heat at this time, too, as allocations to equity-like products now represent about 70% of the average portfolio which is up more than 30% from just a couple of decades ago.

My presentation was on the “Key Factors in the Long-term Sustainability of Defined Benefit Plans”, and one of the points that I was making is the fact that public pension sponsors and their consultants are injecting a ton more risk into their asset allocation in an attempt to achieve the “Holy Grail”, I mean the return on asset assumption (ROA).

Twenty years ago, states needed only to exceed the yield on a 30-year Treasury bond by 1% in order to meet their investment targets. Currently, the typical state would need to outperform a 30-year Treasury bond by nearly 4.5% to meet its now-lower investment assumption. That reality has forced plans to take on higher levels of investment risk and at a time when U.S. equity markets have enjoyed a historic bull market run.

KCS and Ryan ALM have been encouraging plans to take a different path at this time. We want plans to get their arms around the plan’s specific liabilities and to use that output to drive investment structure and asset allocation decisions. We believe that DB plans need to be sustained, but doing the same old, same old in this environment will prove devastating to funding levels once the next correction occurs.

Sponsors needed to be thinking about this strategy in 2006 and not in 2009 after the market collapsed. Well, are you thinking about de-risking your plan now? If not, why not? It might just be too late in another three to four years.

Does The Rest Of The World Know Something That We Don’t?

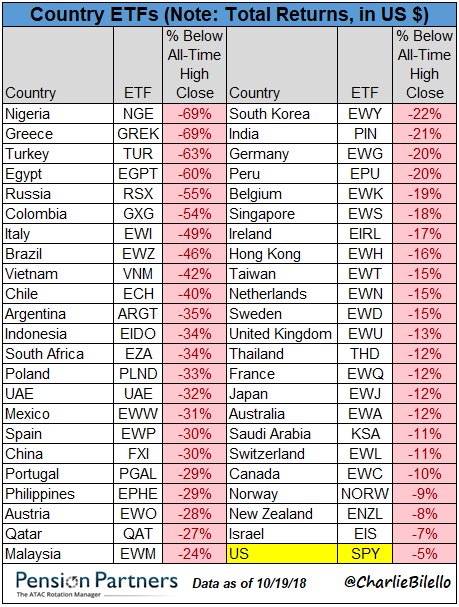
https://pbs.twimg.com/media/Dp9EFgyXcAAtga5.jpg

OUCH! 2018 is certainly not the year to be global in one’s asset allocation, but I certainly have been, and I suspect that many DB plans and DC participants are, too. As the chart above reflects (as of Friday, October 19th), the U.S. is one of only four equity markets to have declined by less than 10% from their all-time high close.  Unfortunately, market action since Friday will have the U.S. equity market getting closer to that -10% mark.

Is the U.S. performance justified at this time? Are we an island in the sea of weak country performance or are we kidding ourselves that the U.S. can continue to produce strong corporate earnings, jobs, economic growth, and increased demand for goods and services despite what might be happening outside our boarders?  I don’t believe that the U.S. is on the cusp of a recession at this time, which is what we normally need in order to see a significant pull-back in equity prices.  However, given the disparate results among the various equity markets, it might just be time to lighten up on the U.S. equity exposure and reallocate some to both developed and emerging markets overseas. What do you think?

Is There A Correlation?

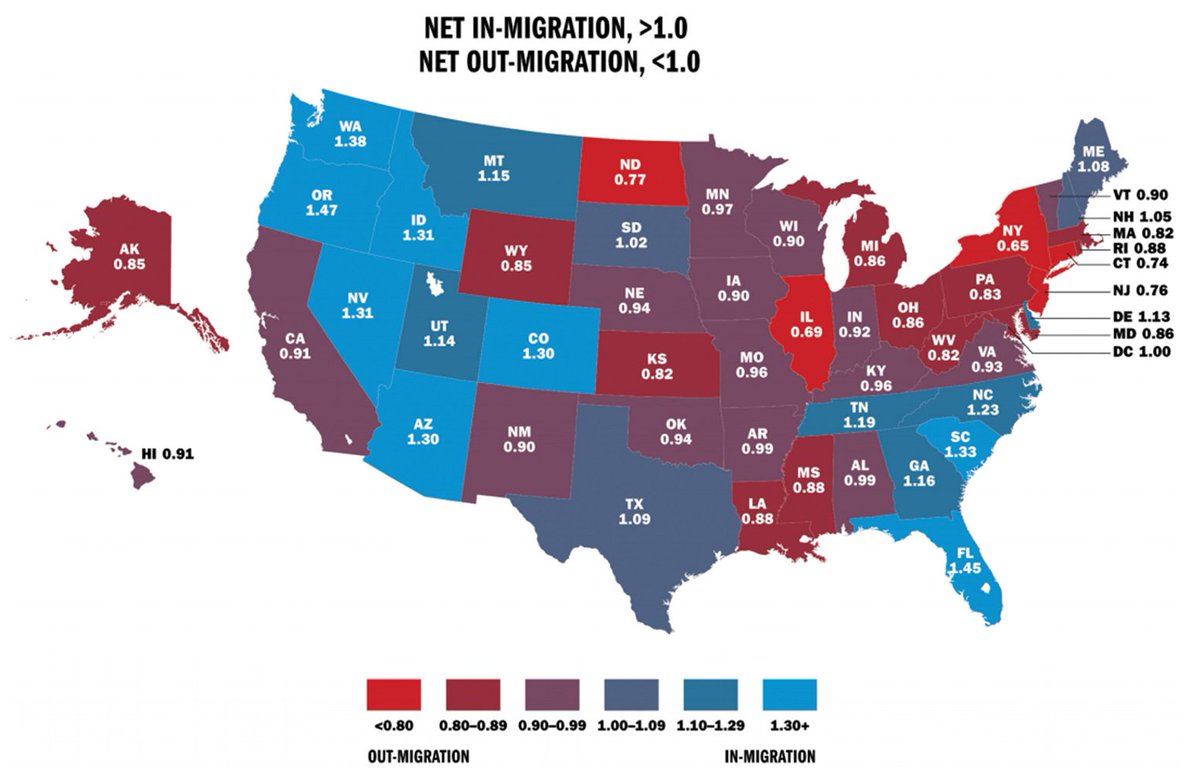
As a lifelong resident of NJ, who appreciates the Garden State for more than its proximity to NYC, I don’t appreciate, but I can understand, the chart below that highlights NJ’s out-migration issue. We aren’t alone, but misery doesn’t like company in this case. There is almost no place like NJ’s beaches, but that alone is clearly not enough to keep people here, as NJ’s taxes, particular property taxes are making life here almost unaffordable. Money Magazine has NJ’s overall tax burden at only #9 among the 50 U.S. states (NY is #1), but the recent Federal tax changes will burden NJ’s residents to a greater extent because of the cap on the SALT deduction.

https://pbs.twimg.com/media/Dp0Zz8EWkAAw862.jpg

Unfortunately, NJ’s plight, and that of many other states, might continue to worsen when one looks at the current pension funding deficits.  NY, IL, CT, NJ, and ND “lead” the way in out-migration, and the pension systems of CT, IL, ND, and NJ all have funding deficits below 70% (actually, CT, IL, and NJ are <60% funded).  New York is the rare exception among the out-migration cohort with a 90%+ funded status. The poor funded status and growing contribution expense will continue to burden the residents of these states.

The economic activity that is produced annually from the benefits received from plan participants is incredibly important to local economies and businesses, as roughly 85% of the net benefit is spent locally. Obviously, these DB plans need to be maintained, but continuing to strive to achieve an inflated ROA is not the answer.  We need to go back to the future and a return to the basics, and manage these systems with an eye toward each plan’s specific liabilities before the markets break once again, which will set these plans and states back even further.


Why the Inconsistency?

Here is an update from the Pension Benefit Guarantee Corporation (PBGC) on the indexing of benefits.

Guarantee Limit: On October 22, 2018, PBGC announced that, as a result of the indexing rules provided in ERISA, the guarantee limits for single-employer plans that fail in 2019 will be 3.46% higher than the limits that applied for 2018.  A table showing the single-employer plan guarantee limits for various ages and payment forms is available on PBGC’s website.  The guarantee limits for multiemployer plans are not indexed and therefore have not changed. (10/22/2018)

Did you notice that participants in multiemployer plans get no increase because their plan limits are not indexed? How is that fair? Who was involved in that negotiation? Guarantee limits for multiemployer plans are roughly 1/5 (<$13,000 annually for a 30-year veteran) of those for participants in single-employer plans already.

This is almost as bad as having two different accounting methodologies for the discounting of plan liabilities (GASB/public and multiemployer plan’s for discounting liabilities and FASB/corporates). The use of GASB to discount liabilities has led to the persistent underfunding of these plans (lowers annual contributions), which has been one of the most critical variables in the funded status (poor) of both multiemployer and public plans.

IF FASB is good enough for Corporate America it should be just as good for public and multiemployer funds. I don’t care that U.S. cities are considered to be perpetual in nature. We’ve seen many examples of U.S. cities struggling financially, which has forced them to terminate DB plans in lieu of DC offerings. Perpetual doesn’t mean sustainable.

It would be wonderful if every DB pension system operated under the same rules and regulations, especially since the average corporation enjoys a more fiscally sound funded status.

Have We Forgotten?

I haven’t seen anything in the business pages today referencing October 19, 1987.  Have we all forgotten the devastation wrought that day? I was working just off Wall Street at the time at 26 Broadway. As you may recall, on Friday, October 16, when all the markets in London were unexpectedly closed due to the Great Storm of 1987 (I didn’t remember this aspect of the event) the DJIA fell 108.35 points (4.6%) to close at 2,246.74 on record volume. It would prove to be the appetizer to the following Monday’s main course.

On October 19, 1987, a day that became known as “Black Monday,” the stock market crashed as the Dow Jones Industrial Average plunged 508 points, or 22.6% in value, its largest single-day percentage drop.  A drop of that magnitude today would be roughly equivalent to a 5,760-point drop. We fret 300 points down days. What was to blame? Historians cite heightened hostilities in the Persian Gulf, fear of higher interest rates, a five-year bull market without a significant correction, and computerized trading that accelerated the selling and fed the frenzy. That’s scary, as all of those elements exist today with one exception; we are now in the midst of a nearly 10-year bull market.

After the Black Monday free fall, the New York Stock Exchange installed what are known as circuit breakers, designed to stop trading when stocks dive too far too fast. It’s a forced timeout to give investors a chance to calm down and interrupt a panic. Today, if stocks dived even 7% (level 1) and 13% (level 2), trading would be suspended for 15 minutes. A decline of 20% would shut down trading for the rest of the day. Let’s hope that we never see this again.


When Is It Not Conservative?

The co-creator of the 401(k), Ted Benna, is raising an issue that I’ve been wondering about for years. Mr. Benna has published a book that’s part history book, part how-to manual, for plan participants.  It covers a wide range of issues, but one in particular is the greater use of target-date-funds (TDFs) as the default offering. He (nor I) is not opposed to their use as a QDIA, but fears that plan participants do not understand the potential risks associated with their use, especially as one nears retirement.

For instance, many of the target-date-fund providers have a TO retirement philosophy, as opposed to a through philosophy (to demise) designed to reduce risk as one nears that last date of employment. However, as is the case in many of the offerings, fixed income exposure is increased and equity exposure decreased. Yet, after a roughly 35-year bull bond market, are fixed income assets really the conservative choice, especially as U.S. interest rates are rising? How short in duration are these exposures and how does the composition of the exposure change among Treasuries, agencies, corporates, etc.? Given the rampant increase in BBB offerings, are these plans protecting their clients from adverse market moves?

The group of near-term retirees is the most vulnerable to a market decline. Just reducing equity exposure in these funds is not necessarily protecting the participants from the potential for dramatic losses. TDFs need to be more tactical in their exposures and the sponsors of these funds need to do a better job of communicating the potential risks associated with the various allocations.

Definitely A Step In The Right Direction

As anyone who reads our blog knows, we believe that the only “true” retirement program is the defined benefit plan. However, given that most of the private sector no longer have access to this benefit, improving defined contribution plans so that they look less like glorified savings accounts and more like retirement vehicles is imperative. To that end, there have been important changes that are helping Americans (those with some disposable income) to save toward the building of a dignified retirement.

One of the most important improvements in plan design is the automatic enrollment feature in which participants have to opt out from participating. As the above chart highlights, those that are placed into a DC plan are far more likely to contribute something than those that have to sign-up. Now, if we could get plans to stop offering loans and premature withdrawals we might just have something that looks more like a retirement account.

Well, Isn’t That Convenient?

Only three (Senator Hatch is retiring) of the sixteen members on Congress’s Joint Select Committee on Solvency of Multiemployer Pension Plans are NOT up for reelection this year. Interestingly, all three are Republican Senators. Isn’t that convenient that this group doesn’t have to face an election in the year in which they’ve been tasked with trying to protect and preserve the pension benefits for more than 1,000,000 American workers. Furthermore, we are lead to believe that little support is forthcoming from the Republicans for the Butch Lewis Act, which they perceive to be a bailout instead of the loan program that is at the core of the proposed legislation. I guess they feel that the delay tactics won’t hurt them during their next election cycle.

As we’ve reported before, little appears to be getting done within the JSC toward finding a bipartisan solution to the evolving multiemployer pension crisis.  That Congress is willing to sacrifice the financial well-being of so many hardworking Americans is beyond me.

Members of the Joint Select Committee on the Solvency of Multiemployer Pension Plans: (Members in bold are not up for reelection)

Senate Democrats

  • Sherrod Brown
  • Joe Manchin
  • Heidi Heitkamp
  • Tina Smith

Senate Republicans

  • Orrin Hatch – retiring
  • Lamar Alexander
  • Rob Portman
  • Mike Crapo

House Democrats

  • Richard Neal
  • Bobby Scott
  • Donald Norcross
  • Debbie Dingell

House Republicans

  • Virginia Foxx
  • Phil Roe
  • Vern Buchanan
  • David Schweikert

Previous attempts at tackling the pension crisis have proven to be disastrous. The Multiemployer Pension Reform Act (MPRA) of 2014 was enacted into law as a means to stabilize failing pension systems. In MPRA, “Congress established a new process for multiemployer pension plans to propose a temporary (who are they kidding?) or permanent reduction of pension benefits if a plan is projected to run out of money before paying all promised benefits (US Treasury Department)”. As of today, the Treasury Department has announced that Local 805’s application to modify (slash?) benefits has been accepted marking the 8th “successful” application since the legislation was enacted.

We find it outrageous that legislation designed to protect pensions and pensioners can call for substantial reductions in benefits for retirees who in most cases are no longer able to make up for the drastic income reduction because of age and/or disability. Given that MPRA might be the course chosen for the remaining 100+ multiemployer plans designated as in critical and declining status, it is imperative that the JSC pass the Butch Lewis Act now! There is no more time for delay.

What I truly fear is that this august body will cobble together a piece of legislation that will demand shared sacrifices (including pension benefit reductions) when the retirees have had nothing to do with the poor state of these plans. Worse, I can see them producing MPRA type legislation that will bring harm to the more than 60% of multiemployer plans that are currently in the green zone.

The U.S. government has the financial means to shore up these critically important plans (CBO estimates the cost at $34 billion) that support so many local economies through the receipt of monthly benefit checks. It is penny wise and pounds foolish to play games, especially since they are likely to have to expand the social safety net once these retirees lose their promised benefits.


The CBO

The Congressional Budget Office (CBO) is a  federal agency within the legislative branch of the U.S. government that provides budget and economic information to Congress. The CBO was created as a nonpartisan agency by the “Congressional Budget and Impoundment Control Act of 1974” (Wikipedia).

There is a consensus among economists that “the CBO has historically issued credible forecasts of the potential impact of both Democratic and Republican legislative proposals.” The mission of the CBO is to produce “independent analyses of budgetary and economic issues to support the Congressional budget process.” Each year, the agency releases reports and cost estimates for proposed legislation, without issuing any policy recommendations. If true, why is the latest estimate of the cost of the Butch Lewis Act not being accepted as a realistic estimate?

Senator Sherrod Brown (D-OH) and Representative Richard Neal (D-MA) have said that the U.S. Congressional Budget Office (CBO) has estimated that the pension reform legislation known as the Butch Lewis Act would cost only $34 billion over the next 10 years, roughly one-third of the $100-billion figure cited in its preliminary analysis earlier this year.

This news should have inspired immediate action on the part of the members of the Joint Select Committee on Solvency of Multiemployer Pension Plans (JSC) to come to some agreement/resolution on legislation to protect these critically important pension plans. Yet, members are questioning the analysis and no legislation has been forthcoming as the time to do something is running out for the JSC.

Are our “leaders” really willing to jeopardize the retirements (and financial freedom) of so many American workers over $34 billion? The Butch Lewis Act is the only proposed legislation that provides loans, protects the PBGC, employers, and plan participants. The issuance of low-interest rate loans provides a 30-year (there may be a provision to begin repayment in year 20) lifeline to these struggling plans. The analysis by Cheiron has determined that 111 of 114 critical and declining plans will not need any PBGC support and can pay back the loan using a more modest return on asset (ROA) assumption of only 6.5%.

Without government help, these plans are doomed to failure and the social and economic toll will be startling. Can we finally stop playing politics and make saving the financial health of these participants the priority?