Use of Callable Bonds in a Cash Flow Matched Portfolio

We recently got a question from one of our client’s consultants regarding the use of Callable Bonds in our cash flow matched bond portfolio. The consultant seemed surprised that we would include them in the universe of acceptable investment-grade bonds to use in an immunized portfolio.  Here is the answer from our head of trading that we provided.

“These day’s it is very difficult to find Corporate bonds that do not have a call feature.  The majority of them have call provisions.  The calls are most often “Make-Whole” call provisions. 

A make–whole call provision is a call provision attached to a bond, whereby the borrower must make a payment to the lender in an amount equal to the net present value of the coupon payments that the lender will forgo if the borrower pays the bonds off early.

The call provisions usually can be exercised until three months before the bond’s maturity date.

Although we do not have much choice these days, buying callable bonds is actually a good strategy when one thinks interest rates will stay relatively stable to maybe going down a little too possibly going up.

This is because an investor receives extra yield at the time of purchase over and above the yield on a non-callable bond plus the investor will receive a premium or prepayment penalty when the bond is called due to the Make-Whole call provision. 

The extra yield from a callable bond acts as a cushion if interest rates rise.   

If interest rates stay flat or go sideways no-harm-no-foul because the investor just reinvests into a new bond at about the same yield that he started with plus the investor received the extra yield at purchase plus the premium at the time of the call.  This means a pickup in income over a non-call bond.

If interest rates go down a little say 25 to 50 basis points then the extra yield received upfront at purchase plus the premium at the time of the call will offset some of the loss in yield due to having to reinvest into a lower-yielding bond.

Finally, the Liability Beta Portfolio cash flow matching strategy is 100% focused on income and not total return.  It is true that a non-callable bond will have better total return performance in a declining interest-rate environment but only if one sells the bond before maturity.  And then if an investor sold her non-call bond before maturity to collect a price gain she would effectively be imposing a self-call because then she would have to reinvest into that lower interest rate environment the same as a callable bond investor would.”
 

These Workers Need Protection

I am extremely proud of the fact that my Mom, Sister, and daughter are all nurses, so it was disturbing to read about the nurses and other hospital workers at St. Clare’s Hospital in Schenectady, N.Y, many of whom have lost their pensions completely. A minority of workers there are “fortunate” to have seen only significant benefit cuts.

St. Clare’s, which was founded by the Catholic Church, suffered financial troubles and as a result it was forced to merge into a larger hospital system in 2008. At the time, employees were told that there pensions would be fine, but 10 years later they were informed that there was no money left to provide the promised benefit. Sinful!

Regrettably, the St. Clare’s of the world are not unique. Because of a loophole, many religious organizations are not covered by a federal guarantee (the PBGC) that protects most other workers’ pensions, so the workers can get left with nothing. By one estimate, more than 1 million workers and retirees from religious organizations lack this federal protection.

The AARP Foundation wants people to be held accountable for this disturbing collapse and they have filed suit on behalf of the more than 600 workers who lost everything against the Roman Catholic Diocese of Albany and the pension fund’s board of trustees. I realize that most Americans don’t have a DB pension plan these days, but for those that were promised one and are counting on it for the bulk of their retirement, this development is shocking. It is unfortunate that religious organizations were not mandated to fund the insurance pool necessary to protect pensions from a collapse.  Incredibly, a Supreme Court decision in 2017 made it easier for religious organizations to opt out of the government sponsored insurance pool.

One can only imagine how many of the roughly 1 million workers at these religious institutions are in plans that are in difficult straits. Although St. Clare’s had the opportunity to opt out, they should still have responsibility to the employees who were promised a benefit. It will be interesting to see what transpires with the AARP Foundation lawsuit and whether it will spur those institutions that have opted out to seek alternative insurance protection. More to come.

ASOP 51 – Are They Prepared?

When I first heard someone mention ASOP 51, I immediately thought that this individual was speaking about Aesop, a slave and storyteller believed to have lived in ancient Greece between 620 and 564 BCE, and one of his many fairy tales.  I suspect that many of our regular readers would accuse me of being the “Boy Who Cried Wolff” for my consistent pronouncements regarding the retirement crisis that continues to unfold.

In September 2017, the Actuarial Standards Board (ASB) adopted a new Actuarial Standard of Practice (ASOP) No. 51 entitled, Assessment and Disclosure of Risk Associated with Measuring Pension Obligations and Determining Pension Plan Contributions (otherwise known as AaDRAwMPOaDPPC or something to that effect). The new ASOP is effective for actuarial work produced on or after November 1, 2018.  It is intended to be used for both private and public pension plans, but not OPEBS.

Importantly, the new ASOP is applicable to actuaries performing funding valuations, pricing valuations, or other, where the actuary is retained to perform a risk assessment that is not part of a funding or pricing valuation. Obviously, risk is in the eye of the beholder, but for this purpose, risk is defined as, “the potential of actual future measurements deviating from expected future measurements resulting from actual future experience deviating from actuarially assumed experience”. And they claim that actuaries aren’t comfortable with small talk at cocktail parties. Phew!

ASOP 51 requires the actuary to identify risks that may reasonably be predicted to significantly affect the pension plan’s future financial condition. Examples include investment risk, asset/liability mismatch risk, interest rate risk, longevity and other demographic risk, and contribution risk. These are all doozies. In addition to identifying the risk, the actuary is asked (required) to assess the identified risk on the plan’s future financial condition. Have you had a conversation with your actuary on how they plan to execute this new requirement?


Investment Risk

Poor investment return performance can significantly affect a public plan’s financial condition most importantly in two ways: computed contribution rate and funded status. For many plans covering general employees, the ratio of assets to payroll is about 5 or so. For plans covering public safety employees, this ratio can be 10 or higher. If a plan with a 7% investment return assumption experienced an annual market value return of –3% (i.e., a 10% investment loss), this would equate to a dollar loss of 50% of payroll for general plans and 100% of payroll for public safety plans. Based upon a reasonable amortization period and payroll growth assumption, this could translate into an increased computed contribution rate of 4.5% of payroll for general plans and 9.0% of payroll for public safety plans. The 2008–2009 Great Recession provides a stark case study for the effect on a plan’s funded status. For many plans that had a 100% fun

The Benefits of Becoming More Liability Aware

For decades, Pension America has focused almost exclusively on cobbling together a portfolio designed to exceed the return on asset assumption (ROA), and for decades many plans have failed.  As a result, the ROA objective continues to fall. As we discussed yesterday, in 2010 the median ROA target for public pensions was 8% and today it has fallen to 7.25%. During that period assets have continued to underperform liability growth insuring that plan funded status would decline despite the tremendous equity bull market, while contribution expenses have grown exponentially. Is there another approach that should be explored? Absolutely!

The objective of a pension system is to SECURE the promised benefits in a cost-efficient manner. Unfortunately, there are only two ways to secure benefits: 1) Insurance annuity buyouts, and 2) Cash flow matching liabilities through a bond portfolio. Many believe that duration matching strategies accomplish this objective but they don’t as they don’t have certain cash flows to meet the future benefit payments.

Importantly, getting ones arms around the promised benefits (plan liabilities) is the only way that a DB plan can de-risk. Through becoming more liability aware a plan sponsor can acquire the following:

  • Greater transparency of the plan’s unique liabilities in multiple dimensions – discount rates based on GASB (ROA), FASB and a risk-free rate (STRIPS)
  • Enhanced knowledge of both cash flow and liquidity requirements
  • Greater accuracy in calculating the TRUE return on assets (ROA) that is required in a test of solvency
  • The ability to establish a cash flow matching bond portfolio created to meet benefit payments
  • Stabilization of both the funded status and contribution expense
  • A much longer investing horizon for the portfolio’s growth assets in order to fund future liabilities
  • Reduced costs
  • Peace of mind that benefits are secure for the next 10 years or so (depends on funded status)
  • Enhanced viability of the pension system

These benefits seem to be pretty significant, yet many plans fail to gain these advantages. Regrettably, most plans only get a once-per-year view of their specific liabilities, which is too infrequent to engage in these important activities. There are many reasons why we’ve witnessed a dramatic reduction in the use of defined benefit plans. Becoming liablity aware will help secure those that remain. Our participants are counting on our industry to take a different path to help them achieve a prosperous retirement.

Going to FPPTA Next Week?

The Florida Public Pension Trustees Association (FPPTA) will be hosting their next Trustee School event from October 6-9 at the Sawgrass Marriott.  My partner, Ron Ryan, will be speaking once again to the trustees and others that will be in attendance. His session:

PUBLIC PENSION ISSUES OF 2019 AND BEYOND

Moderator: Peter Hapgood— FPPTA Education Committee Consultant

Steve Roth— Dahab Associates, Brad Heinrichs— Foster & Foster Consulting Actuaries,
Ron Ryan– Ryan ALM, and Biagio Manieri – PFM Asset Management

Please let us know if you will be there. Ron would welcome the opportunity to visit with you. We hope that you have a great conference.

A Move in the Right Direction

Unlike the “Jeffersons” who were moving on up, public pension systems return on asset assumptions (ROA) are moving on down! Since 2010, 90% of the 129 public pension plans monitored by the National Association of State Retirement Administrators (NASRA) have reduced their annual ROA target. The median objective is now 7.25%, which is down 25 basis points since 2015 and nearly 0.75% since 2010 as reported in a P&I article.

This is a move that is overdue and should be applauded as a step in the right direction, as the lower annual objective will mean that public entities have to contribute more each year to make up for the lower return target. The lower ROA objective should also lead to more conservative asset allocations and investment structures since an 8% objective would naturally lead sponsors and their consultants to invest more heavily in equity and alternative investments.

Given that we are now 10+ years into a bull market recovery for equities and a roughly 35+ year bull market for bonds, the probability of generating an 8% annualized return during the next decade has likely been diminished. Let us hope that the ability to move forward with a more conservative asset allocation will help plans weather potential market turmoil should a weakening global growth environment lead to a recession in the U.S. at some point.

Now, if one wanted to help insulate the portfolio from this potential development, one could always cash flow match the plan’s Retired Lives chronologically from the nearest benefit payment on out (possibly 1-10 years), which will provide the fund with an extended investing horizon for those assets in the portfolio that benefit from the passage of time. This strategy would also help to improve the plan’s liquidity needs, reduce interest rate volatility while stabilizing the funded status and contribution expenses. Intrigued? Please don’t hesitate to reach out to us to learn more.


It’s The Objective That Defines the Asset Allocation

I had the great pleasure of attending (and speaking at) Opal’s Emerging Manager conference in NYC for the last couple of days. I always come away having learned much more than I knew before the day started. However, in the last panel of the conference, the moderator, an influential plan sponsor, who I know and really like, asked the members of his panel why pension plans were later to the game investing in hedge funds than E&Fs and HNW individuals.  The panel highlighted a number of potential reasons, but I think that the question was phrased inappropriately.

I would have asked the question are hedge funds more or less appropriate investments for pension plans than either E&F or HNW individuals? My response would have been that the fund’s objective(s) should be what drives asset allocation and individual product exposures. My feeling is that E&F and HNW individuals have annual positive spending policies that dictate more of an absolute return orientation and that pension plans have a relative objective – that being their specific liabilities (benefit promises). Thus, E&Fs have every reason to want and need to produce a consistently positive return, but pension funds need to outperform liability growth, whether that leads to a positive return or not.

By focusing on the return on asset assumption and not liability growth, pension systems have severely underperformed liability growth since 12/31/99 by an astounding 170% (according to Ryan ALM). Of course, this period coincided with two major market declines, but the negative impact of these bear markets would have been mitigated had assets and liabilities been more in lock-step with one another. Focusing exclusively on the ROA has injected significantly more volatility into the asset allocations for pension plans than how they were managed decades ago. I’m afraid that the singular focus on the return objective is setting these plans up for significant underperformance and rapidly escalating contribution costs should we encounter another bear market in the not-too-distant-future.

Investing in hedge funds won’t protect the asset side of the equation from underperforming plan liabilities in such an environment. They might help E&Fs and INW individuals, but then again, they have a very different annual objective.


What Am I Missing?

CIO Magazine has published an article that cites the Congressional Budget Office (CBO) indicating that the proposed pension legislation “The Rehabilitation for Multiemployer Pensions Act of 2019” (H.R. 397) won’t be enough to protect and preserve all of the plans. In fact, a CBO “study projected that approximately one-quarter of the pension plans that would be eligible for loans through the bill would become insolvent over the next 30 years and would not fully repay their loans. For those plans that do repay their loans, the CBO projects that they will become insolvent within ten years of repayment.” What’s the issue?

At present, there are roughly 125 multiemployer pension plans that are defined as critical and declining.  With no action, all of these plans are expected to become insolvent within the next 15 years. By providing loans to these struggling plans, we are extending the payment of benefits by 30+ years. If 25% fail to repay the loan in 30-years, so be it. We’ve renegotiated terms on a number of government-funded programs, why should this be any different.

The CBO estimated that the Pension Rehabilitation Administration (PRA), which would be established to issue the loans, would only have to provide $39.7 billion in funding. Seems like a drop in the bucket when compared to TARP. Furthermore, they estimated that only $7.9 billion would be returned. I’d love to understand the inputs that they used in creating this analysis. When Cheiron, a leading pension actuary, conducted their analysis on the original 114 plans, only 3 – the Central States, Coal Miners, and the Bakery, Confectionery, Tobacco Workers – would need extra support from the PBGC. In fact, the remaining 111 plans could meet current benefit payments, interest on the loan, future pension liabilities, and the balloon payment in 30-years while earning only 6.5% on their investments.

Given the modest cost of this loan program and the economic benefit of continuing to provide pension payments to nearly 1.3 million American workers, it seems like a no-brainer to me.  What is the economic benefit? According to Congressional testimony, the “cost of doing nothing in terms of lost tax revenue and increased social safety net spending is estimated to be between $170.3 billion and $241.3 billion over the 10-year budget window, and between $332 billion and $479 billion over the next 30 years.”

So, please explain to me why we, as taxpayers, wouldn’t want to “invest” $39.7 billion in a loan program that has, in my humble opinion, a high degree of success, when not doing so would potentially result in a “loss” of nearly $500 billion in economic activity in the next 30-years?  I would hope that ideology isn’t getting in the way of making a rational decision to finally tackle the pension problem that has existed for decades and one that will only get worse with the passage of more time.


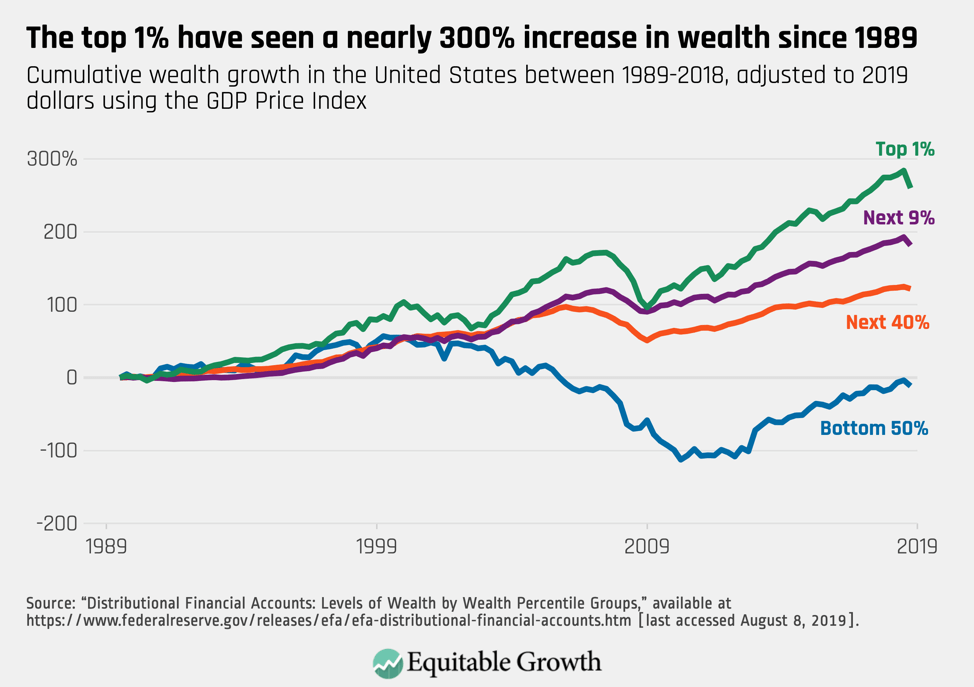
Think the Bottom 50% Can Fund A Retirement Account? Think, Again!

Image

The move away from defined benefit pension plans to defined contribution plans has coincided with stagnant wage growth and no growth in wealth for roughly half the U.S. population. The impact is devastating. How can anyone expect these individuals to meet their basic needs of housing, food, insurance, clothing, education, etc. while also diverting a sum of money to a future liability? It isn’t happening and it won’t! We need to preserve and protect the traditional DB plans that remain, while also figuring out how we can get the bottom 50% participating in our economy to a greater extent.

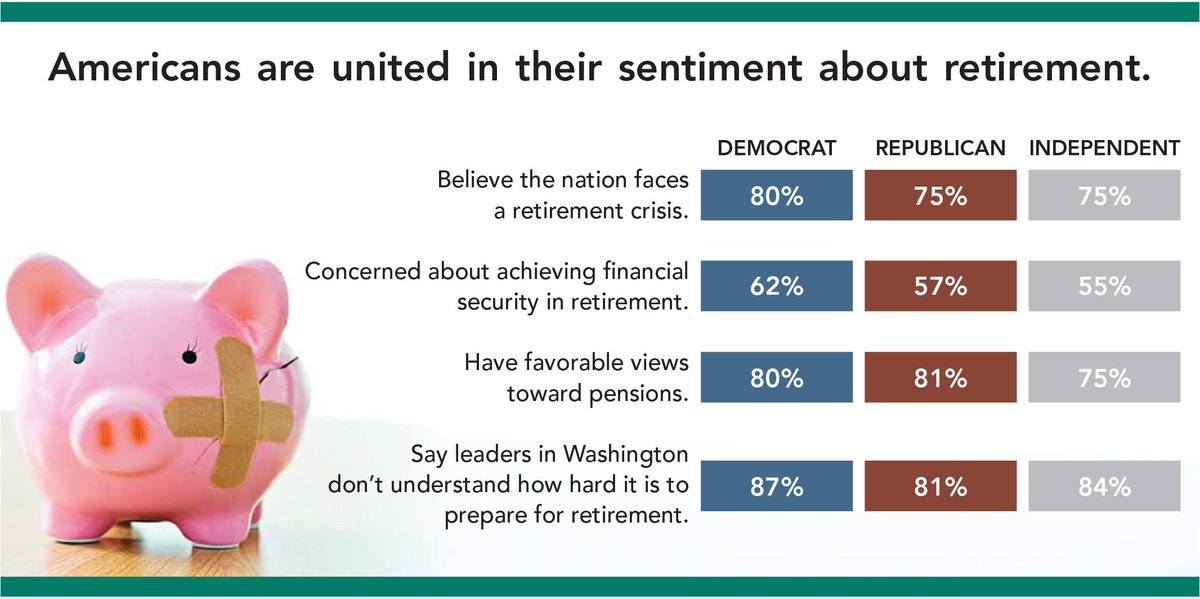
Can we all be wrong?

The following information was provided by the National Institute on Retirement Security. It clearly demonstrates that retirement security is not and should not be a political issue. Most Americans have suffered from weak real wage growth for decades. As a result, they are having great difficulty building the necessary retirement nest egg. Congress has the opportunity to secure the pensions for millions of Americans at this time. Will they continue to let ideology dictate the path forward or will they finally do what is best for the people that they represent?

Image